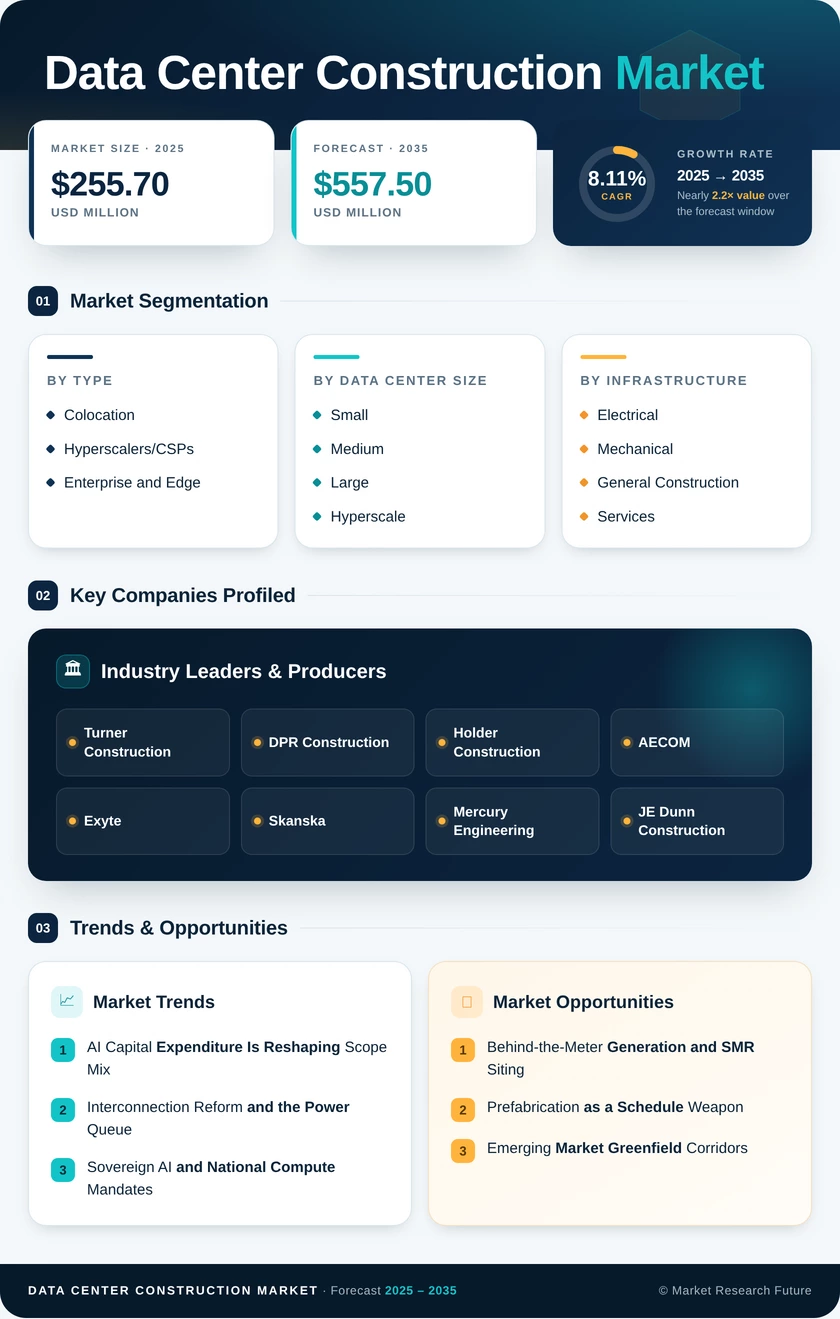
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| By Tier Type | Tier 1 and 2; Tier 3; Tier 4 | Tier 3 | Tier 4 |
| By Data Center Size | Small; Medium; Large; Hyperscale | Hyperscale | Hyperscale |
| By Data Center Type | Colocation; Hyperscalers/CSPs; Enterprise and Edge | Hyperscalers/CSPs | Hyperscalers/CSPs |
| By Infrastructure | Electrical; Mechanical; General Construction; Services | Electrical | Services |
| By Geography | North America; South America; Europe; Asia-Pacific; Middle East & Africa | North America | Asia-Pacific |
Market Segmentation Overview
By Tier Type
| Sub-Segment | Key Trend |
| Tier 1 and 2 | Confined to edge nodes and telco central offices; declining share as enterprise on-premise retreats. |
| Tier 3 | Commercial default for colocation and cloud availability zones; concurrent maintainability at moderate cost |
| Tier 4 | Fastest expansion as sovereign, defence, and financial buyers specify fault tolerance for inference workloads. |
Tier classification increasingly functions as a procurement filter rather than an engineering ideal. Buyers specify Tier 3 for the bulk of capacity and reserve Tier 4 for workloads where an outage carries regulatory or national-security consequence.
By Data Center Size
| Sub-Segment | Key Trend |
| Small | Edge and metro pods sized under 5 MW; growth tied to inference latency requirements |
| Medium | Regional enterprise and government facilities; steady but unspectacular expansion |
| Large | Wholesale colocation campuses in the 50–200 MW band |
| Hyperscale | Master-planned campuses above 500 MW; rolling multi-year construction programmes |
Scale is the defining economic variable. Hyperscale campuses achieve materially lower cost per MW through repeatable design and long-run procurement leverage, which is why the segment continues to absorb a rising share of total capital deployed.
By Data Center Type
| Sub-Segment | Key Trend |
| Colocation | Wholesale pre-leasing to cloud tenants dominates; speculative build has all but ceased |
| Hyperscalers/CSPs | Self-build where power is securable; largest single demand cohort |
| Enterprise and Edge | Structural decline on-premise, partially offset by edge densification |
Ownership model dictates risk allocation. Hyperscale self-build typically runs under guaranteed maximum price with open-book procurement, while colocation developers carry more of the completion and lease-up risk themselves.
By Infrastructure
| Sub-Segment | Key Trend |
| Electrical | Substations, UPS, switchgear and busway; now the largest scope category |
| Mechanical | Liquid cooling, coolant distribution units and facility water loops replacing CRAH arrays |
| General Construction | Shell, civils and structural steel; steady share, commoditised pricing |
| Services | Design, commissioning and programme management; fastest-growing scope element |
Scope composition has inverted since 2023. Rising rack density pushed medium-voltage distribution into the data hall and raised the engineering content of every megawatt delivered, lifting both electrical and services scope at the expense of general construction.
just now
Opus 5 High


 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA