Curcumin Market (2026 - 2035)

Curcumin Market Size, Share, Industry Trend & Analysis Research Report By Form (Powder, Liquid), By Nature (Organic, Conventional), By Application (Dietary Supplement, Food and Beverages, Cosmetic and Personal Care, Others), By Geography (North America, Europe, Asia-Pacific, South America, Middle East & Africa) - Forecast to 2035
ID: MRFR/FnB/6353-HCR 200 Pages Snehal Singh Last Updated: September 15, 2026
Curcumin Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)10.5%
2025 Market SizeUSD 115.32 Million
2035 Market SizeUSD 312.45 Million
Key Players
Sabinsa Corporation
Indena S.p.A.
Synthite Industries
Arjuna Natural
DolCas Biotech
Theravalues Corporation
Opportunities
  • Clinical-Grade Curcumin for Adjunct Oncology
  • Personalized Wellness and DTC Subscription Models
  • African and ASEAN Cultivation Hubs
 

Curcumin Market Summary

The Curcumin Market reached USD 115.32 Million in 2025 and is projected to begin 2026 at approximately USD 127.43 Million, scaling to USD 312.45 Million by 2035 at a 10.5% CAGR. Two catalysts anchor this trajectory: the U.S. FDA's continued GRAS recognition for curcumin formulations and India's USD 580 million Production Linked Incentive scheme for nutraceutical and botanical extracts, which has unlocked fresh extraction capacity in Andhra Pradesh and Telangana. Editorial buyer interest is now squarely focused on turmeric curcumin bioavailability and clinically validated extracts that perform in randomized trials.

Manufacturing economics are transforming as legacy solvent-based extraction yields to supercritical CO₂ and enzyme-assisted processes that lift purity beyond 95% curcuminoids. Capital expenditure in green extraction lines exceeded USD 240 million globally between 2023 and 2025, with European processors leading retrofits. The shift addresses the central commercial pain point — poor oral absorption — through curcumin nanoparticle delivery, phytosome complexes, and micellar systems that lift plasma bioavailability up to 185-fold versus standard powder.

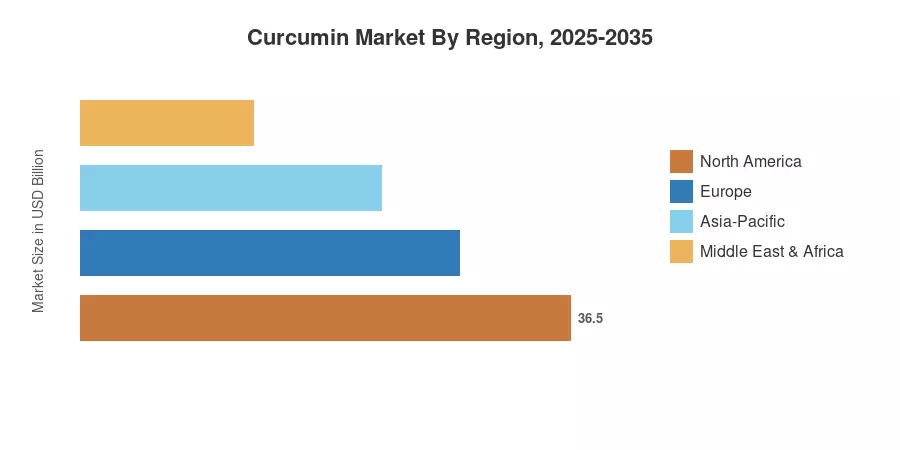
Asia-Pacific anchors the Curcumin Market at roughly 32% revenue share, propelled by India's farm-to-extract integration and China's nutraceutical export base. The Middle East & Africa registers the fastest expansion at 12.1% CAGR, riding on GCC wellness retail and South African functional food adoption. North America holds second position with 27% share, driven by a curcumin anti-inflammatory supplement category that continues outpacing the broader herbal segment. The decade ahead will reward processors who own both upstream agronomy and downstream formulation IP.

Key Report Takeaways

• By Form

  • Powder retains category leadership in the Curcumin Market with approximately 68% revenue share in 2025, anchored by bulk supplement and food coloring demand
  • Liquid extracts are the fastest-growing form at 12.6% CAGR, lifted by ready-to-drink wellness shots and beverage fortification

• By Nature

  • Conventional curcumin generates USD 88.5 Million in 2025 revenue across the Curcumin Market, reflecting cost-driven bulk procurement
  • Organic curcumin expands at 13.1% CAGR through 2035 as clean-label, and EU Organic certification pressures intensify

• By Application

  • Food and beverage captures roughly 31% of the Curcumin Market in 2025, led by natural color replacement of synthetic yellow dyes
  • Cosmetics and personal care record the fastest application growth at 13.0% CAGR through 2035

• By Region

  • Asia-Pacific dominates with about 32% revenue share, supported by India's processing scale
  • Middle East & Africa grows fastest at 12.1% CAGR through 2035
  • Europe holds USD 27.8 Million in 2025, anchored by EFSA-cleared supplement channels

Market Size and Forecast (2021–2035)

Historical figures draw from customs data on turmeric oleoresin exports, USDA AMS organic certification rolls, and corporate filings from publicly listed extractors. Forecast values reflect MRFR's bottom-up application modeling, calibrated against the EFSA Acceptable Daily Intake framework and clinical pipeline trends. The Curcumin Market shows a moderate but consistent expansion path, with one visible spike in 2024 tied to post-pandemic immunity supplement restocking cycles.
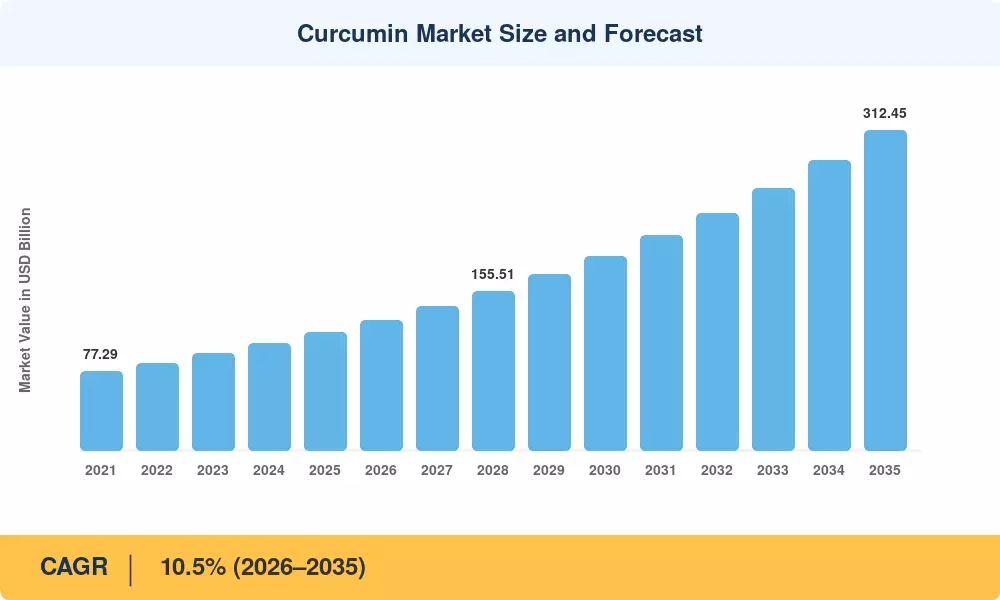
Curcumin Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry


Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Rising chronic inflammation prevalence +2.4% Global Long-term
Advances in turmeric curcumin bioavailability +2.1% NA, EU, APAC Medium-term
Clean-label and natural color substitution +1.8% EU, NA Medium-term
Curcumin nutraceutical market expansion +1.6% Global Long-term
Cosmeceutical and topical innovation +1.2% APAC, NA Medium-term
Pet supplement adoption +0.7% NA, EU Short-term
Sports nutrition recovery formulations +0.6% NA, APAC Short-term


Rising Chronic Inflammation Prevalence

The WHO reported in March 2025 that nearly 18% of adults globally live with chronic musculoskeletal conditions, with India alone accounting for over 180 million arthritis cases [5]. This burden has elevated the curcumin anti-inflammatory supplement category from a niche herbal product to a mainstream OTC tier. U.S. retail data shows curcumin SKUs ranked among the top five botanical supplements by dollar sales in 2024, with category growth of 14% year-over-year [12].

Bioavailability Engineering Breakthroughs

The oral bioavailability of standard curcumin powder is less than 1%, an issue that bioformulation science has vigorously addressed. Meriva phytosome, Theracurmin colloidal dispersion, and CurcuWIN multi-component complexes are examples of patented systems that increase plasma concentration by 27–185 times [6]. Curcumin nanoparticle delivery technologies are starting Phase II oncology adjunct trials at MD Anderson and Tata Memorial Center, and Sabinsa's Curcumin C3 Complex alone has anchored over 80 clinical investigations.


Natural Color Substitution Mandate

The European Commission's progressive restriction of synthetic dyes — including the 2024 ban on titanium dioxide (E171) and growing pressure on tartrazine — has redirected demand toward turmeric-derived natural colors. The Curcumin Market benefits directly because curcumin (E100) is an approved natural yellow with both color and functional health positioning [7]. Major confectionery and dairy reformulations announced by Nestlé, Unilever, and Danone reference E100 as a replacement ingredient in 2024 disclosures.


Restraints Impact Analysis

Restraints are evaluated using the same directional logic as drivers. They erode baseline CAGR rather than subtract additively. The Curcumin Market faces real cost, quality, and regulatory headwinds that require active mitigation.

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
Raw turmeric price volatility -1.7% Global Short-term
Adulteration and lead contamination -1.4% NA, EU Medium-term
Inconsistent curcumin extraction standardization -1.2% Global Medium-term
Stringent EFSA novel food rules -0.9% EU Long-term
Climate stress on Indian turmeric belts -0.7% APAC Long-term


Raw Material Price Volatility

Indian turmeric mandi prices swung from INR 7,200 per quintal in early 2023 to over INR 18,500 in July 2024 before correcting to INR 12,400 by mid-2025 . Erratic monsoon patterns in Telangana and Maharashtra — India's twin curcumin-grade turmeric belts — drove the spike. Such volatility compresses extractor margins and complicates long-term contract pricing with branded supplement buyers.

Adulteration and Heavy Metal Concerns

Lead chromate contamination in imported turmeric and curcumin powder from specific Bangladeshi and Indian sources was the subject of U.S. FDA recalls in 2023 and 2024 [14]. Since then, NSF International and USP have tightened heavy metal restrictions below 2 ppm, increasing unbranded suppliers' compliance costs by 8–12%. The most frequently mentioned quality risk by procurement teams is still the difference in curcumin extraction standards between certified and uncertified output.


Standardization Inconsistency

There is currently no worldwide purity reference for the curcumin market. The curcuminoid quantification techniques used by the Indian Pharmacopoeia, USP, and EP differ slightly, and customers of food-grade and supplement-grade turmeric oleoresin have different requirements [15]. Cross-border formulation harmonization is slowed down by this fragmentation, especially for multinational supplement companies that need to reformulate for each market.


Curcumin Market Opportunities

Clinical-Grade Curcumin for Adjunct Oncology

Investigator-led trials at NCI-designated cancer centers are evaluating high-bioavailability curcumin as a supportive therapy in colorectal and pancreatic cancer protocols. With over 320 active clinical trials registered as of mid-2025, a successful Phase III readout would unlock medical-channel reimbursement and reposition curcumin from supplement to therapeutic adjunct The estimated incremental opportunity exceeds USD 45 million by 2032 [18].

Personalized Wellness and DTC Subscription Models

Direct-to-consumer brands like Care/of, Persona, and Bulletproof have integrated curcumin into algorithm-driven supplement stacks. Monthly subscription economics generate roughly 3x higher customer lifetime value than retail SKUs, opening data monetization through ingredient performance tracking Expansion into India's e-pharmacy channel via PharmEasy and Tata 1mg amplifies the curcumin nutraceutical market reach.

African and ASEAN Cultivation Hubs

Vietnam, Indonesia, and Nigeria are scaling commercial turmeric cultivation under World Bank-backed agribusiness programs, with combined acreage growing 22% between 2022 and 2025 [19]. This geographic diversification reduces overreliance on Indian supply and creates origin-differentiated curcumin tiers — opening premium-priced single-origin SKUs.

Functional Beverage Penetration

Curcumin-fortified kombucha, golden milk lattes, and recovery shots represent a USD 1.2 billion adjacent beverage opportunity by 2030 Liquid formulations using cyclodextrin encapsulation solve the bitter taste and water-insolubility barriers that historically blocked beverage integration.

Veterinary and Pet Wellness

The premium pet supplement category grew 19% in 2024, with joint-health formulas containing curcumin emerging as a high-margin sub-segment. Zesty Paws, Nutramax, and Vetnique have launched curcumin-piperine joint chews targeting senior dogs — an underpenetrated channel projected to add USD 28 Million in curcumin demand by 2030.


Curcumin Market Future Outlook

AI-Driven Formulation Optimization

Machine learning platforms from Brightseed and Spoonshot are screening botanical phytochemicals for synergistic combinations, with curcumin emerging as a high-frequency anchor molecule. By 2028, MRFR expects roughly 25% of new curcumin SKUs to be developed using AI-assisted formulation, accelerating time-to-market by an estimated 40% . This methodology also feeds clinical trial design by predicting which curcumin nanoparticle delivery system pairs best with target patient phenotypes.

Vertically Integrated Platform Economics

The next decade favors processors that own farm, extraction, and brand. Olene Life Sciences, Synthite Industries, and Sabinsa have invested over USD 180 million collectively in vertical integration since 2022. Vertically integrated platforms achieve 15–22% higher EBITDA margins than spot-market extractors and are better positioned to weather raw material volatility

Sustainability and Carbon-Footprint Reporting

EU Corporate Sustainability Reporting Directive (CSRD) requirements apply to nutraceutical manufacturers above EUR 40 million turnover from 2025, mandating Scope 3 emissions disclosure for ingredient supply chains [27]. Curcumin extractors using supercritical CO₂ technology report 35–45% lower carbon intensity versus conventional ethanol extraction — a tangible procurement advantage as Unilever, Nestlé, and L'Oréal apply supplier carbon scorecards.

Precision Wellness and Diagnostics-Linked Supplementation

The convergence of at-home inflammation biomarker testing (hs-CRP, IL-6) with personalized supplement subscriptions creates demand for clinically dosed curcumin formats. By 2030, MRFR estimates 8–10% of premium curcumin sales will be tied to a measured biomarker outcome rather than generic wellness claims This shifts the curcumin nutraceutical market toward outcome-based pricing models.


Regional Market Share Analysis

Region 2025 Share (%) Primary Investment Themes
Asia-Pacific 32.0 Vertical integration, organic cultivation
North America 27.0 Bioavailability IP, clinical claims
Europe 24.1 EFSA-cleared formulations, natural color
South America 9.8 Cosmetic exports, Andean botanicals
Middle East & Africa 7.1 GCC wellness retail, halal certification
Total 100.0 —


North America

Country 2025 USD Million Key Driver
US 26.45 Curcumin anti-inflammatory supplement leadership
Canada 4.20 Natural Health Products Regulations clarity
Mexico 0.49 Cosmetic export demand


The U.S. anchors the Curcumin Market in this region through a mature dietary supplement framework under DSHEA, with retail giants Costco, GNC, and Sprouts dedicating end-cap real estate to curcumin SKUs. Health Canada's NPN approval pathway has cleared over 1,800 curcumin-containing products as of 2024 [21]. Mexico remains modest but rising, driven by cosmetic exporters in Jalisco sourcing curcumin for natural skincare lines.

Europe

Country Share of Region (%) Key Driver
Germany 24.1 Pharmacy retail channel
UK 19.6 Sports nutrition adoption
France 16.8 Pharmacy-cosmetic crossover
Italy 14.2 Mediterranean diet positioning
Spain 9.7 Functional food innovation
Nordic Countries 7.5 Clean-label premium
Russia 4.1 Traditional wellness retail
Rest of Europe 4.0 Independent health stores


EFSA's structured health-claim regime keeps the European Curcumin Market disciplined but credible. Germany's apotheke (pharmacy) network treats curcumin as a borderline medicinal product, supporting premium pricing. France leverages the Indena and Naturex supply ecosystem, while the UK's sports nutrition giants — including Myprotein and Optimum Nutrition — have launched curcumin recovery stacks since 2023.

Asia-Pacific

Country 2025 CAGR (%) Key Driver
China 11.4 TCM modernization
India 11.9 Domestic supplement boom
Japan 9.6 Hangover and liver tonics
South Korea 10.8 K-beauty cosmeceuticals
ASEAN 12.2 Functional beverage growth
Rest of Asia-Pacific 9.4 Traditional medicine demand


India remains the production heart of the Curcumin Market, controlling roughly 78% of global turmeric output and the majority of standardized extract capacity. The Ministry of AYUSH's USD 240 million budget allocation for 2024–25 supports botanical R&D and export promotion [23]. Japan's curcumin demand is anomalous and culturally specific — Honda turmeric drinks marketed as hangover remedies represent a USD 90 million sub-category alone.

South America

Country 2025 Share of Region (%) Key Driver
Brazil 64.1 Cosmetic exports
Argentina 19.8 Functional foods
Rest of South America 16.1 Andean herbal retail


Brazil's ANVISA classified curcumin as a permitted bioactive in 2023, opening labeled health-claim pathways for supplement and functional beverage brands [24]. Domestic cultivation in Goiás and Mato Grosso reduces import dependence and supports a growing curcumin nutraceutical market positioned around the Pantanal botanicals narrative.

Middle East & Africa

Country 2025 USD Million Key Driver
Saudi Arabia 2.40 Vision 2030 wellness push
UAE 1.95 Premium retail and tourism
South Africa 1.85 Functional food adoption
Egypt 1.05 Traditional medicine demand
Rest of MEA 0.94 Halal supplement channels


The Saudi Food and Drug Authority's 2024 health supplement framework cleared curcumin under registered botanical extract categories, enabling pharmacy distribution through Nahdi and Al-Dawaa chains [25]. Halal-certified curcumin from Indian processors commands a 12–18% premium across GCC retail, reflecting the region's procurement preferences.

Curcumin Market By Region, 2025-2035
 

Curcumin Market Segmentation

By Form

Segment 2025 Share / Metric Primary Demand Driver
Powder 68.0% share Bulk supplement and food coloring
Liquid 12.6% CAGR RTD wellness beverages


Powder remains the workhorse format in the Curcumin Market, anchoring cost-sensitive bulk applications including capsules, tablets, and food coloring premixes. It also serves the Indian household culinary segment, although that volume falls outside extract-grade taxonomy. Liquid extracts grow fastest because they deliver pre-solubilized curcumin in functional beverages, condensed shots, and topical cosmetic emulsions — solving the central absorption problem at the formulation stage rather than at digestion.

By Nature

Segment 2025 Metric Primary Demand Driver
Conventional USD 88.5 Million Cost-driven bulk procurement
Organic 13.1% CAGR Clean-label premium demand


Conventional curcumin dominates the Curcumin Market by absolute volume because price-sensitive applications — including industrial food coloring and mass-market supplements — prioritize unit economics over certification. Organic curcumin commands a 35–55% retail premium, supported by USDA Organic, EU Organic, and India Organic certifications. European clean-label pressures and DTC supplement brand positioning are the primary growth catalysts.

By Application

Segment 2025 Metric Primary Demand Driver
Dietary Supplement 30.4% share Anti-inflammatory positioning
Food and Beverage USD 35.75 Million Natural color substitution
Cosmetic and Personal Care 13.0% CAGR Skin brightening and acne formulations
Others 8.2% share Animal nutrition and textiles


Dietary supplements lead the Curcumin Market on value, with joint health, immunity, and cognitive function being the three most cited claims on U.S. retail labels in 2024. Food and beverage absorbs the bulk of volume — turmeric latte mixes, golden milk lines, and curry mixes — but at lower per-kilogram pricing. Cosmetics and personal care grow fastest because K-beauty and Ayurveda-positioned skincare brands have made curcumin a hero ingredient for sensitive and acne-prone skin.


Competitive Benchmarking

The Curcumin Market remains fragmented with a Herfindahl-Hirschman Index estimated near 720, signaling low concentration. The top five players collectively command approximately 38–42% revenue share, with no single firm exceeding 12%. Competitive intensity centers on patented bioavailability platforms, organic certification, and downstream brand partnerships rather than commodity pricing.

Company Est. Revenue Share Range Key Offerings for the Curcumin Market Strategic Positioning
Sabinsa Corporation 9–12% Curcumin C3 Complex, BioPerine Patent leadership, clinical IP
Indena S.p.A. 7–10% Meriva phytosome Premium pharma-grade
Synthite Industries 6–9% Bulk oleoresin, organic curcumin Vertical integration
Arjuna Natural 5–8% BCM-95 turmeric extract Bioavailability IP
DolCas Biotech 4–7% CurcuWIN multi-complex Multi-component delivery
Theravalues Corporation 4–6% Theracurmin colloidal dispersion Japanese clinical leadership
Olene Life Sciences 3–6% Standardized 95% curcuminoids Farm-to-extract integration
Star Hi Herbs 3–5% Organic curcumin, water-dispersible Clean-label specialist
Naturex (Givaudan) 3–5% Natural color and supplement extracts Color and flavor crossover
Biomax Life Sciences 2–4% Curcugen complete root extract Whole-spectrum positioning


Recent News & Developments

  • Sabinsa (March 2025): Received self-affirmed GRAS for a new water-dispersible Curcumin C3 Reduct, expanding beverage application potential [28]
  • Indena (November 2024): Announced EUR 32 million expansion of its Settala, Italy facility, doubling Meriva phytosome capacity [29]
  • Arjuna Natural (July 2024): Published Phase II clinical results for BCM-95 in major depressive disorder, hitting the primary endpoint [30]
  • EFSA (October 2024): Updated curcumin Acceptable Daily Intake guidance, retaining 3 mg/kg body weight threshold while clarifying combined turmeric extract exposure [16]
  • Synthite (May 2024): Acquired a 220-acre organic turmeric estate in Karnataka to support EU-organic export contracts [31]
  • DolCas Biotech (February 2024): Licensed CurcuWIN technology to a major North American sports nutrition brand for pre-workout recovery line [32]
  • Theravalues (September 2023): Launched Theracurmin SD spray-dried format for capsule-friendly applications across Asian markets [33]
  • U.S. FDA (April 2024): Issued import alert on three turmeric suppliers for lead chromate adulteration, tightening procurement scrutiny [14]

Curcumin Market Report Scope

Parameter Detail
Market Scope Global Curcumin Market by Form, Nature, Application, and Geography
Study Period 2021–2035
Base Year 2025
Forecast Period 2026–2035
CAGR 10.5% (2026–2035)
Market Size (2025) USD 115.32 Million
Market Size (2035) USD 312.45 Million
Fastest Growing Segments Liquid form, Organic nature, Cosmetic & Personal Care application
Companies Profiled Sabinsa, Indena, Synthite, Arjuna Natural, DolCas, Theravalues, Olene Life Sciences, Star Hi Herbs, Naturex (Givaudan), Biomax
Valuation Currency USD Million

FAQs

What due diligence should procurement teams perform before signing a curcumin supply contract for the Curcumin Market?
Audit the supplier's third-party heavy metal certificates (USP, NSF), verify pesticide residue testing under FSSAI or EU 396/2005, and confirm DNA-barcoded turmeric authenticity. Request batch-level COAs covering at least 12 months [14].
How do patented bioavailability platforms affect pricing power in the Curcumin Market?
Patented systems like Meriva, BCM-95, and Theracurmin command 4x to 7x the bulk curcumin price per gram. Their clinical evidence base allows premium label claims, locking out generic competitors until patent expiry [6].
What integration challenges arise when adding curcumin to beverage formulations in the Curcumin Market?
Native curcumin is water-insoluble, photosensitive, and bitter. Manufacturers must use cyclodextrin complexes, micellar systems, or emulsified delivery to achieve clarity, taste neutrality, and 12-month shelf stability in finished beverages [33].
How does EFSA's Acceptable Daily Intake guidance shape product positioning in Europe?
EFSA caps curcumin at 3 mg/kg body weight per day, including dietary curry consumption. European brands must calibrate supplement doses against background exposure, often capping daily intake at 200–300 mg per serving [16].
Which emerging use case offers the highest unit economics in the Curcumin Market?
Clinical-grade curcumin in oncology adjunct therapy delivers the highest gross margin, with hospital-channel pricing 8–10x retail supplement levels. Successful Phase III readouts could unlock medical reimbursement pathways [18].
How should investors think about competitive moats in the Curcumin Market?
Sustainable moats sit in three layers: vertically integrated organic farms, patented delivery IP, and clinical evidence portfolios. Pure-play extractors without one of these layers face commoditization pressure as Indian processing capacity expands
What regulatory shift could most disrupt the Curcumin Market over the next five years?
Reclassification of high-bioavailability curcumin as a borderline medicinal product in the EU would force pharmaceutical-grade GMP compliance. This would raise barriers but also unlock pharmacy-channel pricing for compliant manufacturers [16].
Author
Author Author Profile Snehal Singh LinkedIn Manager - Research
High acumen in analyzing complex macro & micro markets with more than 6 years of work experience in the field of market research. By implementing her analytical skills in forecasting and estimation into market research reports, she has expertise in Packaging, Construction, and Equipment domains. She handles a team size of 20-25 resources and ensures smooth running of the projects, associated marketing activities, and client servicing.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of regulatory filings, clinical trial databases, agricultural commodity reports, and peer-reviewed phytochemical literature. Key sources included the US Food & Drug Administration (FDA), European Food Safety Authority (EFSA), Food Standards Australia New Zealand (FSANZ), Food Safety and Standards Authority of India (FSSAI), National Institutes of Health (NIH) Office of Dietary Supplements, National Center for Biotechnology Information (NCBI/PubMed), Cochrane Library, ClinicalTrials.gov, World Health Organization (WHO) Traditional Medicine Center, Food and Agriculture Organization (FAO) FAOSTAT, Spices Board of India, American Botanical Council (ABC), Natural Products Association (NPA), European Spice Association (ESA), United Nations Comtrade Database, ITC Trade Map, and national agricultural ministry reports from India, China, and Vietnam. These sources were utilized to collect extraction volume statistics, standardization protocols (95% curcuminoids), clinical efficacy studies, GRAS (Generally Recognized as Safe) notification data, import-export trade flows, and bioavailability enhancement technology patents for turmeric-derived formulations, synthetic curcumin analogs, and nanoparticle delivery systems.


Primary Research

As part of the initial research process, stakeholders from both the supply and demand sides were interviewed to get both qualitative and quantitative information. CEOs, Heads of Extraction Operations, Phytochemistry R&D Directors, and Regulatory Affairs Managers from botanical extract makers, curcumin refiners, and standard ingredient suppliers were some of the supply-side sources. Formulation Scientists, Procurement Directors, and Brand Managers from nutraceutical supplement companies, functional food and beverage makers, cosmetic formulators, and pharmaceutical development teams were demand-side sources. Primary research confirmed market segmentation for pharmaceutical-grade, food-grade, and cosmetic-grade curcumin. It also confirmed standardized extract pipeline timelines for formulations like C3 Complex, Meriva, Longvida, and Theracurmin. The research also gathered information on clinical adoption in anti-inflammatory therapies, sports nutrition positioning, clean-label coloring applications, and integrating Ayurvedic medicine.

Primary Respondent Breakdown:

• By Designation: C-level Primaries (28%), Director Level (35%), Others (37%)

• By Region: North America (32%), Europe (25%), Asia-Pacific (35%), Rest of World (8%)


Market Size Estimation

Global market valuation was derived through production volume mapping and standardized extract pricing analysis. The methodology included:

• Identification of 60+ key manufacturers and extraction facilities across India (Erode, Nizamabad, Sangli), China, and European refining centers

• Product mapping across solvent-extracted 95% curcuminoid powder, supercritical CO2 extracts, water-dispersible formulations, and synthetic analogs

• Analysis of reported and modeled annual revenues specific to curcumin ingredient portfolios, including toll manufacturing and private label supply agreements

• Coverage of manufacturers representing 65-70% of global market share in 2024

• Extrapolation using bottom-up (turmeric rhizome processing volume × extraction yield × standardization premium by country) and top-down (ingredient supplier revenue validation) approaches to derive segment-specific valuations for pharmaceutical applications, dietary supplements, functional foods, and cosmetic formulations

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.


















