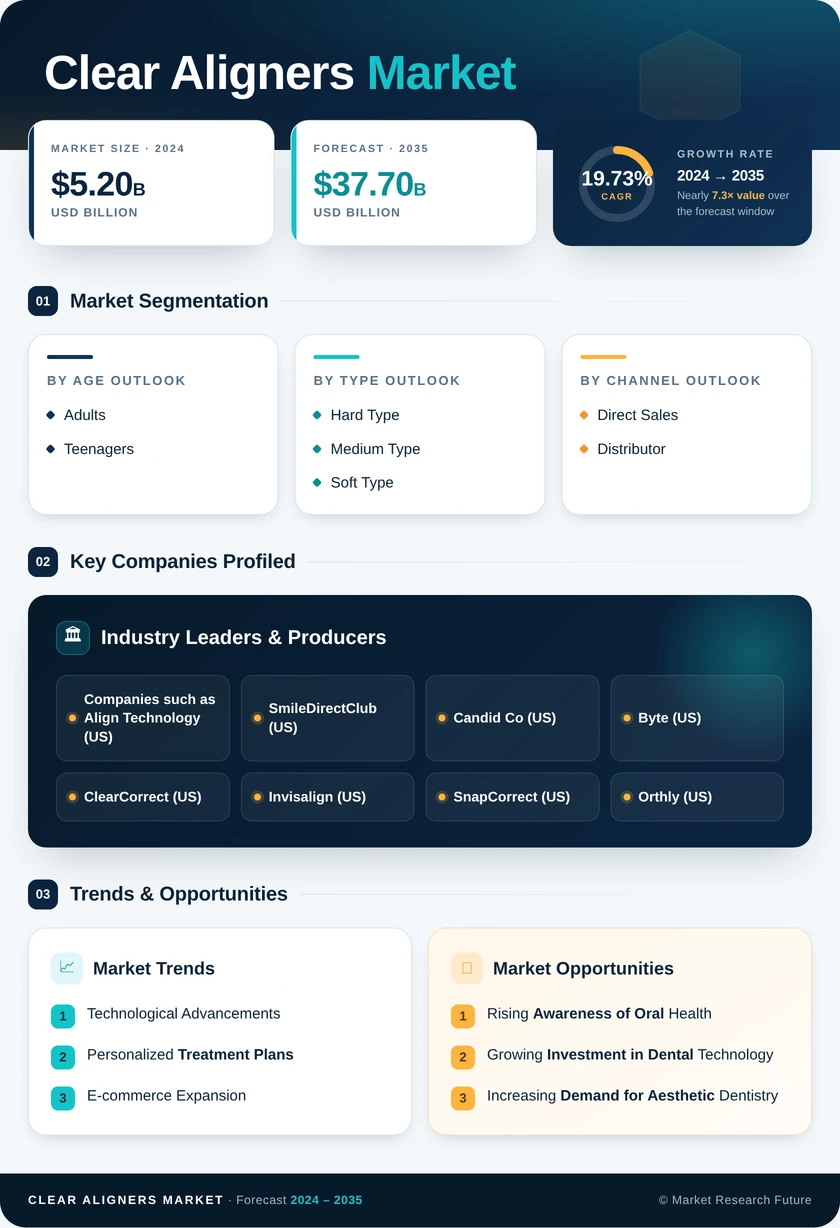
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| By Age | Adults; Teens | Adults | Teens |
| By Manufacturing Workflow | Centralized Lab-Manufactured; In-Office 3D-Printed | Centralized Lab-Manufactured | In-Office 3D-Printed |
| By Material Type | Multilayer Medical-Grade Polyurethane; PET-G; Thermoplastic Polyurethane; Others | Multilayer Medical-Grade Polyurethane | PET-G |
| By End User | Stand-Alone Practices; Dental Service Organizations; Hospitals; Others | Stand-Alone Practices | Hospitals |
| By Distribution Channel | Online; Offline | Offline | Online |
| By Geography | North America; Europe; Asia-Pacific; South America; Middle East & Africa | North America | Asia-Pacific |
Market Segmentation Overview
By Age
| Sub-Segment | Key Trend |
| Adults | Workplace-driven aesthetic demand sustains premium pricing and the largest revenue base. |
| Teens | Compliance-tracking features and parental acceptance drive the fastest cohort expansion |
Adult treatment underwrites category profitability while teen volumes supply momentum. Practices increasingly design dual-track marketing — professional discretion messaging for adults, outcome and compliance assurance for parents — because the two cohorts respond to entirely different arguments.
By Manufacturing Workflow
| Sub-Segment | Key Trend |
| Centralized Lab-Manufactured | Retains scale advantages, validated quality systems, and existing regulatory registrations |
| In-Office 3D-Printed | Same-day refinements and lower per-case cost accelerate practice-level adoption. |
Production is decentralizing without displacing centralized capacity outright. Most practices will run hybrid operations through 2030 — printing refinements and retainers in-house while outsourcing initial full-case series.
By Material Type
| Sub-Segment | Key Trend |
| Multilayer Medical-Grade Polyurethane | Superior force retention keeps it the clinical standard for complex movement. |
| PET-G | Cost efficiency drives value-tier and emerging-market product lines. |
| Thermoplastic Polyurethane | Flexibility suits early-stage staging and comfort-focused offerings. |
| Others (Copolyester, Direct-Print Resins) | Shape-memory resins and recyclable polymers respond to printing and sustainability demands. |
Material choice now doubles as regulatory strategy. European lifecycle disclosure requirements are pushing suppliers toward bio-based and recyclable formulations well ahead of clinical necessity.
By End User
| Sub-Segment | Key Trend |
| Stand-Alone Practices | Majority of chairs, though share erodes as acquisition activity continues |
| Dental Service Organizations | Procurement scale and centralized marketing compress case pricing |
| Hospitals | Surgical-orthodontic and cleft care programs drive fastest institutional growth. |
| Others | Academic, military, and public dental services expand slowly from a small base. |
Ownership structure increasingly determines purchasing behavior. Consolidated groups negotiate at the enterprise level, shifting supplier relationships from clinical preference toward contract economics.
By Distribution Channel
| Sub-Segment | Key Trend |
| Offline | Clinician-supervised diagnosis remains the trust anchor after remote-only contraction. |
| Online | Hybrid teledentistry monitoring reduces required chair visits and lifts channel growth. |
Digital channels rebuilt themselves around supervision rather than replacing it. The surviving online model complements clinics instead of competing with them, which is precisely why regulators now tolerate it.
By Geography
| Sub-Segment | Key Trend |
| North America | Financing depth and DSO scale sustain the largest revenue pool |
| Europe | Medical Device Regulation compliance consolidates share toward certified manufacturers. |
| Asia-Pacific | Domestic manufacturing and value-tier pricing deliver the steepest growth curve. |
| South America | Installment payment culture and Brazilian production capacity support steady expansion. |
| Middle East & Africa | Gulf clinic licensing reform and dental tourism concentrate regional value. |
Geographic performance tracks payer architecture more closely than clinical need. Markets that solve affordability — through insurance, credit, or domestic manufacturing — convert latent demand into revenue fastest.


 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA