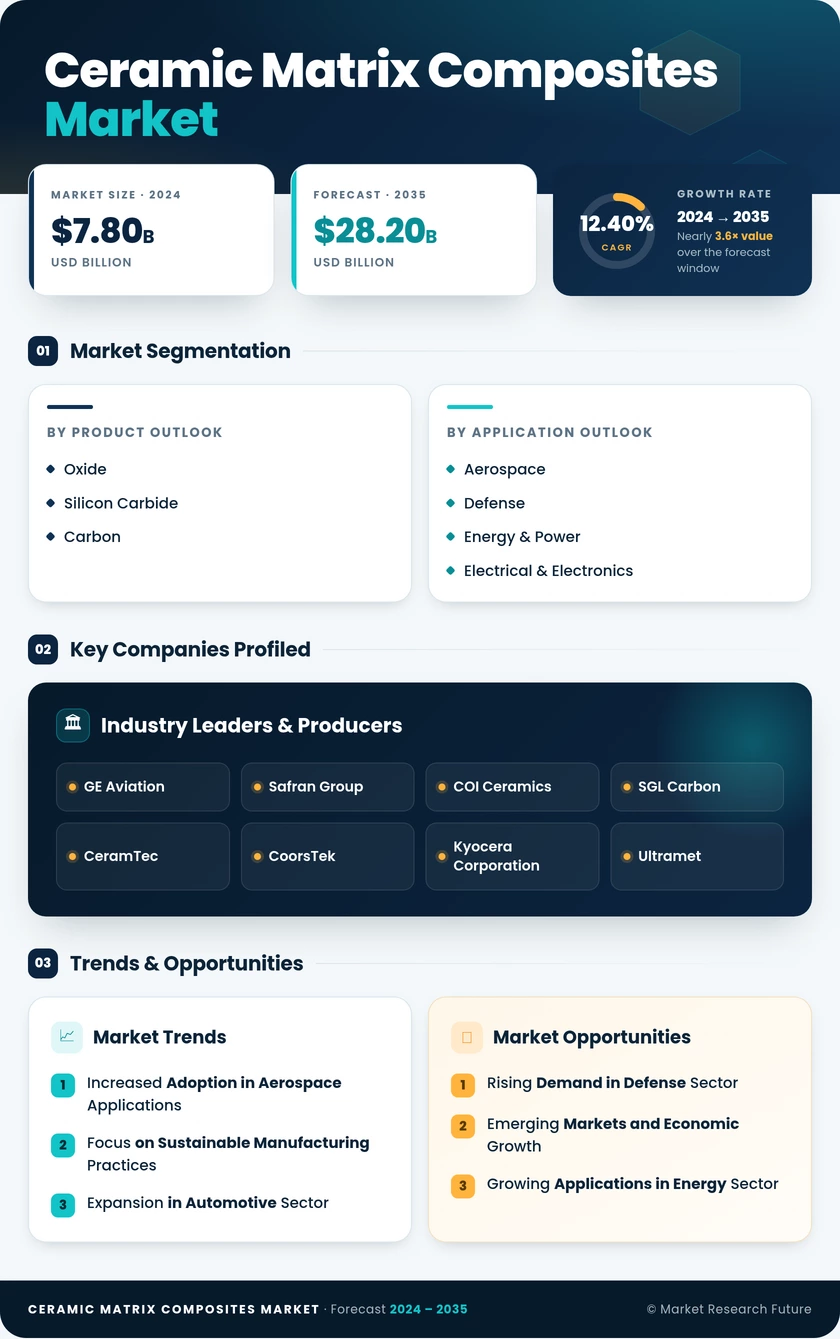
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
|---|---|---|---|
| By Product Type | C/C, C/SiC, Oxide/Oxide, SiC/SiC, Other Product Types | SiC/SiC (51.0% share) | Oxide/Oxide (9.9% CAGR) |
| By End-user Industry | Automotive, Aerospace, Defense, Energy and Power, Electrical and Electronics, Other End-user Industries | Aerospace (41.5% share) | Defense (9.4% CAGR) |
| By Region | Asia-Pacific, North America, Europe, South America, Middle East and Africa | North America (38.5% share (2025)) | Asia-Pacific (9.6% CAGR (2026–2035)) |
Market Segmentation Overview
By Product Type
| Sub-Segment | Key Trend |
|---|---|
| C/C | Stable demand in rocket nozzles and aircraft brakes |
| C/SiC | Rising use in hypersonic leading edges and performance brakes |
| Oxide/Oxide | Fastest adoption in exhaust mixers and heat exchangers |
| SiC/SiC | Expanding content in engine shrouds, liners, and nozzles |
| Other Product Types | Research-stage ultra-high-temperature systems |
SiC/SiC leads this dimension with a 51.0% share because it is the only product family qualified at scale for commercial engine hot sections, where fiber strength and creep resistance matter most. Oxide/Oxide grows fastest at a 9.9% CAGR, since its inherent oxidation stability removes the need for barrier coatings in exhausts and heat exchangers. C/C and C/SiC hold defined niches in nozzles and brakes, where controlled oxidation environments suit carbon-based fibers.
By End-user Industry
| Sub-Segment | Key Trend |
|---|---|
| Automotive | Carbon-ceramic brakes; early EV thermal barriers |
| Aerospace | Higher CMC content per commercial engine |
| Defense | Hypersonic programs moving to low-rate production |
| Energy and Power | Gas turbine retrofits for cycling and hydrogen |
| Electrical and Electronics | Oxide grades in hotter power modules |
| Other End-user Industries | Nuclear cladding and furnace fixtures |
Aerospace dominates with a 41.5% share, driven by CMC shrouds and nozzles already flying in thousands of commercial engines. Defense grows fastest at a 9.4% CAGR because hypersonic vehicles face temperatures no metal can survive, and programs are shifting from prototypes to recurring production. Energy and Power and Automotive follow at a smaller scale, tied to gas turbine retrofits and performance brake discs, respectively.


 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA