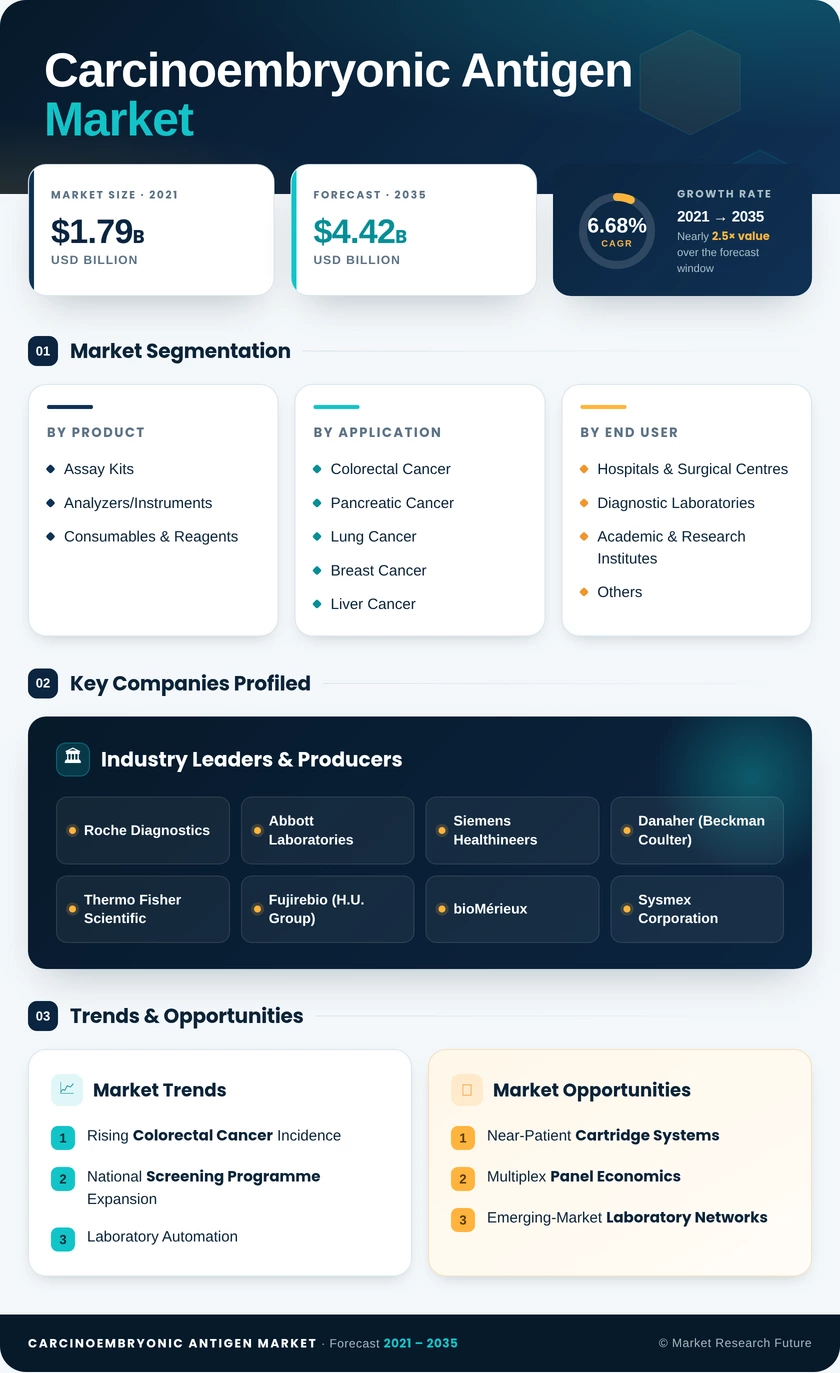
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| By Product | Assay Kits; Analyzers/Instruments; Consumables & Reagents | Assay Kits | Consumables & Reagents |
| By Application | Colorectal Cancer; Pancreatic Cancer; Lung Cancer; Breast Cancer; Liver Cancer; Others | Colorectal Cancer | Liver Cancer |
| By End User | Hospitals & Surgical Centres; Diagnostic Laboratories; Academic & Research Institutes; Others | Hospitals & Surgical Centres | Diagnostic Laboratories |
| By Geography | North America; Europe; Asia-Pacific; South America; Middle East & Africa | North America | Asia-Pacific |
Market Segmentation Overview
By Product
| Sub-Segment | Key Trend |
| Assay Kits | Recurring consumption tied to installed analyzer fleets sustains the largest revenue pool |
| Analyzers/Instruments | Aggressive hardware pricing used to secure long-dated reagent commitments |
| Consumables & Reagents | Third-party competition intensifies as core patents lapse in open-channel markets |
Product economics in this category behave more like a razor-and-blade model than a capital equipment business. Vendors increasingly disclose reagent pull-through per placement as the metric investors watch, because instrument unit counts alone no longer explain revenue trajectories.
By Application
| Sub-Segment | Key Trend |
| Colorectal Cancer | Guideline-mandated serial surveillance across a five-year post-resection window |
| Pancreatic Cancer | Routine inclusion in multiplex gastrointestinal panels alongside CA 19-9 |
| Lung Cancer | Adenocarcinoma monitoring where histology supports marker expression |
| Breast Cancer | Metastatic disease tracking rather than primary diagnosis |
| Liver Cancer | Ageing hepatitis B cohorts in Asia drive the steepest volume growth |
| Others | Gastric, ovarian and thyroid monitoring in specialist referral settings |
Application demand is defined by monitoring rather than detection. Regulatory bodies consistently decline to endorse standalone screening use, so growth follows diagnosed-patient prevalence and treatment-pathway adherence more closely than it follows population health spending.
By End User
| Sub-Segment | Key Trend |
| Hospitals & Surgical Centres | In-house testing tied to resection and immediate post-operative follow-up |
| Diagnostic Laboratories | Outreach consolidation from hospitals below the 60-test-per-day economic threshold |
| Academic & Research Institutes | Clinical trial endpoint measurement and assay validation work |
| Others | Physician office laboratories and specialty oncology clinics |
Buyer behaviour differs sharply by channel. Hospitals negotiate menu-wide agreements where tumour markers are one line among hundreds, while independent laboratories evaluate cost per reportable result with far greater granularity and switch platforms more readily when standardisation permits.

 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA