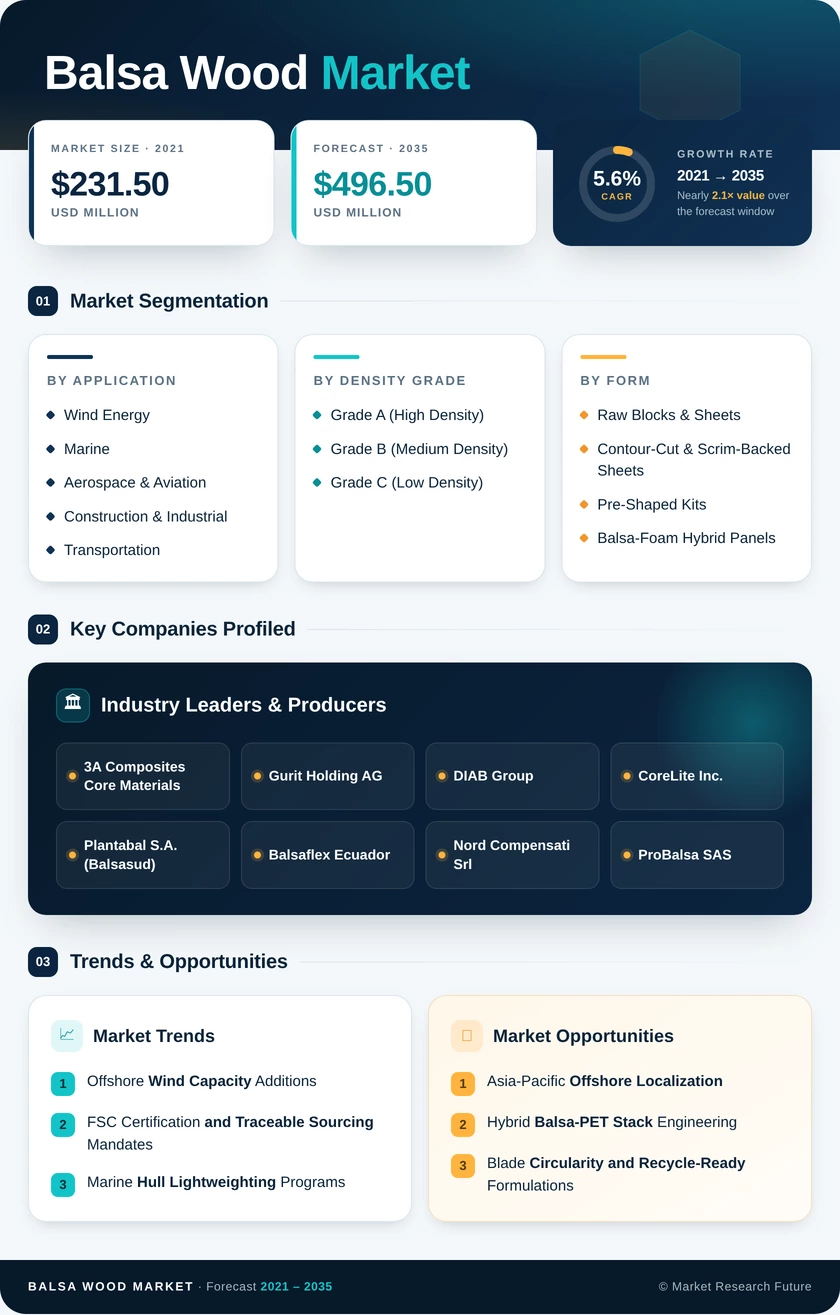
Balsa Wood Market (2026 - 2035)

ID: MRFR/CnM/3059-CR 106 Pages Anshula Mandaokar Last Updated: September 15, 2026
Balsa Wood Market Research Report Information By Application (Wind Energy, Marine, Aerospace & Aviation, Construction & Industrial, Transportation, and Others), By Density Grade (Grade A (high density), Grade B (medium density), and Grade C (low density)), By Form (Raw Blocks & Sheets, Contour-Cut & Scrim-Backed Sheets, Pre-Shaped Kits, and Balsa-Foam Hybrid Panels), and By Distribution Channel (Direct to OEM, Composite Distributors, and Online & Specialty Retail) – Forecast Till 2035
Balsa Wood Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)5.6%
2025 Market SizeUSD 288.0 Million
2035 Market SizeUSD 496.5 Million
Key Players
3A Composites Core Materials
Gurit Holding AG
DIAB Group
CoreLite Inc.
Plantabal S.A.
Balsaflex Ecuador
Opportunities
  • Asia-Pacific Offshore Localization
  • Hybrid Balsa-PET Stack Engineering
  • Blade Circularity and Recycle-Ready Formulations
  1. 1 Market Summary | |
    1. 1.1 Study Assumptions & Market Definition | |
    2. 1.2 Scope of the Study | |
    3. 1.3 Research Methodology | |
  2. 2 Key Report Takeaways | |
    1. 2.1 By Application | |
    2. 2.2 By Product Configuration | |
    3. 2.3 By Geography | |
  3. 3 Market Size & Forecast (2021–2035) | |
    1. 3.1 Historical Market Size (2021–2025) | |
    2. 3.2 Current & Forecast Market Size (2026–2035) | |
    3. 3.3 Market Size by Revenue (USD Million) | |
    4. 3.4 Year-over-Year Growth Analysis | |
  4. 4 Driver Impact Analysis | |
    1. 4.1 Offshore Wind Capacity Additions | |
    2. 4.2 FSC Certification and Traceable Sourcing Mandates | |
    3. 4.3 Marine Hull Lightweighting Programs | |
    4. 4.4 eVTOL and Advanced Air Mobility Prototyping | |
    5. 4.5 Ecuadorian Plantation Yield Improvement | |
    6. 4.6 Lifecycle Carbon Disclosure Regulation | |
    7. 4.7 Automated Kitting Reducing Blade Labor Hours | |
  5. 5 Restraints Impact Analysis | |
    1. 5.1 Single-Country Supply Concentration | |
    2. 5.2 PET and PVC Foam Substitution | |
    3. 5.3 Plantation Rotation Lag | |
    4. 5.4 Density Variability and Inspection Cost | |
    5. 5.5 Freight and Phytosanitary Compliance Burden | |
  6. 6 Opportunities | |
    1. 6.1 Asia-Pacific Offshore Localization | |
    2. 6.2 Hybrid Balsa-PET Stack Engineering | |
    3. 6.3 Blade Circularity and Recycle-Ready Formulations | |
    4. 6.4 Digital Traceability as a Revenue Line | |
    5. 6.5 African and Southeast Asian Plantation Development | |
    6. 6.6 Industry Value Chain Analysis | |
    7. 6.7 Porter's Five Forces Analysis | |
  7. 7 Regional Market Share & Country-Level Analysis | |
    1. 7.1 North America | | |
      1. 7.1.1 US | | |
      2. 7.1.2 Canada | | |
      3. 7.1.3 Mexico | |
    2. 7.2 Europe | | |
      1. 7.2.1 Germany | | |
      2. 7.2.2 UK | | |
      3. 7.2.3 France | | |
      4. 7.2.4 Italy | | |
      5. 7.2.5 Spain | | |
      6. 7.2.6 Nordic Countries | | |
      7. 7.2.7 Russia | | |
      8. 7.2.8 Rest of Europe | |
    3. 7.3 Asia-Pacific | | |
      1. 7.3.1 China | | |
      2. 7.3.2 India | | |
      3. 7.3.3 Japan | | |
      4. 7.3.4 South Korea | | |
      5. 7.3.5 ASEAN | | |
      6. 7.3.6 Rest of Asia-Pacific | |
    4. 7.4 South America | | |
      1. 7.4.1 Brazil | | |
      2. 7.4.2 Argentina | | |
      3. 7.4.3 Rest of South America | |
    5. 7.5 Middle East & Africa | | |
      1. 7.5.1 Saudi Arabia | | |
      2. 7.5.2 UAE | | |
      3. 7.5.3 South Africa | | |
      4. 7.5.4 Egypt | | |
      5. 7.5.5 Rest of Middle East & Africa | |
  8. 8 Future Outlook (2026–2035) | |
    1. 8.1 Turbine Upscaling and Core Intensity | |
    2. 8.2 Automation and Digital Quality Assurance | |
    3. 8.3 Supply Diversification and Sovereign Risk Pricing | |
    4. 8.4 Sustainability Reporting and End-of-Life Regulation | |
  9. 9 Segmentation Analysis | |
    1. 9.1 By Application | | |
      1. 9.1.1 Wind Energy | | |
      2. 9.1.2 Marine | | |
      3. 9.1.3 Aerospace & Aviation | | |
      4. 9.1.4 Construction & Industrial | | |
      5. 9.1.5 Transportation | | |
      6. 9.1.6 Others | |
    2. 9.2 By Density Grade | | |
      1. 9.2.1 Grade A (High Density) | | |
      2. 9.2.2 Grade B (Medium Density) | | |
      3. 9.2.3 Grade C (Low Density) | |
    3. 9.3 By Form | | |
      1. 9.3.1 Raw Blocks & Sheets | | |
      2. 9.3.2 Contour-Cut & Scrim-Backed Sheets | | |
      3. 9.3.3 Pre-Shaped Kits | | |
      4. 9.3.4 Balsa-Foam Hybrid Panels | |
    4. 9.4 By Distribution Channel | | |
      1. 9.4.1 Direct to OEM | | |
      2. 9.4.2 Composite Distributors | | |
      3. 9.4.3 Online & Specialty Retail | |
  10. 10 Competitive Landscape | |
    1. 10.1 Market Share Analysis (2026) | |
    2. 10.2 Competitive Benchmarking Matrix | |
    3. 10.3 Company Profiles | | |
      1. 10.3.1 3A Composites Core Materials | | |
      2. 10.3.2 Gurit Holding AG | | |
      3. 10.3.3 DIAB Group | | |
      4. 10.3.4 CoreLite Inc. | | |
      5. 10.3.5 Plantabal S.A. (Balsasud) | | |
      6. 10.3.6 Balsaflex Ecuador | | |
      7. 10.3.7 Nord Compensati Srl | | |
      8. 10.3.8 ProBalsa SAS | | |
      9. 10.3.9 Carbon-Core Corporation | | |
      10. 10.3.10 I-Core Composites LLC | | |
      11. 10.3.11 The Gill Corporation | |
  11. 11 Recent News & Developments | |
  12. 12 Report Scope & Methodology | |
    1. 12.1 Study Period & Base Year | |
    2. 12.2 Data Sources & Citations | |
    3. 12.3 Abbreviations | |
  13. 13 Detailed Sources & Citations | |
  14. 14 Frequently Asked Questions | | LIST OF TABLES | |
  15. TABLE 1 Global Balsa Wood Market Size & Forecast, by Revenue (USD Million), 2021–2035 | |
  16. TABLE 2 Global Balsa Wood Market – Year-over-Year Growth Analysis, 2021–2035 | |
  17. TABLE 3 Driver Impact Analysis – Global Balsa Wood Market, 2026–2035 | |
  18. TABLE 4 Restraint Impact Analysis – Global Balsa Wood Market, 2026–2035 | |
  19. TABLE 5 Global Balsa Wood Market Size, by Application, 2021–2035 (USD Million) | |
  20. TABLE 6 Global Balsa Wood Market Size, by Density Grade, 2021–2035 (USD Million) | |
  21. TABLE 7 Global Balsa Wood Market Size, by Form, 2021–2035 (USD Million) | |
  22. TABLE 8 Global Balsa Wood Market Size, by Distribution Channel, 2021–2035 (USD Million) | |
  23. TABLE 9 Global Balsa Wood Market Size, by Region, 2021–2035 (USD Million) | |
  24. TABLE 10 North America Balsa Wood Market Size, by Country, 2021–2035 (USD Million) | |
  25. TABLE 11 Europe Balsa Wood Market Size, by Country, 2021–2035 (USD Million) | |
  26. TABLE 12 Asia-Pacific Balsa Wood Market Size, by Country, 2021–2035 (USD Million) | |
  27. TABLE 13 South America Balsa Wood Market Size, by Country, 2021–2035 (USD Million) | |
  28. TABLE 14 Middle East & Africa Balsa Wood Market Size, by Country, 2021–2035 (USD Million) | |
  29. TABLE 15 North America Balsa Wood Market Size, by Application, 2021–2035 (USD Million) | |
  30. TABLE 16 Europe Balsa Wood Market Size, by Application, 2021–2035 (USD Million) | |
  31. TABLE 17 Asia-Pacific Balsa Wood Market Size, by Application, 2021–2035 (USD Million) | |
  32. TABLE 18 South America Balsa Wood Market Size, by Application, 2021–2035 (USD Million) | |
  33. TABLE 19 Middle East & Africa Balsa Wood Market Size, by Application, 2021–2035 (USD Million) | |
  34. TABLE 20 North America Balsa Wood Market Size, by Form, 2021–2035 (USD Million) | |
  35. TABLE 21 Europe Balsa Wood Market Size, by Form, 2021–2035 (USD Million) | |
  36. TABLE 22 Asia-Pacific Balsa Wood Market Size, by Density Grade, 2021–2035 (USD Million) | |
  37. TABLE 23 Competitive Benchmarking Matrix – Global Balsa Wood Market, 2026 | |
  38. TABLE 24 Company Profiles – Key Players, Global Balsa Wood Market | |
  39. TABLE 25 Recent Developments & Strategic Announcements, 2023–2025 | |
  40. TABLE 26 Report Scope & Methodology Summary | |
  41. TABLE 27 Detailed Sources & Citations Index | | LIST OF FIGURES | |
  42. FIGURE 1 Global Balsa Wood Market – Market Dynamics Overview (Drivers, Restraints, Opportunities) | |
  43. FIGURE 2 Global Balsa Wood Market – Industry Value Chain Analysis | |
  44. FIGURE 3 Global Balsa Wood Market – Porter's Five Forces Analysis | |
  45. FIGURE 4 Global Balsa Wood Market Size Trend, 2021–2035 (USD Million) | |
  46. FIGURE 5 Global Balsa Wood Market – Year-over-Year Growth Curve, 2022–2035 | |
  47. FIGURE 6 Market Share by Application, 2025 vs 2035 (%) | |
  48. FIGURE 7 Market Share by Density Grade, 2025 (%) | |
  49. FIGURE 8 Market Share by Form, 2025 vs 2035 (%) | |
  50. FIGURE 9 Market Share by Distribution Channel, 2025 (%) | |
  51. FIGURE 10 Regional Market Share, 2025 (%) | |
  52. FIGURE 11 Regional CAGR Comparison, 2026–2035 (%) | |
  53. FIGURE 12 Country-Level Revenue Contribution – Top 10 Markets, 2025 | |
  54. FIGURE 13 Competitive Landscape – Estimated Revenue Share Bands, 2026 | |
  55. FIGURE 14 Supply Concentration Map – Global Balsa Production by Origin | |
  56. FIGURE 15 Lifecycle Emissions Benchmark – Core Material Comparison

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
By ApplicationWind Energy; Marine; Aerospace & Aviation; Construction & Industrial; Transportation; OthersWind EnergyAerospace & Aviation
By Density GradeGrade A (High Density); Grade B (Medium Density); Grade C (Low Density)Grade A (High Density)Grade A (High Density)
By FormRaw Blocks & Sheets; Contour-Cut & Scrim-Backed Sheets; Pre-Shaped Kits; Balsa-Foam Hybrid PanelsRaw Blocks & SheetsPre-Shaped Kits
By Distribution ChannelDirect to OEM; Composite Distributors; Online & Specialty RetailDirect to OEMOnline & Specialty Retail
By GeographyNorth America; Europe; Asia-Pacific; South America; Middle East & AfricaAsia-PacificSouth America


Market Segmentation Overview

By Application

Sub-SegmentKey Trend
Wind EnergyOffshore blade upscaling raises premium-grade specification requirements
MarineEmissions rules on propulsion push sandwich construction deeper into mid-size hulls
Aerospace & AviationeVTOL certification programmes create high-margin demand for tolerance-controlled sheet
Construction & IndustrialPrice-sensitive segment switches readily to foam during supply disruption.
TransportationRail interior fire-smoke-toxicity standards favor treated core assemblies.
OthersHobby, sports, and educational demand provides stable low-volume baseline.


Application mix is broadening even as wind retains roughly half of revenue. The practical consequence for suppliers is portfolio design: a single grade portfolio can no longer serve blade roots, yacht decks, and aircraft floors simultaneously, and specialization by application is becoming a viable competitive strategy for mid-tier producers.

By Density Grade

Sub-SegmentKey Trend
Grade A (High Density)Structural load cases drive tightening tolerance bands and inline density scanning.
Grade B (Medium Density)Workhorse specification for marine and industrial sandwich panels
Grade C (Low Density)Narrow qualification windows in aviation support outsized per-unit pricing


Grade sorting has become a source of margin rather than a cost of doing business. Producers investing in computed-tomography scanning can guarantee statistical density bands, which is precisely the assurance that foam competitors have used to displace natural cores in automated infusion environments.

By Form

Sub-SegmentKey Trend
Raw Blocks & SheetsShare erodes as OEMs outsource cutting and kitting to suppliers
Contour-Cut & Scrim-Backed SheetsStandard for curved shell surfaces requiring drapability
Pre-Shaped KitsLabor and offcut savings drive the fastest growth of any form factor.
Balsa-Foam Hybrid PanelsEngineered assemblies defend share against pure-foam substitution.


Value is migrating steadily downstream. Every step from log to finished kit adds conversion margin, and the suppliers capturing that migration are those with CNC finishing capacity positioned close to customer plants rather than close to plantations.

By Distribution Channel

Sub-SegmentKey Trend
Direct to OEMMulti-year agreements with indexed pricing and consignment inventory
Composite DistributorsServes refit yards and small fabricators with irregular order patterns
Online & Specialty RetailHobby and education demand grows from a small revenue base.


Direct supply will keep gaining share as qualification burdens rise and traceability documentation becomes contractual. Distributors retain a defensible role in repair and prototyping, where speed and small lot sizes matter more than certified provenance or price per cubic metre.

By Geography

Sub-SegmentKey Trend
North AmericaMarine and aerospace demand outweighs wind; import exposure to tariff review.
EuropeRegulatory leadership on deforestation and circularity sets global specification norms.
Asia-PacificBlade manufacturing concentration sustains the largest regional demand pool.
South AmericaUpstream producers move into kit conversion, capturing downstream margin.
Middle East & AfricaEarly-stage wind programmes and nascent plantation trials


Regional dynamics increasingly diverge. Europe writes the rules, Asia-Pacific consumes the volume, and South America controls the resource — a three-way structure that leaves buyers navigating regulatory, logistical, and biological constraints simultaneously.




Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.