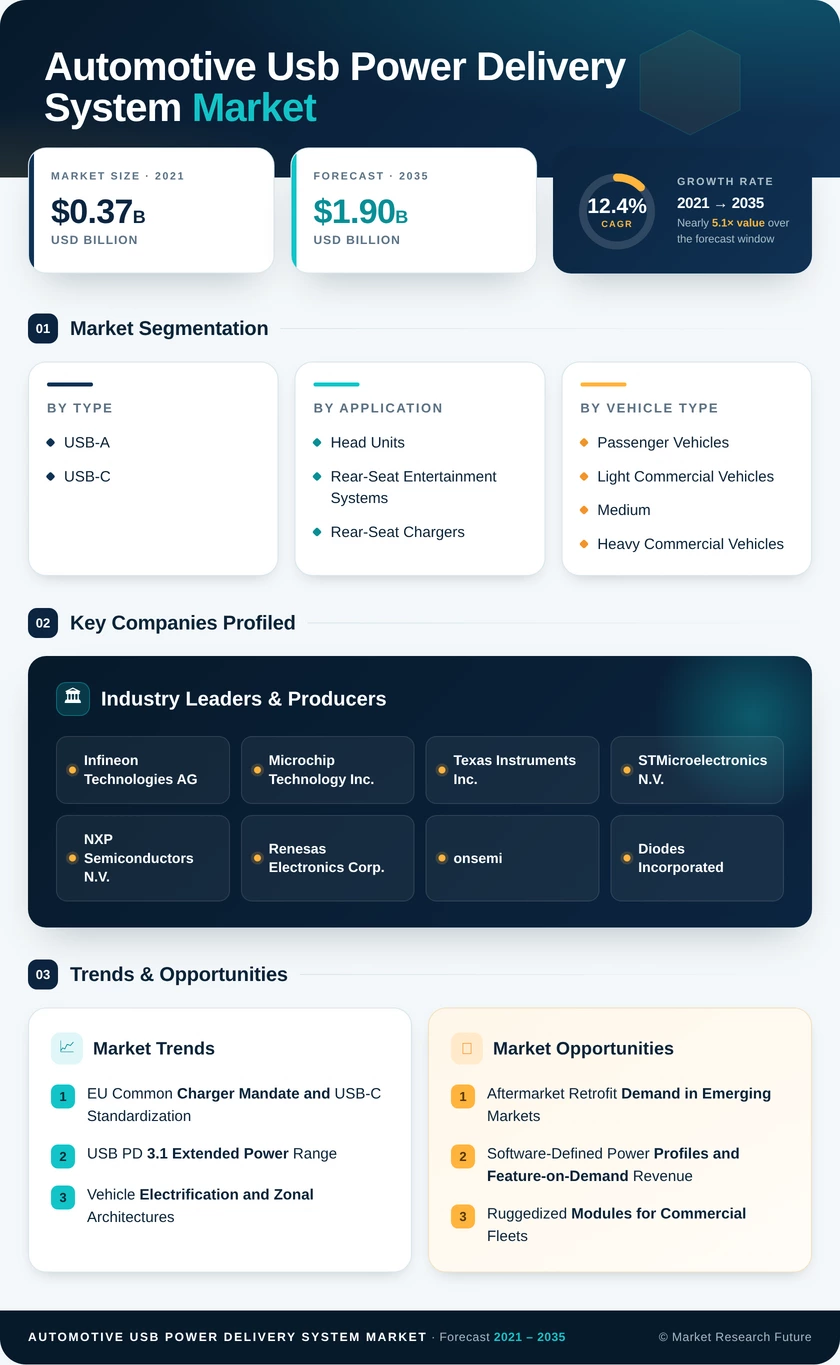
Automotive USB Power Delivery System Market (2026 - 2035)

ID: MRFR/AT/6175-CR 110 Pages Shubham Munde Last Updated: September 24, 2026
Automotive USB Power Delivery System Market Research Report By Type (USB-A, USB-C), By Application (Head Units, Rear-Seat Entertainment Systems, Rear-Seat Chargers), By Vehicle Type (Passenger Vehicles, Light Commercial Vehicles, Medium and Heavy Commercial Vehicles), By Distribution Channel (OEM, Aftermarket) - Forecast to 2035
Automotive USB Power Delivery System Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)12.4%
2025 Market SizeUSD 0.59 Billion
2035 Market SizeUSD 1.90 Billion
Key Players
Infineon Technologies AG
Microchip Technology Inc.
Texas Instruments Inc.
STMicroelectronics N.V.
NXP Semiconductors N.V.
Renesas Electronics Corp.
Opportunities
  • Aftermarket Retrofit Demand in Emerging Markets
  • Software-Defined Power Profiles and Feature-on-Demand Revenue
  • Ruggedized Modules for Commercial Fleets
  1. 1 Market Summary | |
  2. 2 Key Report Takeaways | |
    1. 2.1 By Type | |
    2. 2.2 By Application | |
    3. 2.3 By Vehicle Type | |
    4. 2.4 By Distribution Channel | |
    5. 2.5 By Region | |
  3. 3 Market Size and Forecast (2021–2035) | |
  4. 4 Driver Impact Analysis | |
    1. 4.1 EU Common Charger Mandate and USB-C Standardization | |
    2. 4.2 USB PD
    3. 3.1 Extended Power Range | |
    4. 4.3 Vehicle Electrification and Zonal Architectures | |
    5. 4.4 Multi-Row Cabin and Rear-Seat Feature Expansion | |
    6. 4.5 Commercial Fleet Digitization | |
    7. 4.6 Asia-Pacific Production Scale and Localization Incentives | |
    8. 4.7 Semiconductor Integration and Capacity Investment | |
  5. 5 Restraints Impact Analysis | |
    1. 5.1 Thermal and EMC Constraints at High Wattage | |
    2. 5.2 Automotive-Grade Qualification and Supply Lead Times | |
    3. 5.3 Price Erosion in Entry-Level Vehicles | |
    4. 5.4 Substitution by Wireless Charging and Projection | |
    5. 5.5 Functional Safety and Cybersecurity Compliance Burden | |
  6. 6 Opportunities | |
    1. 6.1 Aftermarket Retrofit Demand in Emerging Markets | |
    2. 6.2 Software-Defined Power Profiles and Feature-on-Demand Revenue | |
    3. 6.3 Ruggedized Modules for Commercial Fleets | |
    4. 6.4 Seat-Integrated Power Modules for Multi-Row EVs | |
    5. 6.5 High-Power Ports Aligned with Laptop Charging Rules | |
  7. 7 Regional Market Share and Country-Level Analysis | |
    1. 7.1 North America | | |
      1. 7.1.1 US | | |
      2. 7.1.2 Canada | | |
      3. 7.1.3 Mexico | |
    2. 7.2 Europe | | |
      1. 7.2.1 Germany | | |
      2. 7.2.2 UK | | |
      3. 7.2.3 France | | |
      4. 7.2.4 Italy | | |
      5. 7.2.5 Spain | | |
      6. 7.2.6 Nordic Countries | | |
      7. 7.2.7 Russia | | |
      8. 7.2.8 Rest of Europe | |
    3. 7.3 Asia-Pacific | | |
      1. 7.3.1 China | | |
      2. 7.3.2 India | | |
      3. 7.3.3 Japan | | |
      4. 7.3.4 South Korea | | |
      5. 7.3.5 ASEAN | | |
      6. 7.3.6 Rest of Asia-Pacific | |
    4. 7.4 South America | | |
      1. 7.4.1 Brazil | | |
      2. 7.4.2 Argentina | | |
      3. 7.4.3 Rest of South America | |
    5. 7.5 Middle East & Africa | | |
      1. 7.5.1 Saudi Arabia | | |
      2. 7.5.2 UAE | | |
      3. 7.5.3 South Africa | | |
      4. 7.5.4 Egypt | | |
      5. 7.5.5 Rest of MEA | |
  8. 8 Future Outlook (2026–2035) | |
    1. 8.1 Software-Defined Vehicles Reshape Cabin Power | |
    2. 8.2 The Electrification Supercycle | |
    3. 8.3 Silicon Integration and Wide-Bandgap Power Stages | |
    4. 8.4 Sustainability and Circular Design | |
  9. 9 Segmentation Analysis | |
    1. 9.1 By Type | | |
      1. 9.1.1 USB-A | | |
      2. 9.1.2 USB-C | |
    2. 9.2 By Application | | |
      1. 9.2.1 Head Units | | |
      2. 9.2.2 Rear-Seat Entertainment Systems | | |
      3. 9.2.3 Rear-Seat Chargers | |
    3. 9.3 By Vehicle Type | | |
      1. 9.3.1 Passenger Vehicles | | |
      2. 9.3.2 Light Commercial Vehicles | | |
      3. 9.3.3 Medium and Heavy Commercial Vehicles | |
    4. 9.4 By Distribution Channel | | |
      1. 9.4.1 OEM | | |
      2. 9.4.2 Aftermarket | |
  10. 10 Competitive Landscape | |
    1. 10.1 Market Concentration Analysis | |
    2. 10.2 Competitive Benchmarking Matrix | |
  11. 11 Recent News & Developments | |
  12. 12 Report Scope and Methodology | |
  13. 13 Detailed Sources and Citations | |
  14. 14 Frequently Asked Questions (FAQs) | | LIST OF TABLES | | LIST OF FIGURES

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
By TypeUSB-A, USB-CUSB-C (67.8% share)USB-C (67.8% share)
By ApplicationHead Units, Rear-Seat Entertainment Systems, Rear-Seat ChargersHead Units (46.2% share)Rear-Seat Chargers (16.7% CAGR)
By Vehicle TypePassenger Vehicles, Light Commercial Vehicles, Medium and Heavy Commercial VehiclesPassenger Vehicles (69.1% share)Medium and Heavy Commercial Vehicles (14.9% CAGR)
By Distribution ChannelOEM, AftermarketOEM (79.3% share)Aftermarket (16.1% CAGR)
By RegionNorth America, Europe, Asia-Pacific, South America, Middle East & AfricaEurope (36.0% share)Asia-Pacific (14.6% CAGR)


Market Segmentation Overview

By Type

Sub-SegmentKey Trend
USB-ARetained as optional port in entry trims; shifting to aftermarket replacement.
USB-CDefault connector on new platforms with support for up to 240 W


USB-C leads have a 67.8% share and are also the fastest-growing type, because regulation and consumer devices have converged on a single connector. USB-A persists only in legacy platforms and low-cost trims, where it serves older phones. As automakers finalize phase-out plans, USB-A revenue will increasingly come from aftermarket replacement rather than new vehicle programs.

By Application

Sub-SegmentKey Trend
Head UnitsDual high-current ports for phone projection and charging
Rear-Seat Entertainment SystemsUSB-C used for both screen power and media input
Rear-Seat ChargersSeatback and third-row ports rising in multi-row SUVs


Head Units lead with a 46.2% share because every vehicle needs a primary port near the driver for navigation and phone projection. Rear-Seat Chargers grow fastest at 16.7% as three-row SUVs and premium sedans distribute 45–100 W outlets to every seating position. Rear-Seat Entertainment Systems sit between the two, tied closely to premium and family vehicle trims.

By Vehicle Type

Sub-SegmentKey Trend
Passenger VehiclesFeature migration of multi-port USB-C to mass-market trims
Light Commercial VehiclesDelivery van electrification and handheld device use
Medium and Heavy Commercial VehiclesRuggedized ports for logging devices and telematics


Passenger Vehicles dominate with a 69.1% share, driven by production volume and consumer expectations for device charging in every row. Medium and Heavy Commercial Vehicles grow fastest at 14.9% because electronic logging rules and fleet telematics require reliable, surge-protected cab power. Light Commercial Vehicles benefit from delivery fleets equipping vans with scanners and navigation tablets.

By Distribution Channel

Sub-SegmentKey Trend
OEMFactory integration with wireless pads and validated EMC performance
AftermarketClip-in 65–100 W USB-C modules for older vehicles


OEM channels lead with a 79.3% share because factory-fitted ports pass electromagnetic compatibility testing and carry vehicle warranty coverage. The Aftermarket grows fastest at 16.1% as owners of older and budget vehicles retrofit USB-C modules to match their current phones and laptops. Certified cable bundles and simple installation are helping retail channels address buyer safety concerns.




Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.