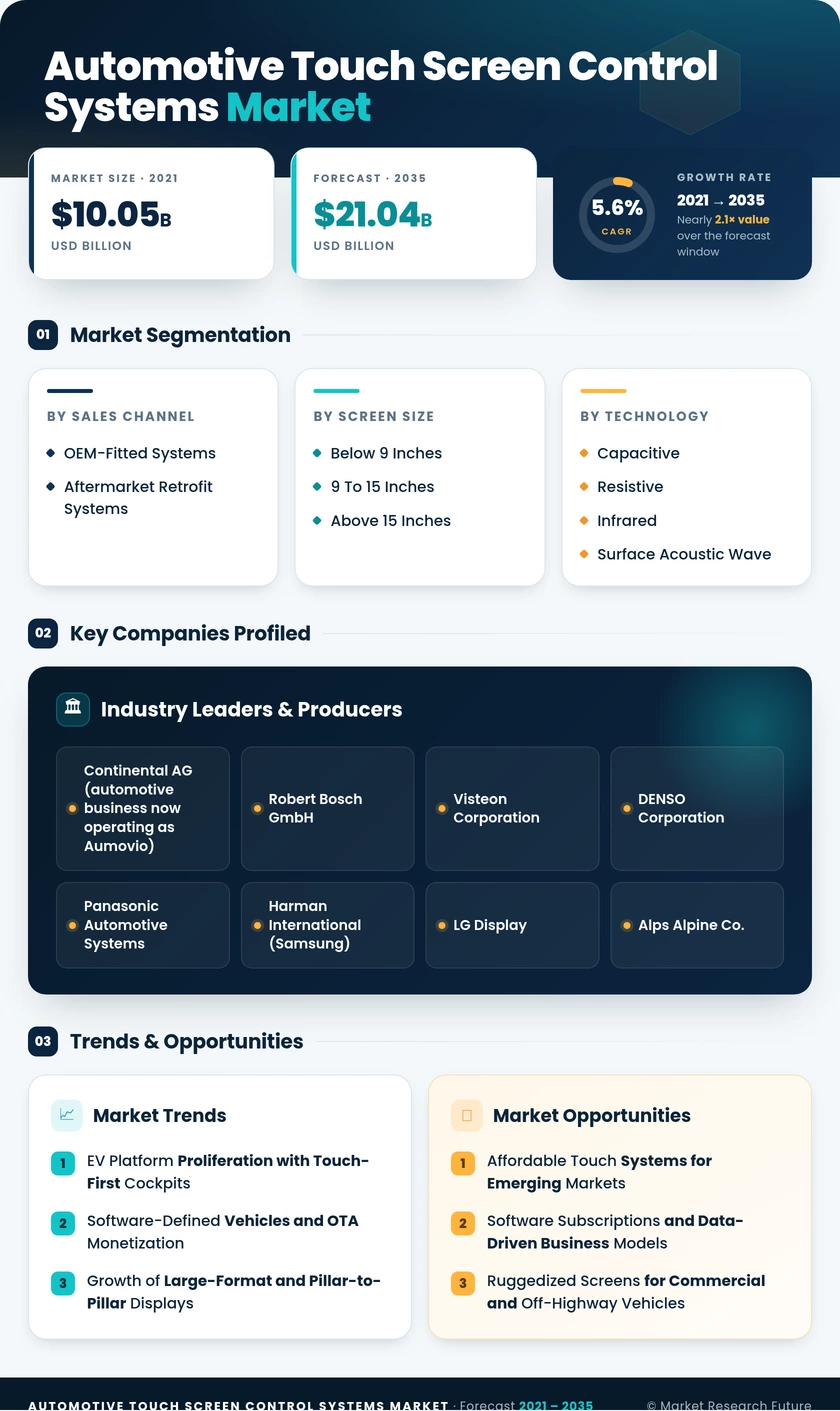
Automotive Touch Screen Control Systems Market (2026 - 2035)

ID: MRFR/AT/10205-HCR 128 Pages Shubham Munde Last Updated: September 24, 2026
Automotive Touch Screen Control Systems Market Research Report By Sales Channel (OEM-Fitted Systems, Aftermarket Retrofit Systems), By Screen Size (Below 9 Inches, 9 To 15 Inches, Above 15 Inches), By Technology (Capacitive, Resistive, Infrared, Surface Acoustic Wave), By Application (Passenger Cars, Light Commercial Vehicles, Medium and Heavy Commercial Vehicles) - Forecast to 2035
Automotive Touch Screen Control Systems Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)5.6%
2025 Market SizeUSD 12.20 Billion
2035 Market SizeUSD 21.04 Billion
Key Players
Continental AG
Robert Bosch GmbH
Visteon Corporation
DENSO Corporation
Panasonic Automotive Systems
Harman International
Opportunities
  • Affordable Touch Systems for Emerging Markets
  • Software Subscriptions and Data-Driven Business Models
  • Ruggedized Screens for Commercial and Off-Highway Vehicles
  1. 1 Market Summary | |
  2. 2 Key Report Takeaways | |
    1. 2.1 By Sales Channel | |
    2. 2.2 By Screen Size | |
    3. 2.3 By Technology | |
    4. 2.4 By Application | |
    5. 2.5 By Region | |
  3. 3 Market Size and Forecast (2021–2035) | |
  4. 4 Driver Impact Analysis | |
    1. 4.1 EV Platform Proliferation with Touch-First Cockpits | |
    2. 4.2 Software-Defined Vehicles and OTA Monetization | |
    3. 4.3 Growth of Large-Format and Pillar-to-Pillar Displays | |
    4. 4.4 Safety Regulations Requiring In-Cabin Visual Interfaces | |
    5. 4.5 Commercial Fleet Digitization and Electronic Logging | |
    6. 4.6 Localized Automotive Electronics Supply Chains | |
    7. 4.7 Rising Global Vehicle Output and Panel Scale Economies | |
  5. 5 Restraints Impact Analysis | |
    1. 5.1 Driver Distraction Concerns and Safety-Rating Pressure | |
    2. 5.2 Semiconductor and Display Supply Volatility | |
    3. 5.3 Tariffs on Imported Automotive Parts | |
    4. 5.4 Cybersecurity Compliance Costs | |
    5. 5.5 Harsh-Environment Durability Requirements | |
  6. 6 Opportunities | |
    1. 6.1 Affordable Touch Systems for Emerging Markets | |
    2. 6.2 Software Subscriptions and Data-Driven Business Models | |
    3. 6.3 Ruggedized Screens for Commercial and Off-Highway Vehicles | |
    4. 6.4 Haptic Hybrid Control Surfaces | |
    5. 6.5 Retrofit Demand from Smartphone Mirroring Shifts | |
  7. 7 Regional Market Share and Country-Level Analysis | |
    1. 7.1 North America | | |
      1. 7.1.1 US | | |
      2. 7.1.2 Canada | | |
      3. 7.1.3 Mexico | |
    2. 7.2 Europe | | |
      1. 7.2.1 Germany | | |
      2. 7.2.2 UK | | |
      3. 7.2.3 France | | |
      4. 7.2.4 Italy | | |
      5. 7.2.5 Spain | | |
      6. 7.2.6 Nordic Countries | | |
      7. 7.2.7 Russia | | |
      8. 7.2.8 Rest of Europe | |
    3. 7.3 Asia-Pacific | | |
      1. 7.3.1 China | | |
      2. 7.3.2 India | | |
      3. 7.3.3 Japan | | |
      4. 7.3.4 South Korea | | |
      5. 7.3.5 ASEAN | | |
      6. 7.3.6 Rest of Asia-Pacific | |
    4. 7.4 South America | | |
      1. 7.4.1 Brazil | | |
      2. 7.4.2 Argentina | | |
      3. 7.4.3 Rest of South America | |
    5. 7.5 Middle East & Africa | | |
      1. 7.5.1 Saudi Arabia | | |
      2. 7.5.2 UAE | | |
      3. 7.5.3 South Africa | | |
      4. 7.5.4 Egypt | | |
      5. 7.5.5 Rest of MEA | |
  8. 8 Future Outlook (2026–2035) | |
    1. 8.1 AI Assistants and Multimodal Control | |
    2. 8.2 Centralized Cockpit Platforms | |
    3. 8.3 Electrification Supercycle | |
    4. 8.4 Circularity and Sustainability Requirements | |
  9. 9 Segmentation Analysis | |
    1. 9.1 By Sales Channel | | |
      1. 9.1.1 OEM-Fitted Systems | | |
      2. 9.1.2 Aftermarket Retrofit Systems | |
    2. 9.2 By Screen Size | | |
      1. 9.2.1 Below 9 Inches | | |
      2. 9.2.2 9 To 15 Inches | | |
      3. 9.2.3 Above 15 Inches | |
    3. 9.3 By Technology | | |
      1. 9.3.1 Capacitive | | |
      2. 9.3.2 Resistive | | |
      3. 9.3.3 Infrared | | |
      4. 9.3.4 Surface Acoustic Wave | |
    4. 9.4 By Application | | |
      1. 9.4.1 Passenger Cars | | |
      2. 9.4.2 Light Commercial Vehicles | | |
      3. 9.4.3 Medium and Heavy Commercial Vehicles | |
  10. 10 Competitive Landscape | |
    1. 10.1 Market Concentration Analysis | |
    2. 10.2 Competitive Benchmarking | |
  11. 11 Recent News & Developments | |
  12. 12 Report Scope and Methodology | |
  13. 13 Detailed Sources and Citations | |
  14. 14 Frequently Asked Questions (FAQs) | | LIST OF TABLES | |
  15. TABLE 1 Report Summary — Key Market Parameters, 2025–2035 | |
  16. TABLE 2 Global Market Size & Forecast, by Revenue (USD Billion), 2021–2035 | |
  17. TABLE 3 Driver Impact Analysis, 2026–2035 | |
  18. TABLE 4 Restraints Impact Analysis, 2026–2035 | |
  19. TABLE 5 Regional Summary, 2025 | |
  20. TABLE 6 North America — Country-Level Analysis, 2025 | |
  21. TABLE 7 Europe — Country-Level Analysis, 2025 | |
  22. TABLE 8 Asia-Pacific — Country-Level Analysis, 2025 | |
  23. TABLE 9 South America — Country-Level Analysis, 2025 | |
  24. TABLE 10 Middle East & Africa — Country-Level Analysis, 2025 | |
  25. TABLE 11 Market Segmentation, by Sales Channel, 2025 | |
  26. TABLE 12 Market Segmentation, by Screen Size, 2025 | |
  27. TABLE 13 Market Segmentation, by Technology, 2025 | |
  28. TABLE 14 Market Segmentation, by Application, 2025 | |
  29. TABLE 15 Competitive Benchmarking Matrix, 2025 | |
  30. TABLE 16 Report Scope and Methodology | |
  31. TABLE 17 Detailed Sources and Citations | |
  32. TABLE 18 Segmentation Quick Reference | |
  33. TABLE 19 Sales Channel — Sub-Segment Key Trends | |
  34. TABLE 20 Screen Size — Sub-Segment Key Trends | |
  35. TABLE 21 Technology — Sub-Segment Key Trends | |
  36. TABLE 22 Application — Sub-Segment Key Trends | | LIST OF FIGURES | |
  37. FIGURE 1 Market Dynamics Overview — Drivers, Restraints, and Opportunities | |
  38. FIGURE 2 Industry Value Chain Analysis | |
  39. FIGURE 3 Porter's Five Forces Analysis | |
  40. FIGURE 4 Global Market Size Trend (USD Billion), 2021–2035 | |
  41. FIGURE 5 Market Share by Sales Channel, 2025 | |
  42. FIGURE 6 Market Share by Screen Size, 2025 | |
  43. FIGURE 7 Market Share by Technology, 2025 | |
  44. FIGURE 8 Market Share by Application, 2025 | |
  45. FIGURE 9 Regional Market Share, 2025 | |
  46. FIGURE 10 Country-Level Revenue Distribution by Region, 2025 | |
  47. FIGURE 11 Competitive Landscape — Estimated Revenue Share Ranges, 2025 | |
  48. FIGURE 12 Market Concentration and Positioning Matrix

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
By Sales ChannelOEM-Fitted Systems; Aftermarket Retrofit SystemsOEM-Fitted Systems — 76.0% (share)Aftermarket Retrofit Systems — 7.6% (CAGR)
By Screen SizeBelow 9 Inches; 9 To 15 Inches; Above 15 Inches9 To 15 Inches — 58.2% (share)Above 15 Inches — 9.6% (CAGR)
By TechnologyCapacitive; Resistive; Infrared; Surface Acoustic WaveCapacitive — 75.4% (share)Surface Acoustic Wave — 8.2% (CAGR)
By ApplicationPassenger Cars; Light Commercial Vehicles; Medium and Heavy Commercial VehiclesPassenger Cars — 68.5% (share)Light Commercial Vehicles — 6.5% (CAGR)
By RegionNorth America; Europe; Asia-Pacific; South America; Middle East & AfricaAsia-Pacific — 46.0% (share)Asia-Pacific — 46.0% (share)


Market Segmentation Overview

By Sales Channel

Sub-SegmentKey Trend
OEM-Fitted SystemsGateway-level integration enabling OTA feature sales and warranty-backed reliability
Aftermarket Retrofit SystemsWireless mirroring and camera kits for legacy vehicles as some OEMs drop CarPlay support.


OEM-Fitted Systems lead with a 76.0% share because factory units sit behind the vehicle's secure gateway, pass crash validation, and carry OEM warranty terms that retrofit products cannot match. Aftermarket Retrofit Systems grow fastest at a 7.6% CAGR as owners of older vehicles seek smartphone mirroring and parking cameras. Retrofit gains remain capped by restricted data-bus access.

By Screen Size

Sub-SegmentKey Trend
Below 9 InchesRetained in cost-sensitive fleets and basic commercial cabins
9 To 15 InchesStandard fit across mass-market dashboards and base-trim upgrades
Above 15 InchesPillar-to-pillar and curved OLED surfaces entering near-luxury crossovers


The 9 To 15 Inches range holds 58.2% share because it fits existing dashboard hardpoints while giving enough area for navigation and media. Above 15 Inches displays grow fastest at a 9.6% CAGR as falling cost per square inch brings panoramic panels into crossovers. Below 9 Inches units persist where glove use and budget constraints dominate.

By Technology

Sub-SegmentKey Trend
CapacitiveIn-cell and force-sensing designs reduce weight and add haptics
ResistiveConfined to low-cost and extreme-temperature dashboards
InfraredNiche use in specialty large-format and bezel-free designs
Surface Acoustic WaveTouch detection through thick protective glass for gloved operators


Capacitive leads with a 75.4% share on the strength of multi-finger gestures and a mature supply chain, with in-cell stacks trimming bezels and weight. Surface Acoustic Wave grows fastest at an 8.2% CAGR because it reads touches through protective glass in trucks and farm machinery where capacitive sensing struggles. Resistive and Infrared attract limited new investment.

By Application

Sub-SegmentKey Trend
Passenger CarsTouch control of EV energy, comfort, and personalization features
Light Commercial VehiclesDisplays linked to route planning and driver scorecards
Medium and Heavy Commercial VehiclesGradual uptake driven by e-logging and remote diagnostics


Passenger Cars hold a 68.5% share as OEMs replace switch clusters with contextual touch menus, particularly on EVs. Light Commercial Vehicles grow fastest at a 6.5% CAGR, since last-mile operators value screens tied to fleet analytics and electrified van platforms. Medium and Heavy Commercial Vehicles adopt more slowly, weighing cost and durability against electronic logging requirements.




Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.