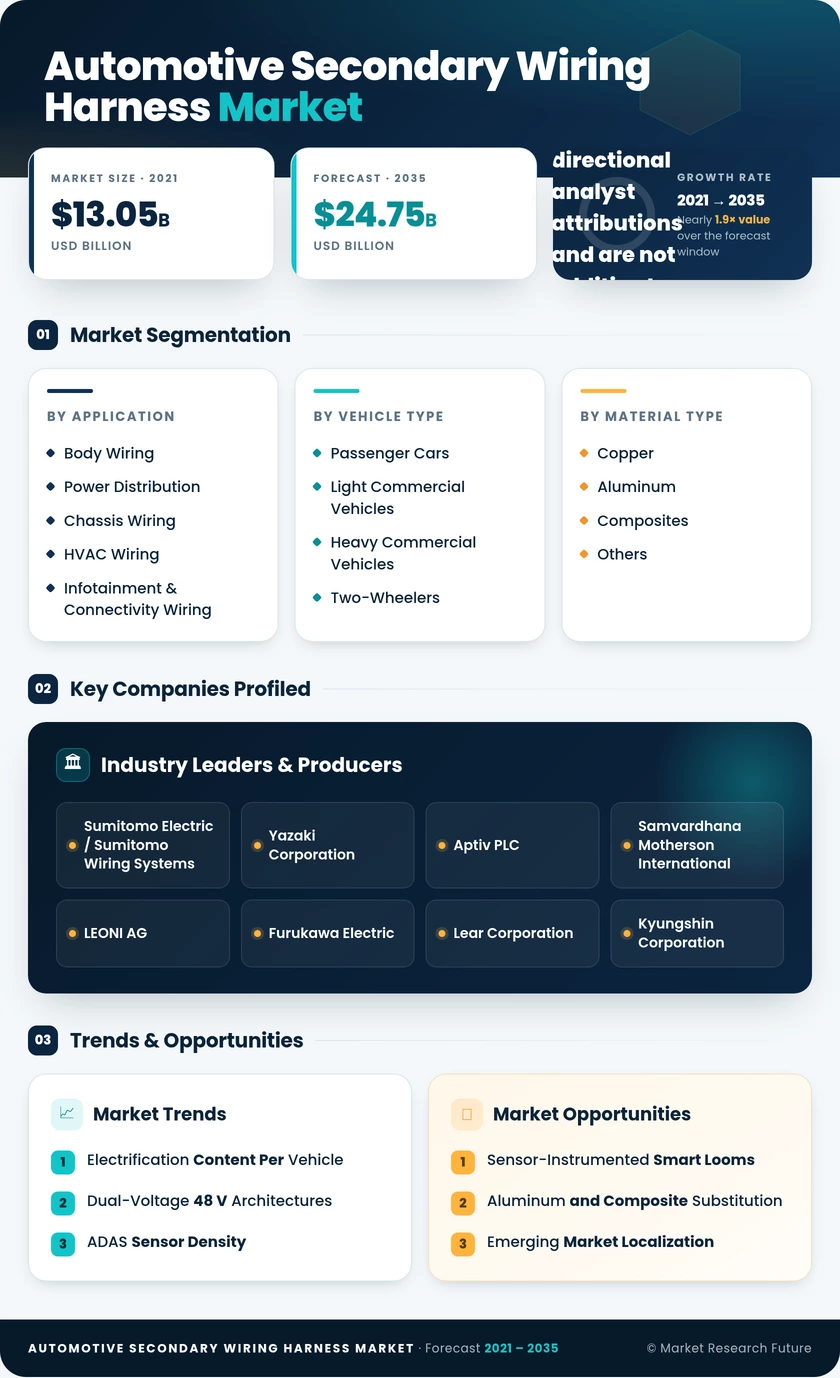
Automotive Secondary Wiring Harness Market (2026 - 2035)

ID: MRFR/AT/4633-HCR 100 Pages Triveni Bhoyar Last Updated: August 27, 2026
Automotive Secondary Wiring Harness Market Research Report By Application (Body Wiring, Power Distribution, Chassis Wiring, HVAC Wiring, Infotainment & Connectivity Wiring, Others), By Vehicle Type (Passenger Cars, Light Commercial Vehicles, Heavy Commercial Vehicles, Two-Wheelers), By Material Type (Copper, Aluminum, Composites, Others), By Connector Type (Sealed Connectors, Unsealed Connectors, Multi-Connector Systems, Others), By Technology (Conventional Wiring, Smart Wiring Systems), By End User (OEMs, Aftermarket Suppliers) and By Regional (North America, Europe, South America, Asia Pacific, Middle East and Africa) - Forecast to 2035
Automotive Secondary Wiring Harness Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)4.40%
2025 Market SizeUSD 16.08 Billion
2035 Market SizeUSD 24.75 Billion
Key Players
Sumitomo Electric / Sumitomo Wiring Systems
Yazaki Corporation
Aptiv PLC
Samvardhana Motherson International
LEONI AG
Furukawa Electric
Opportunities
  • Sensor-Instrumented Smart Looms
  • Aluminum and Composite Substitution
  • Emerging Market Localization
  1. 1 Market Summary |
    1. 1.1 Study Assumptions & Market Definition |
    2. 1.2 Scope of the Study |
    3. 1.3 Research Methodology
  2. 2 Key Report Takeaways |
    1. 2.1 By Technology |
    2. 2.2 By Sector |
    3. 2.3 By Region
  3. 3 Market Size & Forecast (2021–2035) |
    1. 3.1 Historical Market Size (2021–2025) |
    2. 3.2 Current & Forecast Market Size (2026–2035) |
    3. 3.3 Year-over-Year Growth Analysis
  4. 4 Driver Impact Analysis |
    1. 4.1 Electrification Content Per Vehicle |
    2. 4.2 Dual-Voltage 48 V Architectures |
    3. 4.3 ADAS Sensor Density |
    4. 4.4 Asia-Pacific Volume Expansion
  5. 5 Restraints Impact Analysis |
    1. 5.1 Copper Price Volatility |
    2. 5.2 Zonal Architecture Consolidation |
    3. 5.3 Assembly Labor Economics
  6. 6 Opportunities |
    1. 6.1 Sensor-Instrumented Smart Looms |
    2. 6.2 Aluminum and Composite Substitution |
    3. 6.3 Emerging Market Localization |
    4. 6.4 Predictive Maintenance Data Services |
    5. 6.5 Aftermarket Retrofit Channels
  7. 7 Regional Market Share & Country-Level Analysis |
    1. 7.1 North America | |
      1. 7.1.1 US | |
      2. 7.1.2 Canada | |
      3. 7.1.3 Mexico |
    2. 7.2 Europe | |
      1. 7.2.1 Germany | |
      2. 7.2.2 UK | |
      3. 7.2.3 France | |
      4. 7.2.4 Italy | |
      5. 7.2.5 Spain | |
      6. 7.2.6 Nordic Countries | |
      7. 7.2.7 Russia | |
      8. 7.2.8 Rest of Europe |
    3. 7.3 Asia-Pacific | |
      1. 7.3.1 China | |
      2. 7.3.2 India | |
      3. 7.3.3 Japan | |
      4. 7.3.4 South Korea | |
      5. 7.3.5 ASEAN | |
      6. 7.3.6 Rest of Asia-Pacific |
    4. 7.4 South America | |
      1. 7.4.1 Brazil | |
      2. 7.4.2 Argentina | |
      3. 7.4.3 Rest of South America |
    5. 7.5 Middle East & Africa | |
      1. 7.5.1 Saudi Arabia | |
      2. 7.5.2 UAE | |
      3. 7.5.3 South Africa | |
      4. 7.5.4 Egypt | |
      5. 7.5.5 Rest of Middle East & Africa
  8. 8 Future Outlook (2026–2035) |
    1. 8.1 Software-Defined Vehicles & Zonal Convergence |
    2. 8.2 The Electrification Supercycle |
    3. 8.3 Circularity & Material Accountability |
    4. 8.4 Manufacturing Automation
  9. 9 Market Segmentation Analysis |
    1. 9.1 By Application | |
      1. 9.1.1 Body Wiring | |
      2. 9.1.2 Power Distribution | |
      3. 9.1.3 Chassis Wiring | |
      4. 9.1.4 HVAC Wiring | |
      5. 9.1.5 Infotainment & Connectivity Wiring | |
      6. 9.1.6 Others |
    2. 9.2 By Vehicle Type | |
      1. 9.2.1 Passenger Cars | |
      2. 9.2.2 Light Commercial Vehicles | |
      3. 9.2.3 Heavy Commercial Vehicles | |
      4. 9.2.4 Two-Wheelers |
    3. 9.3 By Material Type | |
      1. 9.3.1 Copper | |
      2. 9.3.2 Aluminum | |
      3. 9.3.3 Composites | |
      4. 9.3.4 Others |
    4. 9.4 By Connector Type | |
      1. 9.4.1 Sealed Connectors | |
      2. 9.4.2 Unsealed Connectors | |
      3. 9.4.3 Multi-Connector Systems | |
      4. 9.4.4 Others |
    5. 9.5 By Technology | |
      1. 9.5.1 Conventional Wiring | |
      2. 9.5.2 Smart Wiring Systems |
    6. 9.6 By End User | |
      1. 9.6.1 OEMs | |
      2. 9.6.2 Aftermarket Suppliers
  10. 10 Competitive Landscape |
    1. 10.1 Market Concentration Analysis |
    2. 10.2 Competitive Benchmarking Matrix |
    3. 10.3 Company Profiles | |
      1. 10.3.1 Sumitomo Electric / Sumitomo Wiring Systems | |
      2. 10.3.2 Yazaki Corporation | |
      3. 10.3.3 Aptiv PLC | |
      4. 10.3.4 Samvardhana Motherson International | |
      5. 10.3.5 LEONI AG | |
      6. 10.3.6 Furukawa Electric | |
      7. 10.3.7 Lear Corporation | |
      8. 10.3.8 Kyungshin Corporation | |
      9. 10.3.9 Fujikura Ltd. | |
      10. 10.3.10 Kromberg & Schubert | |
      11. 10.3.11 Coroplast Group
  11. 11 Recent News & Developments
  12. 12 Report Scope & Methodology |
    1. 12.1 Study Period & Base Year |
    2. 12.2 Data Sources & Citations |
    3. 12.3 Abbreviations
  13. 13 Detailed Sources & Citations
  14. 14 Frequently Asked Questions
  15. 15 LIST OF TABLES |
  16. TABLE 1 Global Automotive Secondary Wiring Harness Market Size & Forecast (USD Billion), 2021–2035 |
  17. TABLE 2 Year-over-Year Growth Analysis, 2021–2035 |
  18. TABLE 3 Driver Impact Analysis Matrix, 2026–2035 |
  19. TABLE 4 Restraint Impact Analysis Matrix, 2026–2035 |
  20. TABLE 5 Regional Market Share Summary, 2025 |
  21. TABLE 6 North America Market Size, by Country, 2021–2035 (USD Billion) |
  22. TABLE 7 Europe Market Size, by Country, 2021–2035 (USD Billion) |
  23. TABLE 8 Asia-Pacific Market Size, by Country, 2021–2035 (USD Billion) |
  24. TABLE 9 South America Market Size, by Country, 2021–2035 (USD Billion) |
  25. TABLE 10 Middle East & Africa Market Size, by Country, 2021–2035 (USD Billion) |
  26. TABLE 11 Market Size, by Application, 2021–2035 (USD Billion) |
  27. TABLE 12 Market Size, by Vehicle Type, 2021–2035 (USD Billion) |
  28. TABLE 13 Market Size, by Material Type, 2021–2035 (USD Billion) |
  29. TABLE 14 Market Size, by Connector Type, 2021–2035 (USD Billion) |
  30. TABLE 15 Market Size, by Technology, 2021–2035 (USD Billion) |
  31. TABLE 16 Market Size, by End User, 2021–2035 (USD Billion) |
  32. TABLE 17 Competitive Benchmarking Matrix, 2026 |
  33. TABLE 18 Company Profiles — Key Players |
  34. TABLE 19 Recent Developments & Strategic Announcements, 2023–2025 |
  35. TABLE 20 Report Scope & Methodology Summary |
  36. TABLE 21 Detailed Sources & Citations Index
  37. 16 LIST OF FIGURES |
  38. FIGURE 1 Market Dynamics — Drivers, Restraints, Opportunities |
  39. FIGURE 2 Industry Value Chain Analysis |
  40. FIGURE 3 Porter's Five Forces Analysis |
  41. FIGURE 4 Global Market Size Trend, 2021–2035 (USD Billion) |
  42. FIGURE 5 Year-over-Year Growth Curve, 2022–2035 |
  43. FIGURE 6 Application Segment Share, 2025 vs 2035 |
  44. FIGURE 7 Vehicle Type Segment Share, 2025 |
  45. FIGURE 8 Material Type Segment Share, 2025 |
  46. FIGURE 9 Connector Type Segment Share, 2025 |
  47. FIGURE 10 Technology Segment Growth Comparison, 2026–2035 |
  48. FIGURE 11 End User Channel Split, 2025 |
  49. FIGURE 12 Regional Market Share Distribution, 2025 |
  50. FIGURE 13 Asia-Pacific Country Growth Comparison, 2026–2035 |
  51. FIGURE 14 Competitive Landscape Positioning Map, 2026 |
  52. FIGURE 15 Top-5 Supplier Revenue Share Concentration, 2026

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
By ApplicationBody Wiring, Power Distribution, Chassis Wiring, HVAC Wiring, Infotainment & Connectivity Wiring, OthersBody WiringPower Distribution
By Vehicle TypePassenger Cars, Light Commercial Vehicles, Heavy Commercial Vehicles, Two-WheelersPassenger CarsHeavy Commercial Vehicles
By Material TypeCopper, Aluminum, Composites, OthersCopperComposites
By Connector TypeSealed Connectors, Unsealed Connectors, Multi-Connector Systems, OthersSealed ConnectorsMulti-Connector Systems
By TechnologyConventional Wiring, Smart Wiring SystemsConventional WiringSmart Wiring Systems
By End UserOEMs, Aftermarket SuppliersOEMsAftermarket Suppliers


Market Segmentation Overview

By Application

Sub-SegmentKey Trend
Body WiringCircuit count rises with seat, mirror, and ambient lighting content
Power DistributionConductor upsizing driven by 48 V rails and higher accessory loads
Chassis WiringSensor and actuator proliferation lengthens signal drops
HVAC WiringEV thermal management adds pack and cabin loop circuits
Infotainment & Connectivity WiringDisplay count and antenna diversity expand shielded runs
OthersLighting modules migrate to LED with dedicated drivers


Application demand concentrates where interior features live. Body circuits carry the widest trim-level variation, which makes them the hardest to standardize and the most valuable to platform-engineer well.

By Vehicle Type

Sub-SegmentKey Trend
Passenger CarsFeature democratization pushes premium content into entry trims
Light Commercial VehiclesLast-mile electrification adds telematics and cargo-area circuits
Heavy Commercial VehiclesSafety mandates lift historically lean electrical architectures
Two-WheelersAsian electrification introduces harnesses to a low-content segment


Commercial platforms represent the underappreciated growth pocket. Regulatory content mandates arrive there later than in passenger cars but land on a much lower content baseline.

By Material Type

Sub-SegmentKey Trend
CopperRetains dominance on validated crimp reliability
AluminumAdopted selectively for low-current door, roof, and floor circuits
CompositesUsed for specialty shielding and weight-critical routing
OthersClad and coated conductors bridge cost and reliability gaps


Material substitution moves slowly because qualification cost, not raw material price, governs the decision. Programs that plan substitution at platform launch capture savings; mid-cycle switches rarely pay back.

By Connector Type

Sub-SegmentKey Trend
Sealed ConnectorsRequired for door, floor, and underbody ingress protection
Unsealed ConnectorsCost-optimized for dry cabin interior zones
Multi-Connector SystemsConsolidation points expand under zonal architectures
OthersHigh-voltage interlocked interfaces grow with EV mix


Connector strategy increasingly determines assembly cost. Fewer, denser interfaces reduce labor time but raise the consequence of any single interface failure.

By Technology

Sub-SegmentKey Trend
Conventional WiringContinues serving existing platforms through end of cycle
Smart Wiring SystemsIntegrated diagnostics and solid-state load management scale up


Smart systems win nomination where warranty exposure is highest. Fault localization at the loom level shortens dealer diagnostic time, which is a measurable cost saving OEMs can underwrite.

By End User

Sub-SegmentKey Trend
OEMsBuild-to-sequence supply tied to platform nomination cycles
Aftermarket SuppliersRetrofit, repair, and accessory fitment sustain independent demand


OEM channels dominate value but carry the tighter margins. Aftermarket volume grows with parc age and repairability rules that favor serviceable connector designs over moulded assemblies.




Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.