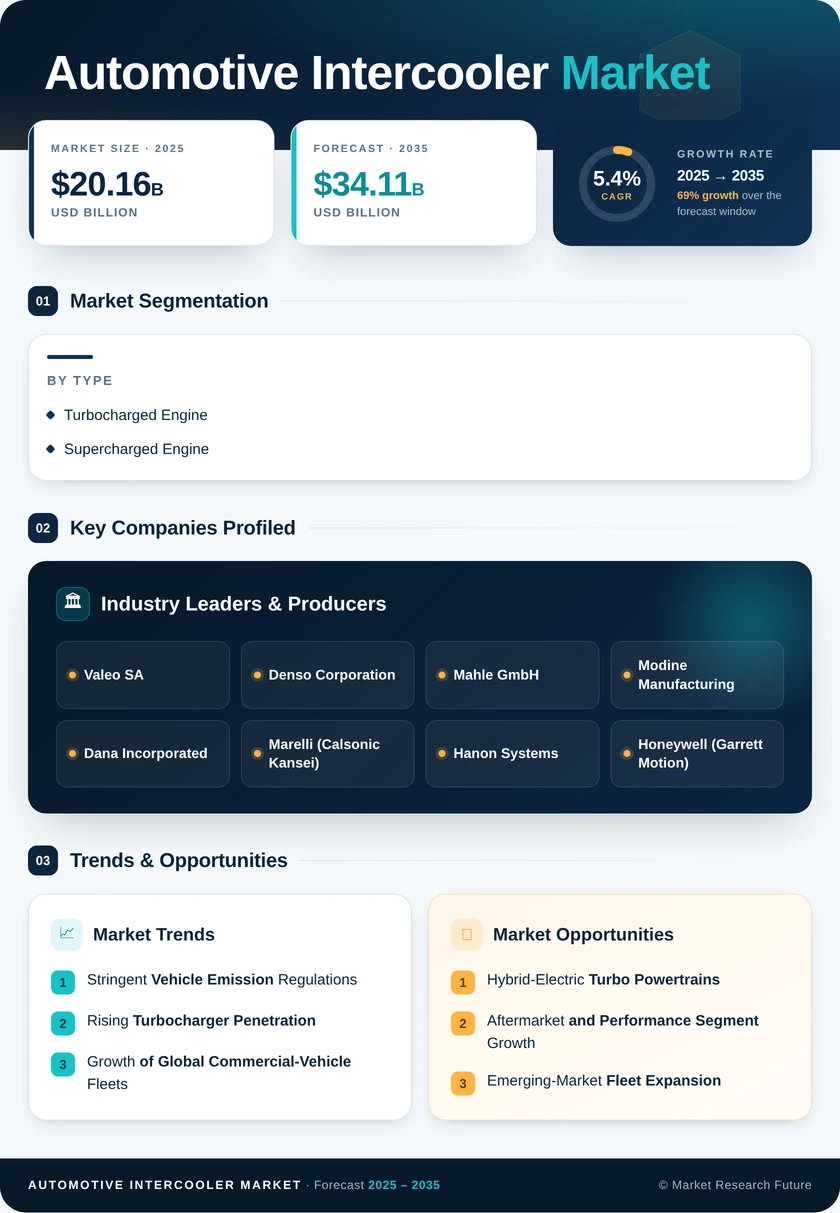
Automotive Intercooler Market (2026 - 2035)

ID: MRFR/AT/1562-HCR 110 Pages Shubham Munde Last Updated: September 15, 2026
Automotive Intercooler Market Research Report By Type (Air to Air Intercooler, Air to Water Intercooler), By Vehicle Type (Passenger Cars, Commercial Vehicles), By Engine Type (Turbocharged Engine, Supercharged Engine) and By Regional (North America, Europe, South America, Asia Pacific, Middle East and Africa) - Forecast to 2035
Automotive Intercooler Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)5.4%
2025 Market SizeUSD 20.16 Billion
2035 Market SizeUSD 34.11 Billion
Key Players
Valeo SA
Denso Corporation
Mahle GmbH
Modine Manufacturing
Dana Incorporated
Marelli
Opportunities
  • Hybrid-Electric Turbo Powertrains
  • Aftermarket and Performance Segment Growth
  • Emerging-Market Fleet Expansion
  1. 1 Market Overview |
    1. 1.1 Study Assumptions & Market Definition |
    2. 1.2 Scope of the Study |
    3. 1.3 Research Methodology
  2. 2 Market Summary & Key Takeaways
  3. 3 Market Dynamics |
    1. 3.1 Market Drivers Analysis | |
      1. 3.1.1 Stringent Vehicle Emission Regulations | |
      2. 3.1.2 Rising Turbocharger Penetration in Passenger Cars | |
      3. 3.1.3 Growth of Global Commercial-Vehicle Fleets | |
      4. 3.1.4 Downsized Engine Programs by OEMs | |
      5. 3.1.5 Lightweight Material Adoption (Aluminum, Composites) | |
      6. 3.1.6 Expansion of Aftermarket Performance Upgrades | |
      7. 3.1.7 Hybrid-Electric Turbo Powertrain Integration |
    2. 3.2 Market Restraints Analysis | |
      1. 3.2.1 Growing EV Adoption Reducing ICE Fleet | |
      2. 3.2.2 Raw-Material Price Volatility (Aluminum, Copper) | |
      3. 3.2.3 Thermal Management Integration Reducing Standalone Demand | |
      4. 3.2.4 Supply-Chain Disruptions and Logistics Costs | |
      5. 3.2.5 Decline of Supercharger Applications |
    3. 3.3 Market Opportunity Analysis | |
      1. 3.3.1 Hybrid-Electric Turbo Powertrains | |
      2. 3.3.2 Aftermarket and Performance Segment Growth | |
      3. 3.3.3 Emerging-Market Fleet Expansion | |
      4. 3.3.4 Advanced Materials and Additive Manufacturing | |
      5. 3.3.5 Data-Driven Predictive Maintenance |
    4. 3.4 Industry Value Chain Analysis |
    5. 3.5 Porter's Five Forces Analysis
  4. 4 Global Automotive Intercooler Market Size & Forecast (2021–2035) |
    1. 4.1 Historical Market Size (2021–2025) |
    2. 4.2 Current & Forecast Market Size (2026–2035) |
    3. 4.3 Market Size by Revenue (USD Billion) |
    4. 4.4 Year-over-Year Growth Analysis
  5. 5 Segmentation Analysis |
    1. 5.1 By Type | |
      1. 5.1.1 Air to Air Intercooler | |
      2. 5.1.2 Air to Water Intercooler |
    2. 5.2 By Vehicle Type | |
      1. 5.2.1 Passenger Cars | |
      2. 5.2.2 Commercial Vehicles |
    3. 5.3 By Engine Type | |
      1. 5.3.1 Turbocharged Engine | |
      2. 5.3.2 Supercharged Engine
  6. 6 Regional Analysis |
    1. 6.1 North America | |
      1. 6.1.1 United States | |
      2. 6.1.2 Canada | |
      3. 6.1.3 Mexico |
    2. 6.2 Europe | |
      1. 6.2.1 Germany | |
      2. 6.2.2 United Kingdom | |
      3. 6.2.3 France | |
      4. 6.2.4 Italy | |
      5. 6.2.5 Spain | |
      6. 6.2.6 Nordic Countries | |
      7. 6.2.7 Russia | |
      8. 6.2.8 Rest of Europe |
    3. 6.3 Asia-Pacific | |
      1. 6.3.1 China | |
      2. 6.3.2 India | |
      3. 6.3.3 Japan | |
      4. 6.3.4 South Korea | |
      5. 6.3.5 ASEAN | |
      6. 6.3.6 Rest of Asia-Pacific |
    4. 6.4 South America | |
      1. 6.4.1 Brazil | |
      2. 6.4.2 Argentina | |
      3. 6.4.3 Rest of South America |
    5. 6.5 Middle East & Africa | |
      1. 6.5.1 Saudi Arabia | |
      2. 6.5.2 UAE | |
      3. 6.5.3 South Africa | |
      4. 6.5.4 Egypt | |
      5. 6.5.5 Rest of MEA
  7. 7 Competitive Landscape |
    1. 7.1 Market Share Analysis (2025) |
    2. 7.2 Competitive Benchmarking Matrix |
    3. 7.3 Company Profiles | |
      1. 7.3.1 Valeo SA | |
      2. 7.3.2 Denso Corporation | |
      3. 7.3.3 Mahle GmbH | |
      4. 7.3.4 Modine Manufacturing | |
      5. 7.3.5 Dana Incorporated | |
      6. 7.3.6 Marelli (Calsonic Kansei) | |
      7. 7.3.7 Hanon Systems | |
      8. 7.3.8 Honeywell (Garrett Motion) | |
      9. 7.3.9 T.RAD Co., Ltd. | |
      10. 7.3.10 Mishimoto
  8. 8 Future Outlook & Strategic Recommendations (2026–2035) |
    1. 8.1 Hybrid-Turbo Architectures as the Bridge Technology |
    2. 8.2 Smart Thermal Management Integration |
    3. 8.3 Sustainability and Circular-Economy Pressures |
    4. 8.4 Autonomous and Connected Heavy Vehicles
  9. 9 Recent Developments & News
  10. 10 Frequently Asked Questions (FAQs)
  11. 11 Report Scope & Methodology |
    1. 11.1 Study Period & Base Year |
    2. 11.2 Data Sources & Citations |
    3. 11.3 Abbreviations
  12. 1 LIST OF TABLES
  13. 2 LIST OF FIGURES

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
By TypeAir to Air Intercooler; Air to Water IntercoolerAir to Air IntercoolerAir to Water Intercooler
By Vehicle TypePassenger Cars; Commercial VehiclesPassenger CarsPassenger Cars
By Engine TypeTurbocharged Engine; Supercharged EngineTurbocharged EngineTurbocharged Engine
By RegionNorth America; Europe; Asia-Pacific; South America; Middle East & AfricaEuropeAsia-Pacific


Market Segmentation Overview

By Type

Sub-SegmentKey Trend
Air to Air IntercoolerRemains the standard for front-mount applications across passenger and commercial vehicles due to cost and weight advantages
Air to Water IntercoolerGrowing adoption in performance, luxury, and hybrid vehicles where compact packaging and consistent charge-air temperatures are critical


Air to Air intercoolers continue to represent the dominant technology in the global market, driven by simple integration, lower manufacturing cost, and proven reliability across diverse climatic conditions. Air to Water systems are capturing share in higher-value segments where engine layout constraints demand shorter intake paths and tighter thermal control.

By Vehicle Type

Sub-SegmentKey Trend
Passenger CarsNear-universal turbo adoption in new models drives the highest volume of intercooler units
Commercial VehiclesStringent emissions standards for heavy-duty trucks sustain demand for high-capacity, durable intercoolers


Passenger cars generate the largest share of intercooler demand as global powertrain strategies converge on downsized turbocharged engines. Commercial vehicles contribute disproportionate revenue per unit due to larger, more complex intercooler assemblies required for Class 6–8 truck and bus applications.

By Engine Type

Sub-SegmentKey Trend
Turbocharged EngineDominant forced-induction architecture with over 75% of all intercooler-equipped vehicles
Supercharged EngineStable but declining niche limited to select luxury and legacy performance platforms


Turbocharged engine applications dominate intercooler demand globally, benefiting from OEM standardization across gasoline and diesel platforms. Supercharged applications are gradually contracting as OEMs transition legacy V8 and V6 supercharged powertrains to more efficient turbo or electrified alternatives.




Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.