Vehicle Engine Management System Market (2026 - 2035)

ID: MRFR/AT/3329-CR 100 Pages Triveni Bhoyar Last Updated: October 16, 2026
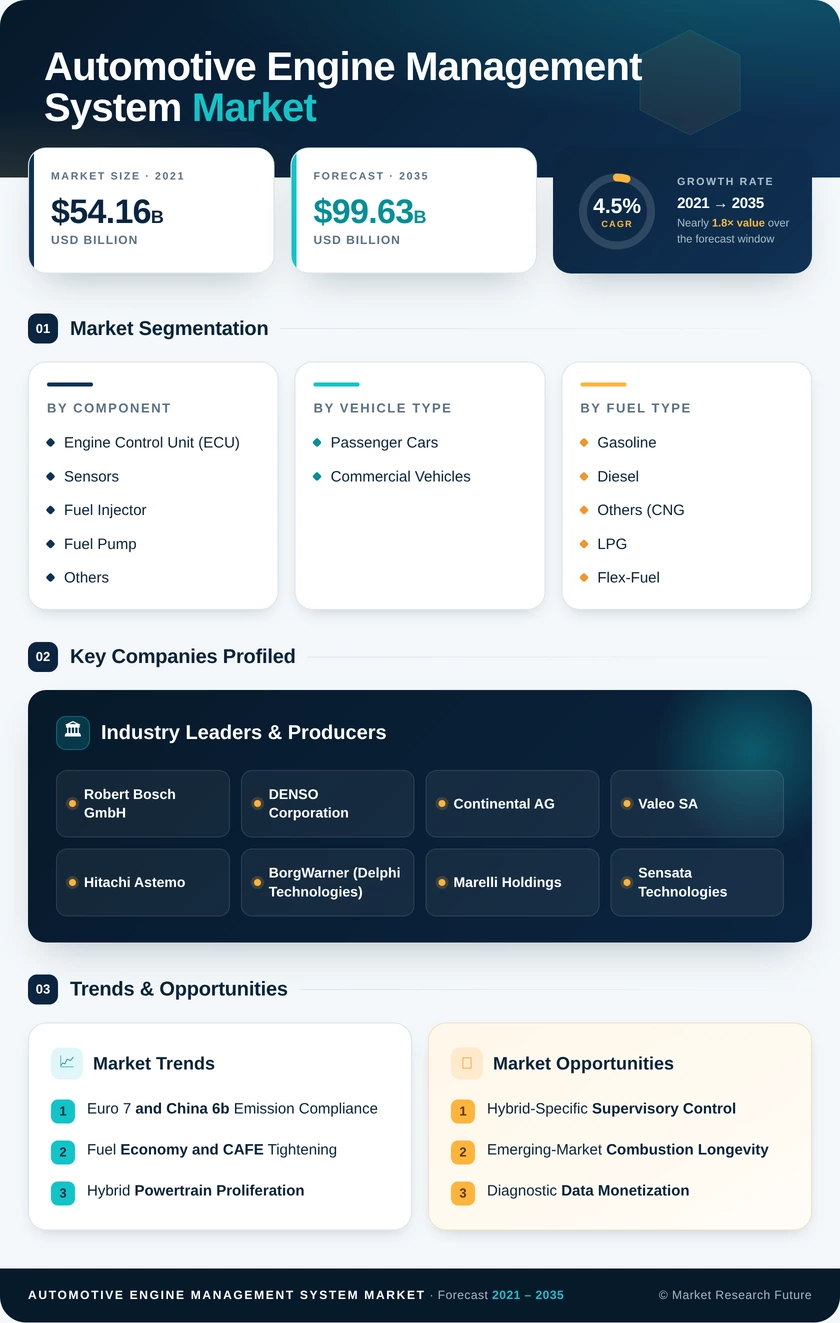
Automotive Engine Management System Market Research Report By Component (Engine Control Unit (ECU), Sensors, Fuel Injector, Fuel Pump, Others), By Vehicle Type (Passenger Cars, Commercial Vehicles), By Fuel Type (Gasoline, Diesel, Others (CNG, LPG, Flex-Fuel, Hydrogen ICE)) - Forecast to 2035
Vehicle Engine Management System Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)4.5%
2025 Market SizeUSD 64.15 Billion
2035 Market SizeUSD 99.63 billion
Key Players
Robert Bosch GmbH
DENSO Corporation
Continental AG
Valeo SA
Hitachi Astemo
BorgWarner
Opportunities
  • Hybrid-Specific Supervisory Control
  • Emerging-Market Combustion Longevity
  • Diagnostic Data Monetization
  1. 1 Market Overview | |
    1. 1.1 Study Assumptions & Market Definition | |
    2. 1.2 Scope of the Study | |
    3. 1.3 Research Methodology | |
  2. 2 Market Summary & Key Takeaways | |
    1. 2.1 Key Findings by Component | |
    2. 2.2 Key Findings by Vehicle Type | |
    3. 2.3 Key Findings by Geography | |
  3. 3 Global Market Size & Forecast (2021–2035) | |
    1. 3.1 Historical Market Size (2021–2025) | |
    2. 3.2 Current & Forecast Market Size (2026–2035) | |
    3. 3.3 Market Size by Revenue (USD Billion) | |
    4. 3.4 Year-over-Year Growth Analysis | |
  4. 4 Market Dynamics — Drivers | |
    1. 4.1 Euro 7 and China 6b Emission Compliance | |
    2. 4.2 Fuel Economy and CAFE Tightening | |
    3. 4.3 Hybrid Powertrain Proliferation | |
    4. 4.4 Rising Sensor Content per Engine | |
    5. 4.5 Heavy-Duty On-Board Diagnostics Mandates | |
    6. 4.6 Software-Defined E/E Architecture Migration | |
    7. 4.7 Asia-Pacific Vehicle Production Growth | |
  5. 5 Market Dynamics — Restraints | |
    1. 5.1 Battery-Electric Displacement of ICE | |
    2. 5.2 Semiconductor Cost and Supply Volatility | |
    3. 5.3 Calibration and Validation Cost Escalation | |
    4. 5.4 Aftermarket Price Erosion and Counterfeits | |
    5. 5.5 Regulatory Fragmentation and Homologation Delay | |
  6. 6 Market Opportunity Analysis | |
    1. 6.1 Hybrid-Specific Supervisory Control | |
    2. 6.2 Emerging-Market Combustion Longevity | |
    3. 6.3 Diagnostic Data Monetization | |
    4. 6.4 Alternative-Fuel Calibration Platforms | |
    5. 6.5 Over-the-Air Powertrain Update Capability | |
    6. 6.6 Industry Value Chain Analysis | |
    7. 6.7 Porter's Five Forces Analysis | |
  7. 7 Regional Analysis | |
    1. 7.1 North America | | |
      1. 7.1.1 US | | |
      2. 7.1.2 Canada | | |
      3. 7.1.3 Mexico | |
    2. 7.2 Europe | | |
      1. 7.2.1 Germany | | |
      2. 7.2.2 UK | | |
      3. 7.2.3 France | | |
      4. 7.2.4 Italy | | |
      5. 7.2.5 Spain | | |
      6. 7.2.6 Nordic Countries | | |
      7. 7.2.7 Russia | | |
      8. 7.2.8 Rest of Europe | |
    3. 7.3 Asia-Pacific | | |
      1. 7.3.1 China | | |
      2. 7.3.2 India | | |
      3. 7.3.3 Japan | | |
      4. 7.3.4 South Korea | | |
      5. 7.3.5 ASEAN | | |
      6. 7.3.6 Rest of Asia-Pacific | |
    4. 7.4 South America | | |
      1. 7.4.1 Brazil | | |
      2. 7.4.2 Argentina | | |
      3. 7.4.3 Rest of South America | |
    5. 7.5 Middle East & Africa | | |
      1. 7.5.1 Saudi Arabia | | |
      2. 7.5.2 UAE | | |
      3. 7.5.3 South Africa | | |
      4. 7.5.4 Egypt | | |
      5. 7.5.5 Rest of Middle East & Africa | |
  8. 8 Future Outlook (2026–2035) | |
    1. 8.1 Machine Learning in Powertrain Calibration | |
    2. 8.2 The Electrification Supercycle and Its Limits | |
    3. 8.3 Platform Economics and Software Licensing | |
    4. 8.4 Lifecycle Emissions Reporting and ESG Disclosure | |
  9. 9 Segmentation Analysis | |
    1. 9.1 By Component | | |
      1. 9.1.1 Engine Control Unit (ECU) | | |
      2. 9.1.2 Sensors | | |
      3. 9.1.3 Fuel Injector | | |
      4. 9.1.4 Fuel Pump | | |
      5. 9.1.5 Others | |
    2. 9.2 By Vehicle Type | | |
      1. 9.2.1 Passenger Cars | | |
      2. 9.2.2 Commercial Vehicles | |
    3. 9.3 By Fuel Type | | |
      1. 9.3.1 Gasoline | | |
      2. 9.3.2 Diesel | | |
      3. 9.3.3 Others (CNG, LPG, Flex-Fuel, Hydrogen ICE) | |
  10. 10 Competitive Landscape | |
    1. 10.1 Market Concentration Analysis (2026) | |
    2. 10.2 Competitive Benchmarking Matrix | |
    3. 10.3 Company Profiles | | |
      1. 10.3.1 Robert Bosch GmbH | | |
      2. 10.3.2 DENSO Corporation | | |
      3. 10.3.3 Continental AG | | |
      4. 10.3.4 Valeo SA | | |
      5. 10.3.5 Hitachi Astemo | | |
      6. 10.3.6 BorgWarner (Delphi Technologies) | | |
      7. 10.3.7 Marelli Holdings | | |
      8. 10.3.8 Sensata Technologies | | |
      9. 10.3.9 Infineon Technologies | | |
      10. 10.3.10 Niterra (NGK Spark Plug) | | |
      11. 10.3.11 Mitsubishi Electric | | |
      12. 10.3.12 TTTech Auto | |
  11. 11 Recent Developments & News | |
  12. 12 Report Scope & Methodology | |
    1. 12.1 Study Period & Base Year | |
    2. 12.2 Data Sources & Citations | |
    3. 12.3 Abbreviations | |
  13. 13 Detailed Sources and Citations | |
  14. 14 Frequently Asked Questions (FAQs) | | LIST OF TABLES | |
  15. TABLE 1 Global Automotive Engine Management System Market Size & Forecast, by Revenue (USD Billion), 2021–2035 | |
  16. TABLE 2 Global Market — Year-over-Year Growth Analysis, 2021–2035 | |
  17. TABLE 3 Driver Impact Analysis Matrix, 2026–2035 | |
  18. TABLE 4 Restraint Impact Analysis Matrix, 2026–2035 | |
  19. TABLE 5 Global Market Size, by Region, 2021–2035 (USD Billion) | |
  20. TABLE 6 North America Market Size, by Country, 2021–2035 (USD Billion) | |
  21. TABLE 7 Europe Market Size, by Country, 2021–2035 (USD Billion) | |
  22. TABLE 8 Asia-Pacific Market Size, by Country, 2021–2035 (USD Billion) | |
  23. TABLE 9 South America Market Size, by Country, 2021–2035 (USD Billion) | |
  24. TABLE 10 Middle East & Africa Market Size, by Country, 2021–2035 (USD Billion) | |
  25. TABLE 11 Global Market Size, by Component, 2021–2035 (USD Billion) | |
  26. TABLE 12 Global Market Size, by Vehicle Type, 2021–2035 (USD Billion) | |
  27. TABLE 13 Global Market Size, by Fuel Type, 2021–2035 (USD Billion) | |
  28. TABLE 14 North America Market Size, by Component, 2021–2035 (USD Billion) | |
  29. TABLE 15 North America Market Size, by Vehicle Type, 2021–2035 (USD Billion) | |
  30. TABLE 16 North America Market Size, by Fuel Type, 2021–2035 (USD Billion) | |
  31. TABLE 17 Europe Market Size, by Component, 2021–2035 (USD Billion) | |
  32. TABLE 18 Europe Market Size, by Vehicle Type, 2021–2035 (USD Billion) | |
  33. TABLE 19 Europe Market Size, by Fuel Type, 2021–2035 (USD Billion) | |
  34. TABLE 20 Asia-Pacific Market Size, by Component, 2021–2035 (USD Billion) | |
  35. TABLE 21 Asia-Pacific Market Size, by Vehicle Type, 2021–2035 (USD Billion) | |
  36. TABLE 22 Asia-Pacific Market Size, by Fuel Type, 2021–2035 (USD Billion) | |
  37. TABLE 23 South America Market Size, by Component, 2021–2035 (USD Billion) | |
  38. TABLE 24 South America Market Size, by Vehicle Type, 2021–2035 (USD Billion) | |
  39. TABLE 25 Middle East & Africa Market Size, by Component, 2021–2035 (USD Billion) | |
  40. TABLE 26 Middle East & Africa Market Size, by Fuel Type, 2021–2035 (USD Billion) | |
  41. TABLE 27 US Market Size, by Component, 2021–2035 (USD Billion) | |
  42. TABLE 28 China Market Size, by Component, 2021–2035 (USD Billion) | |
  43. TABLE 29 India Market Size, by Component, 2021–2035 (USD Billion) | |
  44. TABLE 30 Germany Market Size, by Component, 2021–2035 (USD Billion) | |
  45. TABLE 31 Japan Market Size, by Vehicle Type, 2021–2035 (USD Billion) | |
  46. TABLE 32 Brazil Market Size, by Fuel Type, 2021–2035 (USD Billion) | |
  47. TABLE 33 Competitive Benchmarking Matrix, 2026 | |
  48. TABLE 34 Company Profiles — Key Players | |
  49. TABLE 35 Recent Developments & Strategic Announcements, 2023–2025 | |
  50. TABLE 36 Report Scope & Methodology Summary | |
  51. TABLE 37 Detailed Sources and Citations | | LIST OF FIGURES | |
  52. FIGURE 1 Market Dynamics Overview — Drivers, Restraints and Opportunities | |
  53. FIGURE 2 Industry Value Chain Analysis | |
  54. FIGURE 3 Porter's Five Forces Analysis | |
  55. FIGURE 4 Global Market Size Trend, 2021–2035 (USD Billion) | |
  56. FIGURE 5 Year-over-Year Growth Trajectory, 2022–2035 (%) | |
  57. FIGURE 6 Market Share by Component, 2025 vs 2035 (%) | |
  58. FIGURE 7 Market Share by Vehicle Type, 2025 vs 2035 (%) | |
  59. FIGURE 8 Market Share by Fuel Type, 2025 vs 2035 (%) | |
  60. FIGURE 9 Regional Market Share Distribution, 2025 (%) | |
  61. FIGURE 10 Regional CAGR Comparison, 2026–2035 (%) | |
  62. FIGURE 11 North America Country-Level Share, 2025 (%) | |
  63. FIGURE 12 Europe Country-Level Share, 2025 (%) | |
  64. FIGURE 13 Asia-Pacific Country-Level Share, 2025 (%) | |
  65. FIGURE 14 Competitive Landscape — Revenue Share Positioning, 2026 | |
  66. FIGURE 15 Competitive Strategy Matrix — Product Breadth vs Software Capability | |
  67. FIGURE 16 Regulatory Timeline Map, 2023–2032 | |
  68. FIGURE 17 Sensor Content per Engine Trend, 2015–2035

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
By ComponentEngine Control Unit (ECU), Sensors, Fuel Injector, Fuel Pump, OthersEngine Control Unit (ECU)Sensors
By Vehicle TypePassenger Cars, Commercial VehiclesPassenger CarsCommercial Vehicles
By Fuel TypeGasoline, Diesel, Others (CNG, LPG, Flex-Fuel, Hydrogen ICE)GasolineOthers (CNG, LPG, Flex-Fuel, Hydrogen ICE)
By GeographyNorth America, Europe, Asia-Pacific, South America, Middle East & AfricaAsia-PacificNorth America


Market Segmentation Overview

By Component

Sub-SegmentKey Trend
Engine Control Unit (ECU)Migration to multicore processors with hardware security modules and over-the-air update partitions
SensorsChannel counts rising toward 22+ per turbocharged engine under extended durability testing.
Fuel InjectorDirect-injection penetration lifting content value to roughly double port-injection systems.
Fuel PumpHigh-pressure modules required for GDI; integration with thermal management
OthersIgnition coils, throttle bodies and harness interfaces consolidating into fewer part numbers.


Component value is migrating upward in the stack. Controllers absorb functions once handled by discrete modules, while sensing expands on unit count rather than unit price. Fuel delivery hardware grows more slowly, though direct injection has arrested what would otherwise be commodity price decline across injectors and high-pressure pumps.

By Vehicle Type

Sub-SegmentKey Trend
Passenger CarsHybridization preserves combustion control content even as battery-electric share rises.
Commercial VehiclesExtended emission warranty exposure driving investment in predictive diagnostics


Passenger cars supply the volume base, anchored in Chinese, Indian and Japanese assembly. Commercial vehicles grow faster because heavy-duty regulation arrived later and bites harder, and because fleet operators calculate downtime cost explicitly — making them willing buyers of diagnostic capability that private consumers rarely value at its engineering cost.

By Fuel Type

Sub-SegmentKey Trend
GasolineReinforced by hybrid pairing; remains the default global passenger powertrain.
DieselEntrenched in freight where energy density still wins on total cost of ownership
Others (CNG, LPG, Flex-Fuel, Hydrogen ICE)Regional fuel policy creating demand for configurable multi-fuel calibration maps


Fuel-type mix determines how much combustion control demand survives electrification. Gasoline benefits from hybrid architectures rather than losing to them. Diesel holds in heavy transport. The alternative category grows fastest from a small base, concentrated in Brazil, South Asia and early hydrogen combustion demonstrations in long-haul freight.




Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.