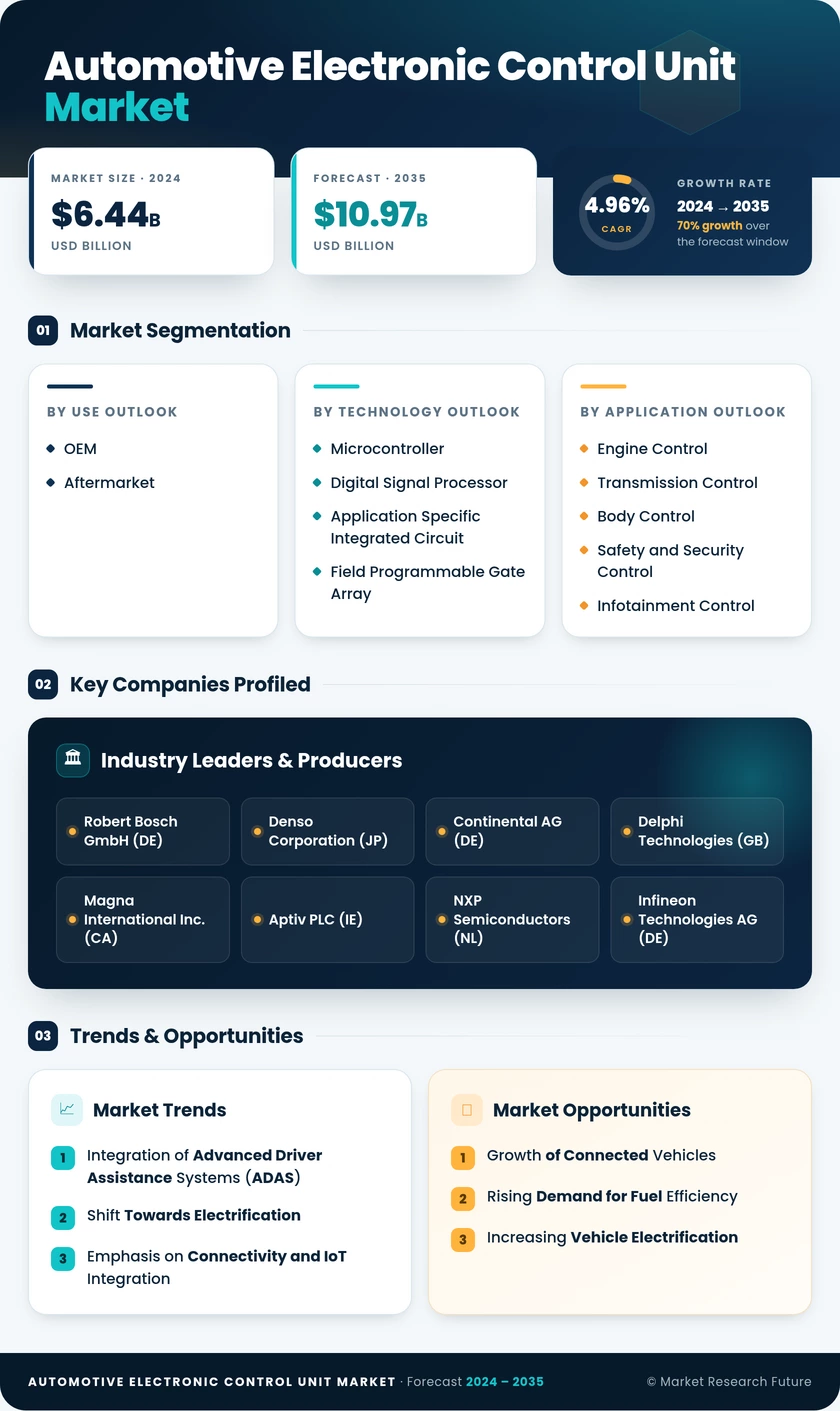
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| By Propulsion | Internal Combustion Engine, Hybrid, Battery Electric Vehicle | Internal Combustion Engine | Battery Electric Vehicle |
| By Application | Powertrain, ADAS & Safety Systems, Body Electronics & Comfort, Infotainment & Communication, Chassis & Suspension | Powertrain | Infotainment & Communication |
| By ECU Capacity | 16-Bit ECU, 32-Bit ECU, 64-Bit ECU | 32-Bit ECU | 64-Bit ECU |
| By Autonomy Level | Conventional (L0–L1), L2, L3, L4–L5 | Conventional (L0–L1) | L4–L5 |
| By Vehicle Type | Passenger Car, Light Commercial Vehicle, Heavy Commercial Vehicle | Passenger Car | Light Commercial Vehicle |
| By Geography | North America, Europe, Asia-Pacific, South America, Middle East & Africa | Asia-Pacific | Asia-Pacific |
Market Segmentation Overview
By Propulsion
| Sub-Segment | Key Trend |
| Internal Combustion Engine | Euro 7 and China 6b aftertreatment control raising content on mature platforms |
| Hybrid | Dual-propulsion arbitration logic carrying the highest per-vehicle complexity of any drivetrain |
| Battery Electric Vehicle | Four incremental control domains per vehicle; 800V migration reshaping inverter requirements |
Propulsion remains the most consequential segmentation axis because it determines the baseline node count before any optional feature is specified. Combustion volume sustains near-term revenue while electric platforms drive the growth rate.
By Application
| Sub-Segment | Key Trend |
| Powertrain | Decomposition of the single engine controller into distributed injection, aftertreatment and drive nodes |
| ADAS & Safety Systems | Regulatory mandates converting optional content into baseline specification across all trims. |
| Body Electronics & Comfort | Feature democratization pushing premium comfort functions into mainstream vehicles. |
| Infotainment & Communication | Cockpit domain consolidation raising value per node while reducing node count. |
| Chassis & Suspension | Brake-by-wire and adaptive damping adoption in mid-segment platforms |
Application-level demand is bifurcating. Regulated safety functions grow through mandate, while comfort and infotainment functions grow through consumer expectation, and the two respond to entirely different commercial levers.
By ECU Capacity
| Sub-Segment | Key Trend |
| 16-Bit ECU | Persistent demand in cost-optimized lighting, seating and mirror functions |
| 32-Bit ECU | Industry default for safety-relevant control; gradual share erosion without volume collapse |
| 64-Bit ECU | Hypervisor and virtualization support enabling multi-domain consolidation onto single silicon |
Compute width tracks architectural position more than vehicle price point. High-value consolidation targets migrate to 64-bit while peripheral functions stay comfortably on legacy tiers.
By Autonomy Level
| Sub-Segment | Key Trend |
| Conventional (L0–L1) | Declining share as regulatory floors rise in developed markets |
| L2 | Becoming effectively mandated content in Europe and North America |
| L3 | Conditional automation approvals expanding beyond Germany and Japan |
| L4–L5 | Robotaxi and closed-campus deployments driving the highest compute density per vehicle. |
Autonomy tier is the clearest predictor of perception compute spend. Each step up roughly doubles required throughput, which is why L4–L5 volumes remain small yet disproportionately valuable.
By Vehicle Type
| Sub-Segment | Key Trend |
| Passenger Car | Consumer feature expectations and safety regulation setting a rising content floor |
| Light Commercial Vehicle | Last-mile delivery electrification favoring electric drivetrains on fixed urban routes |
| Heavy Commercial Vehicle | Telematics, platooning readiness and mandated safety retrofit across existing fleets |
Commercial vehicles are closing the content gap with passenger cars faster than most forecasts assumed, largely because fleet operators evaluate safety electronics on insurance and downtime economics rather than on sticker price.


 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA