Automotive Digital Instrument Cluster Market (2026 - 2035)

ID: MRFR/AT/4255-HCR 100 Pages Triveni Bhoyar Last Updated: September 28, 2026
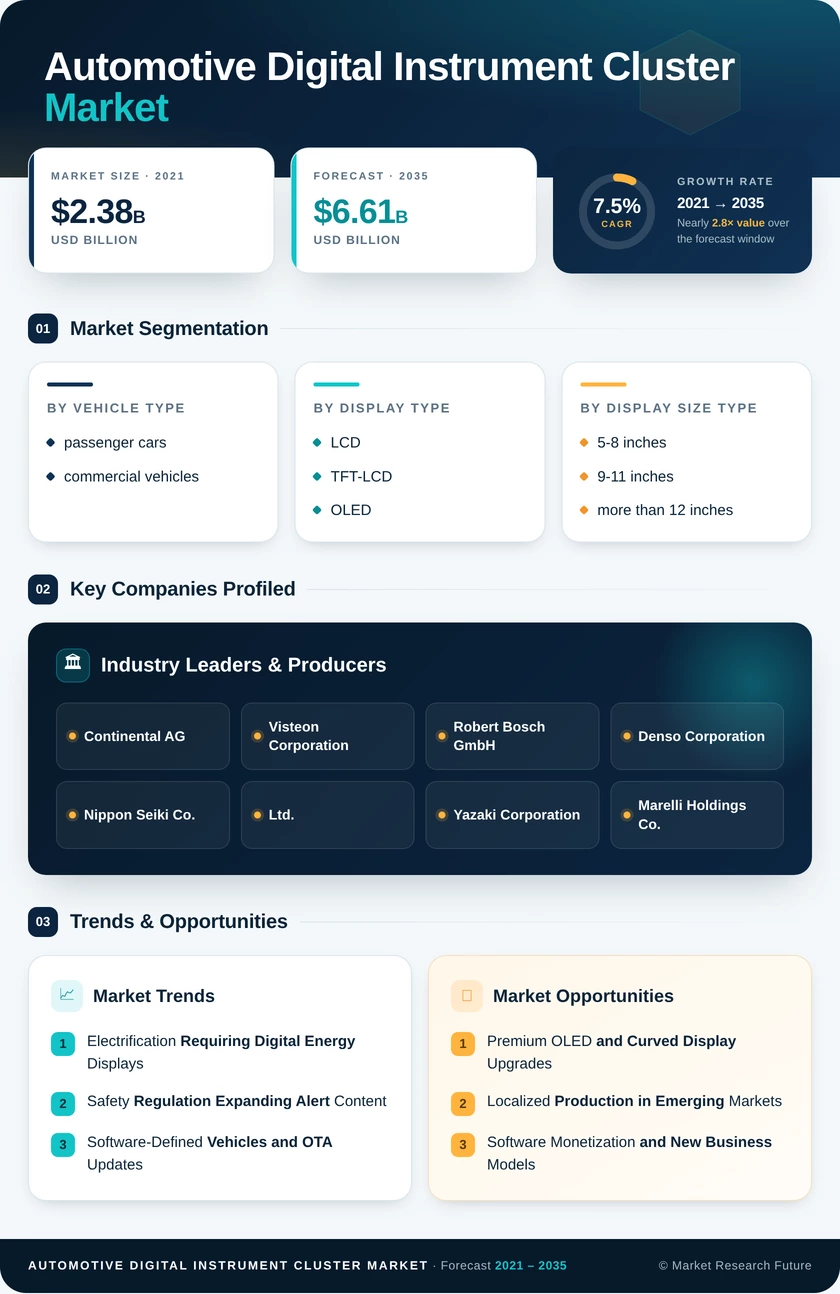
Automotive Digital Instrument Cluster Market Research Report By Vehicle Type (Passenger Cars, Commercial Vehicles), By Display Type (LCD, TFT-LCD, OLED), By Display Size Type (5-8 Inches, 9-11 Inches, More than 12 Inches) - Forecast to 2035
Automotive Digital Instrument Cluster Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)7.5%
2025 Market SizeUSD 3.21 Billion
2035 Market SizeUSD 6.61 Billion
Key Players
Continental AG
Visteon Corporation
Robert Bosch GmbH
Denso Corporation
Nippon Seiki Co., Ltd.
Yazaki Corporation
Opportunities
  • Premium OLED and Curved Display Upgrades
  • Localized Production in Emerging Markets
  • Software Monetization and New Business Models
  1. 1 Market Summary | |
  2. 2 Key Report Takeaways | |
    1. 2.1 By Vehicle Type | |
    2. 2.2 By Display Type | |
    3. 2.3 By Display Size Type | |
    4. 2.4 By Region | |
  3. 3 Market Size and Forecast (2021–2035) | |
  4. 4 Driver Impact Analysis | |
    1. 4.1 Electrification Requiring Digital Energy Displays | |
    2. 4.2 Safety Regulation Expanding Alert Content | |
    3. 4.3 Software-Defined Vehicles and OTA Updates | |
    4. 4.4 Consumer Demand for Larger, Customizable Screens | |
    5. 4.5 Semiconductor Localization Programs | |
    6. 4.6 Asia-Pacific Production Incentives | |
  5. 5 Restraints Impact Analysis | |
    1. 5.1 Display Panel and Chip Supply Volatility | |
    2. 5.2 Cost Premium in Entry-Level Vehicles | |
    3. 5.3 Cybersecurity Compliance Burden | |
    4. 5.4 Driver Distraction and HMI Scrutiny | |
    5. 5.5 Cockpit Consolidation Eroding Standalone Cluster Value | |
  6. 6 Opportunities | |
    1. 6.1 Premium OLED and Curved Display Upgrades | |
    2. 6.2 Localized Production in Emerging Markets | |
    3. 6.3 Software Monetization and New Business Models | |
    4. 6.4 Commercial Vehicle and Fleet Digitalization | |
    5. 6.5 Augmented Reality Head-Up Integration | |
  7. 7 Regional Market Share and Country-Level Analysis | |
    1. 7.1 North America | | |
      1. 7.1.1 United States | | |
      2. 7.1.2 Canada | | |
      3. 7.1.3 Rest of North America | |
    2. 7.2 Europe | | |
      1. 7.2.1 Germany | | |
      2. 7.2.2 United Kingdom | | |
      3. 7.2.3 France | | |
      4. 7.2.4 Rest of Europe | |
    3. 7.3 Asia-Pacific | | |
      1. 7.3.1 India | | |
      2. 7.3.2 China | | |
      3. 7.3.3 Japan | | |
      4. 7.3.4 South Korea | | |
      5. 7.3.5 Rest of Asia-Pacific | |
    4. 7.4 Rest of the World | | |
      1. 7.4.1 Brazil | | |
      2. 7.4.2 Mexico | | |
      3. 7.4.3 United Arab Emirates | | |
      4. 7.4.4 Other Countries | |
  8. 8 Future Outlook (2026–2035) | |
    1. 8.1 AI-Driven Adaptive Interfaces and Automated Driving | |
    2. 8.2 Centralized Compute and Platform Economics | |
    3. 8.3 Electrification Through | |
    4. 8.4 Sustainability and Circular Electronics | |
  9. 9 Segmentation Analysis | |
    1. 9.1 By Vehicle Type | | |
      1. 9.1.1 Passenger cars | | |
      2. 9.1.2 Commercial vehicles | |
    2. 9.2 By Display Type | | |
      1. 9.2.1 LCD | | |
      2. 9.2.2 TFT-LCD | | |
      3. 9.2.3 OLED | |
    3. 9.3 By Display Size Type | | |
      1. 9.3.1 5-8 inches | | |
      2. 9.3.2 9-11 inches | | |
      3. 9.3.3 More than 12 inches | |
  10. 10 Competitive Landscape | |
  11. 11 Recent News & Developments | |
  12. 12 Report Scope and Methodology | |
  13. 13 Detailed Sources and Citations | |
  14. 14 Frequently Asked Questions (FAQs) | | LIST OF TABLES | |
  15. TABLE 1 Global Market Size & Forecast, by Revenue (USD Billion), 2021–2035 | |
  16. TABLE 2 Driver Impact Analysis, 2026–2035 | |
  17. TABLE 3 Restraints Impact Analysis, 2026–2035 | |
  18. TABLE 4 Regional Summary, by Region, 2025 | |
  19. TABLE 5 North America Market, by Country, 2025 | |
  20. TABLE 6 Europe Market, by Country, 2025 | |
  21. TABLE 7 Asia-Pacific Market, by Country, 2025 | |
  22. TABLE 8 Rest of the World Market, by Country, 2025 | |
  23. TABLE 9 Global Market, by Vehicle Type, 2025 | |
  24. TABLE 10 Global Market, by Display Type, 2025 | |
  25. TABLE 11 Global Market, by Display Size Type, 2025 | |
  26. TABLE 12 Competitive Benchmarking Matrix, 2025 | |
  27. TABLE 13 Report Scope and Methodology | |
  28. TABLE 14 Detailed Sources and Citations | | LIST OF FIGURES | |
  29. FIGURE 1 Market Dynamics Overview: Drivers, Restraints, and Opportunities | |
  30. FIGURE 2 Industry Value Chain Analysis | |
  31. FIGURE 3 Porter's Five Forces Analysis | |
  32. FIGURE 4 Global Market Size Trend (USD Billion), 2021–2035 | |
  33. FIGURE 5 Market Share, by Vehicle Type, 2025 | |
  34. FIGURE 6 Market Share, by Display Type, 2025 | |
  35. FIGURE 7 Market Share, by Display Size Type, 2025 | |
  36. FIGURE 8 Regional Market Share, 2025 | |
  37. FIGURE 9 Competitive Landscape: Estimated Revenue Share Ranges, 2025

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
By Vehicle Typepassenger cars, commercial vehiclespassenger cars (81.5% share)commercial vehicles (8.3% CAGR)
By Display TypeLCD, TFT-LCD, OLEDTFT-LCD (63.0% share)OLED (12.4% CAGR)
By Display Size Type5-8 inches, 9-11 inches, more than 12 inches9-11 inches (44.0% share)more than 12 inches (10.6% CAGR)
By RegionNorth America, Europe, Asia-Pacific, Rest of the WorldEurope (36.5% share)Asia-Pacific (9.1% CAGR)


Market Segmentation Overview

By Vehicle Type

Sub-SegmentKey Trend
passenger carsDigital clusters becoming standard from compact to premium trims
commercial vehiclesTelematics-integrated, ruggedized clusters for fleets and electric trucks


Passenger cars lead with an 81.5% share because OEMs now fit digital clusters as standard across most model lines, with EVs setting the pace. Commercial vehicles grow fastest at an 8.3% CAGR, since fleet operators need tachograph data, driver coaching, and charging status on one display. Truck duty cycles also require ruggedized panels, which carry higher unit value.

By Display Type

Sub-SegmentKey Trend
LCDRetained in segmented and monochrome layouts for cost-sensitive trims
TFT-LCDMainstream full-color standard with falling panel prices
OLEDThin, curved, high-contrast panels for premium EVs


TFT-LCD leads with a 63.0% share because automotive-grade supply is mature and the panels tolerate extreme cabin temperatures. OLED grows fastest at a 12.4% CAGR as tandem-stack designs reduce burn-in risk and premium EV brands use curved panels for differentiation. LCD persists in entry trims, where segmented displays still meet cost targets.

By Display Size Type

Sub-SegmentKey Trend
5-8 inchesBudget vehicles and hybrid analog-digital layouts
9-11 inchesMainstream packaging balance of readability and cost
More than 12 inchesPanoramic and pillar-to-pillar premium cockpits


The 9-11 inches band leads with a 44.0% share because it fits standard dashboard binnacles without structural redesign. More than 12 inches grows fastest at a 10.6% CAGR as panoramic EV cockpits extend clusters across the instrument panel. The 5-8 inches size remains the practical choice for budget platforms where cost and space are tight.




Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.