Automotive Diagnostic Scan Tools Market (2026 - 2035)

ID: MRFR/AT/5714-CR 100 Pages Shubham Munde Last Updated: September 16, 2026
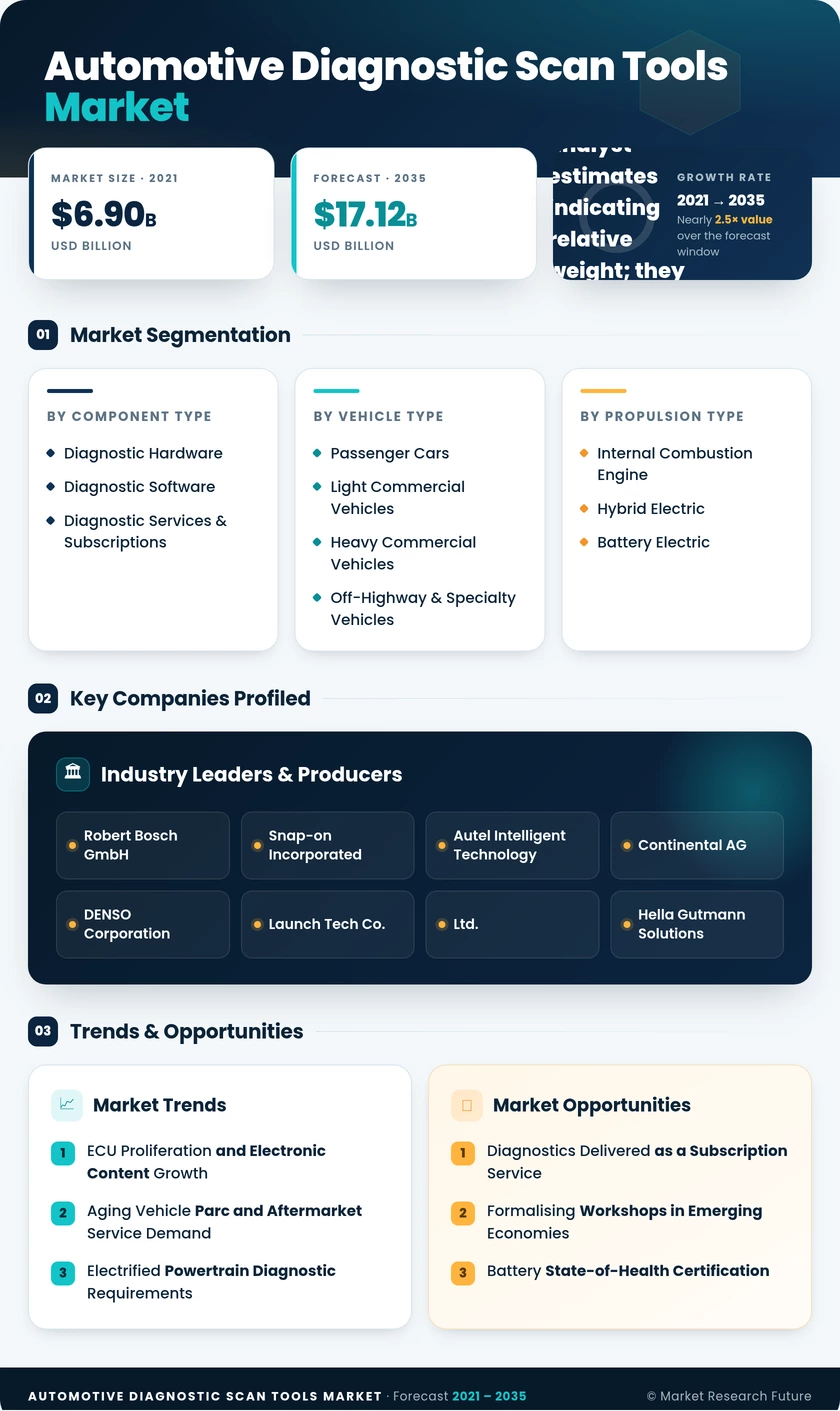
Automotive Diagnostic Scan Tools Market Research Report By Component Type (Diagnostic Hardware, Diagnostic Software, Diagnostic Services & Subscriptions), By Vehicle Type (Passenger Cars, Light Commercial Vehicles, Heavy Commercial Vehicles, Off-Highway & Specialty Vehicles), By Propulsion Type (Internal Combustion Engine, Hybrid Electric, Battery Electric), By Technology (Wired Interfaces, Wireless (Bluetooth/Wi-Fi) Interfaces, Cloud-Connected & Remote Diagnostic Platforms, AI-Enabled Predictive Diagnostics), By Application (OEM Dealerships & Authorised Service Networks, Independent Aftermarket Workshops, Fleet & Leasing Operators, DIY / Consumer) - Forecast to 2035
Automotive Diagnostic Scan Tools Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)6.4%
2025 Market SizeUSD 9.20 Billion
2035 Market SizeUSD 17.12 Billion
Key Players
Robert Bosch GmbH
Snap-on Incorporated
Autel Intelligent Technology
Continental AG
DENSO Corporation
Launch Tech Co., Ltd.
Opportunities
  • Diagnostics Delivered as a Subscription Service
  • Formalising Workshops in Emerging Economies
  • Battery State-of-Health Certification
  1. 1 Market Summary | |
    1. 1.1 Study Assumptions & Market Definition | |
    2. 1.2 Scope of the Study | |
    3. 1.3 Research Methodology | |
  2. 2 Key Report Takeaways | |
    1. 2.1 By Component Type | |
    2. 2.2 By Vehicle Type | |
    3. 2.3 By Propulsion Type | |
    4. 2.4 By Technology | |
    5. 2.5 By Application | |
    6. 2.6 By Region | |
  3. 3 Market Size and Forecast (2021–2035) | |
    1. 3.1 Historical Market Size (2021–2025) | |
    2. 3.2 Current & Forecast Market Size (2026–2035) | |
    3. 3.3 Market Size by Revenue (USD Billion) | |
    4. 3.4 Year-over-Year Growth Analysis | |
  4. 4 Driver Impact Analysis | |
    1. 4.1 ECU Proliferation and Electronic Content Growth | |
    2. 4.2 Aging Vehicle Parc and Aftermarket Service Demand | |
    3. 4.3 Electrified Powertrain Diagnostic Requirements | |
    4. 4.4 In-Service Emissions and Inspection Mandates | |
    5. 4.5 Sensor Recalibration After Collision and Routine Repair | |
    6. 4.6 Cloud-Connected and Remote Service Delivery | |
    7. 4.7 Independent Repair Data-Access Legislation | |
  5. 5 Restraints Impact Analysis | |
    1. 5.1 Cost of Manufacturer-Level Licences and Subscriptions | |
    2. 5.2 Technician Skills Shortage | |
    3. 5.3 Secure Gateway and Cybersecurity Access Controls | |
    4. 5.4 Protocol Fragmentation and Update Burden | |
    5. 5.5 Reduced Routine Powertrain Service on Electric Platforms | |
  6. 6 Opportunities | |
    1. 6.1 Diagnostics Delivered as a Subscription Service | |
    2. 6.2 Formalising Workshops in Emerging Economies | |
    3. 6.3 Battery State-of-Health Certification | |
    4. 6.4 Fleet Integration and Scheduled Intervention | |
    5. 6.5 Heavy-Duty and Off-Highway Coverage | |
  7. 7 Regional Market Share and Country-Level Analysis | |
    1. 7.1 North America | | |
      1. 7.1.1 United States | | |
      2. 7.1.2 Canada | | |
      3. 7.1.3 Mexico | |
    2. 7.2 Europe | | |
      1. 7.2.1 Germany | | |
      2. 7.2.2 United Kingdom | | |
      3. 7.2.3 France | | |
      4. 7.2.4 Italy | | |
      5. 7.2.5 Rest of Europe | |
    3. 7.3 Asia-Pacific | | |
      1. 7.3.1 China | | |
      2. 7.3.2 Japan | | |
      3. 7.3.3 India | | |
      4. 7.3.4 South Korea | | |
      5. 7.3.5 Rest of Asia-Pacific | |
    4. 7.4 South America | | |
      1. 7.4.1 Brazil | | |
      2. 7.4.2 Argentina | | |
      3. 7.4.3 Rest of South America | |
    5. 7.5 Middle East & Africa | | |
      1. 7.5.1 Saudi Arabia | | |
      2. 7.5.2 United Arab Emirates | | |
      3. 7.5.3 South Africa | | |
      4. 7.5.4 Rest of Middle East & Africa | |
  8. 8 Future Outlook (2026–2035) | |
    1. 8.1 From Fault Reading to Fault Prediction | |
    2. 8.2 Platform Economics Reshape Vendor Margins | |
    3. 8.3 The Electrification Supercycle Arrives in the Aftermarket | |
    4. 8.4 Access Rules Become the Governing Variable | |
  9. 9 Segmentation Analysis | |
    1. 9.1 By Component Type | | |
      1. 9.1.1 Diagnostic Hardware | | |
      2. 9.1.2 Diagnostic Software | | |
      3. 9.1.3 Diagnostic Services & Subscriptions | |
    2. 9.2 By Vehicle Type | | |
      1. 9.2.1 Passenger Cars | | |
      2. 9.2.2 Light Commercial Vehicles | | |
      3. 9.2.3 Heavy Commercial Vehicles | | |
      4. 9.2.4 Off-Highway & Specialty Vehicles | |
    3. 9.3 By Propulsion Type | | |
      1. 9.3.1 Internal Combustion Engine | | |
      2. 9.3.2 Hybrid Electric | | |
      3. 9.3.3 Battery Electric | |
    4. 9.4 By Technology | | |
      1. 9.4.1 Wired Interfaces | | |
      2. 9.4.2 Wireless (Bluetooth/Wi-Fi) Interfaces | | |
      3. 9.4.3 Cloud-Connected & Remote Diagnostic Platforms | | |
      4. 9.4.4 AI-Enabled Predictive Diagnostics | |
    5. 9.5 By Application | | |
      1. 9.5.1 OEM Dealerships & Authorised Service Networks | | |
      2. 9.5.2 Independent Aftermarket Workshops | | |
      3. 9.5.3 Fleet & Leasing Operators | | |
      4. 9.5.4 DIY / Consumer | |
  10. 10 Competitive Landscape | |
    1. 10.1 Market Share Analysis (2026) | |
    2. 10.2 Competitive Benchmarking Matrix | |
    3. 10.3 Company Profiles | | |
      1. 10.3.1 Robert Bosch GmbH | | |
      2. 10.3.2 Snap-on Incorporated | | |
      3. 10.3.3 Autel Intelligent Technology | | |
      4. 10.3.4 Continental AG | | |
      5. 10.3.5 DENSO Corporation | | |
      6. 10.3.6 Launch Tech Co., Ltd. | | |
      7. 10.3.7 Hella Gutmann Solutions | | |
      8. 10.3.8 BorgWarner (Delphi Technologies) | | |
      9. 10.3.9 Actia Group | | |
      10. 10.3.10 Softing AG / Vector Informatik | |
  11. 11 Recent News & Developments | |
  12. 12 Report Scope and Methodology | |
    1. 12.1 Study Period & Base Year | |
    2. 12.2 Data Sources & Citations | |
    3. 12.3 Abbreviations | |
  13. 13 Detailed Sources and Citations | |
  14. 14 Frequently Asked Questions (FAQs) | | LIST OF TABLES | |
  15. TABLE 1 Global Automotive Diagnostic Scan Tools Market Size & Forecast, by Revenue (USD Billion), 2021–2035 | |
  16. TABLE 2 Global Automotive Diagnostic Scan Tools Market — Year-over-Year Growth Analysis, 2021–2035 | |
  17. TABLE 3 Driver Impact Analysis — Estimated Contribution to CAGR, 2026–2035 | |
  18. TABLE 4 Restraint Impact Analysis — Estimated Drag on CAGR, 2026–2035 | |
  19. TABLE 5 Global Market Size, by Component Type, 2021–2035 (USD Billion) | |
  20. TABLE 6 Global Market Size, by Vehicle Type, 2021–2035 (USD Billion) | |
  21. TABLE 7 Global Market Size, by Propulsion Type, 2021–2035 (USD Billion) | |
  22. TABLE 8 Global Market Size, by Technology, 2021–2035 (USD Billion) | |
  23. TABLE 9 Global Market Size, by Application, 2021–2035 (USD Billion) | |
  24. TABLE 10 Global Market Size, by Region, 2021–2035 (USD Billion) | |
  25. TABLE 11 Regional Summary — Share, Value and Investment Themes, 2025 | |
  26. TABLE 12 North America Market Size, by Country, 2021–2035 (USD Billion) | |
  27. TABLE 13 Europe Market Size, by Country, 2021–2035 (USD Billion) | |
  28. TABLE 14 Asia-Pacific Market Size, by Country, 2021–2035 (USD Billion) | |
  29. TABLE 15 South America Market Size, by Country, 2021–2035 (USD Billion) | |
  30. TABLE 16 Middle East & Africa Market Size, by Country, 2021–2035 (USD Billion) | |
  31. TABLE 17 North America Market Size, by Component Type, 2021–2035 (USD Billion) | |
  32. TABLE 18 North America Market Size, by Application, 2021–2035 (USD Billion) | |
  33. TABLE 19 Europe Market Size, by Component Type, 2021–2035 (USD Billion) | |
  34. TABLE 20 Europe Market Size, by Propulsion Type, 2021–2035 (USD Billion) | |
  35. TABLE 21 Asia-Pacific Market Size, by Component Type, 2021–2035 (USD Billion) | |
  36. TABLE 22 Asia-Pacific Market Size, by Vehicle Type, 2021–2035 (USD Billion) | |
  37. TABLE 23 South America Market Size, by Application, 2021–2035 (USD Billion) | |
  38. TABLE 24 Middle East & Africa Market Size, by Application, 2021–2035 (USD Billion) | |
  39. TABLE 25 United States Market Size, by Component Type, 2021–2035 (USD Billion) | |
  40. TABLE 26 China Market Size, by Technology, 2021–2035 (USD Billion) | |
  41. TABLE 27 India Market Size, by Vehicle Type, 2021–2035 (USD Billion) | |
  42. TABLE 28 Germany Market Size, by Application, 2021–2035 (USD Billion) | |
  43. TABLE 29 Competitive Benchmarking Matrix, 2026 | |
  44. TABLE 30 Company Profiles — Key Players | |
  45. TABLE 31 Recent Developments & Strategic Announcements, 2023–2025 | |
  46. TABLE 32 Report Scope & Methodology Summary | |
  47. TABLE 33 Detailed Sources and Citations | | LIST OF FIGURES | |
  48. FIGURE 1 Market Dynamics — Drivers, Restraints and Opportunities Overview | |
  49. FIGURE 2 Industry Value Chain Analysis | |
  50. FIGURE 3 Porter's Five Forces Analysis | |
  51. FIGURE 4 Global Market Size Trend, 2021–2035 (USD Billion) | |
  52. FIGURE 5 Year-over-Year Growth Trend, 2022–2035 (%) | |
  53. FIGURE 6 Market Share by Component Type, 2025 vs 2035 (%) | |
  54. FIGURE 7 Market Share by Vehicle Type, 2025 (%) | |
  55. FIGURE 8 Market Share by Propulsion Type, 2025 vs 2035 (%) | |
  56. FIGURE 9 Market Share by Technology, 2025 (%) | |
  57. FIGURE 10 Market Share by Application, 2025 (%) | |
  58. FIGURE 11 Regional Revenue Share, 2025 (%) | |
  59. FIGURE 12 Regional CAGR Comparison, 2026–2035 (%) | |
  60. FIGURE 13 North America Country-Level Share, 2025 (%) | |
  61. FIGURE 14 Asia-Pacific Country-Level Share, 2025 (%) | |
  62. FIGURE 15 Competitive Landscape — Estimated Revenue Share Ranges, 2026 | |
  63. FIGURE 16 Vendor Positioning Matrix — Coverage Depth vs Price Point

Market Segmentation Analysis

By Component Type

Diagnostic Hardware

Diagnostic Software

Diagnostic Services & Subscriptions

By Vehicle Type

Passenger Cars

Light Commercial Vehicles

Heavy Commercial Vehicles

Off-Highway & Specialty Vehicles

By Propulsion Type

Internal Combustion Engine

Hybrid Electric

Battery Electric

By Technology

Wired Interfaces

Wireless (Bluetooth/Wi-Fi) Interfaces

Cloud-Connected & Remote Diagnostic Platforms

AI-Enabled Predictive Diagnostics

By Application

OEM Dealerships & Authorised Service Networks

Independent Aftermarket Workshops

Fleet & Leasing Operators

DIY / Consumer

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
By Component TypeDiagnostic Hardware; Diagnostic Software; Diagnostic Services & SubscriptionsDiagnostic Hardware (54.0% share, 2025)Diagnostic Services & Subscriptions (9.1% CAGR, 2026–2035)
By Vehicle TypePassenger Cars; Light Commercial Vehicles; Heavy Commercial Vehicles; Off-Highway & Specialty VehiclesPassenger Cars (61.5% share, 2025)Light Commercial Vehicles (7.0% CAGR, 2026–2035)
By Propulsion TypeInternal Combustion Engine; Hybrid Electric; Battery ElectricInternal Combustion Engine (72.0% share, 2025)Battery Electric (14.6% CAGR, 2026–2035)
By TechnologyWired Interfaces; Wireless (Bluetooth/Wi-Fi) Interfaces; Cloud-Connected & Remote Diagnostic Platforms; AI-Enabled Predictive DiagnosticsWired Interfaces (46.0% share, 2025)AI-Enabled Predictive Diagnostics (16.2% CAGR, 2026–2035)
By ApplicationOEM Dealerships & Authorised Service Networks; Independent Aftermarket Workshops; Fleet & Leasing Operators; DIY / ConsumerOEM Dealerships & Authorised Service Networks (38.0% share, 2025)Fleet & Leasing Operators (9.4% CAGR, 2026–2035)


Market Segmentation Overview

By Component Type

Sub-SegmentKey Trend
Diagnostic HardwareMulti-protocol interfaces replace single-generation readers; unit prices hold as capability rises
Diagnostic SoftwareCoverage libraries expand across model years, making breadth the primary purchase criterion
Diagnostic Services & SubscriptionsHosted procedures and remote expert sessions convert one-time sales into annual renewals


Diagnostic hardware leads this dimension at 54.0% share because no session begins without a physical interface capable of reaching the controller network, and workshops replace those interfaces on protocol cycles rather than annual ones. Diagnostic services and subscriptions grow fastest at 9.1% CAGR, driven by vendors moving update delivery, guided procedures, and technical support behind renewable licences. Diagnostic software occupies the middle position, competing on how many manufacturers and model years its library covers rather than on unit volume.

By Vehicle Type

Sub-SegmentKey Trend
Passenger CarsAging parc sustains volume; electronic content per vehicle rises steadily
Light Commercial VehiclesDelivery fleet growth makes uptime the dominant purchase justification
Heavy Commercial VehiclesHigh downtime cost supports premium equipment and thinner competition
Off-Highway & Specialty VehiclesConstruction and agricultural electronics create underserved coverage gaps


Passenger cars dominate at 61.5% share, a function of parc scale rather than per-vehicle diagnostic spend, and that position holds throughout the forecast. Light commercial vehicles grow fastest at 7.0% CAGR because last-mile delivery operators treat a stationary van as directly lost revenue and buy equipment on uptime economics rather than repair-order margin. Heavy commercial vehicles contribute disproportionate value per session, since coverage is thinner and each fault carries higher cost.

By Propulsion Type

Sub-SegmentKey Trend
Internal Combustion EngineEmissions monitor verification sustains demand well past 2030
Hybrid ElectricDual powertrains require two distinct diagnostic domains in one vehicle
Battery ElectricPost-warranty vehicles enter independent channels, forcing capability investment


Internal combustion platforms lead at 72.0% share and will remain the volume base for years, because parc turnover is slow and in-service emissions checks keep those vehicles cycling through workshops. Battery electric grows fastest at 14.6% CAGR as vehicles delivered earlier this decade leave warranty and arrive at independent shops that must equip for high-voltage isolation and pack testing. Hybrid electric sits awkwardly between the two, requiring competence in both domains and therefore the broadest tool specification.

By Technology

Sub-SegmentKey Trend
Wired InterfacesPreferred for module programming where connection loss risks controller damage
Wireless (Bluetooth/Wi-Fi) InterfacesBay mobility supports multi-vehicle workflow and faster throughput
Cloud-Connected & Remote Diagnostic PlatformsHosted access resolves the mismatch between rare faults and scarce specialists
AI-Enabled Predictive DiagnosticsFleet-scale fault histories enable intervention before failure occurs


Wired interfaces lead at 46.0% share for a practical reason: technicians will not risk a dropped connection during flashing, where failure can render a controller unusable. AI-enabled predictive diagnostics grows fastest at 16.2% CAGR, though from a base small enough that its absolute contribution stays limited until the early 2030s. Wireless interfaces hold the largest share of the growth-stage segments, winning on workflow speed in high-throughput bays where mobility between vehicles matters more than session stability.

By Application

Sub-SegmentKey Trend
OEM Dealerships & Authorised Service NetworksWarranty work requires factory-credentialed equipment and procedures
Independent Aftermarket WorkshopsPost-warranty volume on aging vehicles drives multi-brand coverage demand
Fleet & Leasing OperatorsProcurement-budget purchasing tied to uptime rather than billable hours
DIY / ConsumerSmartphone-linked readers serve basic code retrieval at low price points


Dealerships and authorised service networks lead at 38.0% share, sustained by warranty work that only factory-credentialed equipment can complete and by manufacturer requirements around calibration procedures. Fleet and leasing operators grow fastest at 9.4% CAGR because they buy from procurement budgets, size purchases against avoided downtime, and increasingly want equipment that feeds directly into maintenance planning systems. Independent workshops remain the larger long-run pool as the parc ages, but their purchasing is more price-constrained.


just now

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.