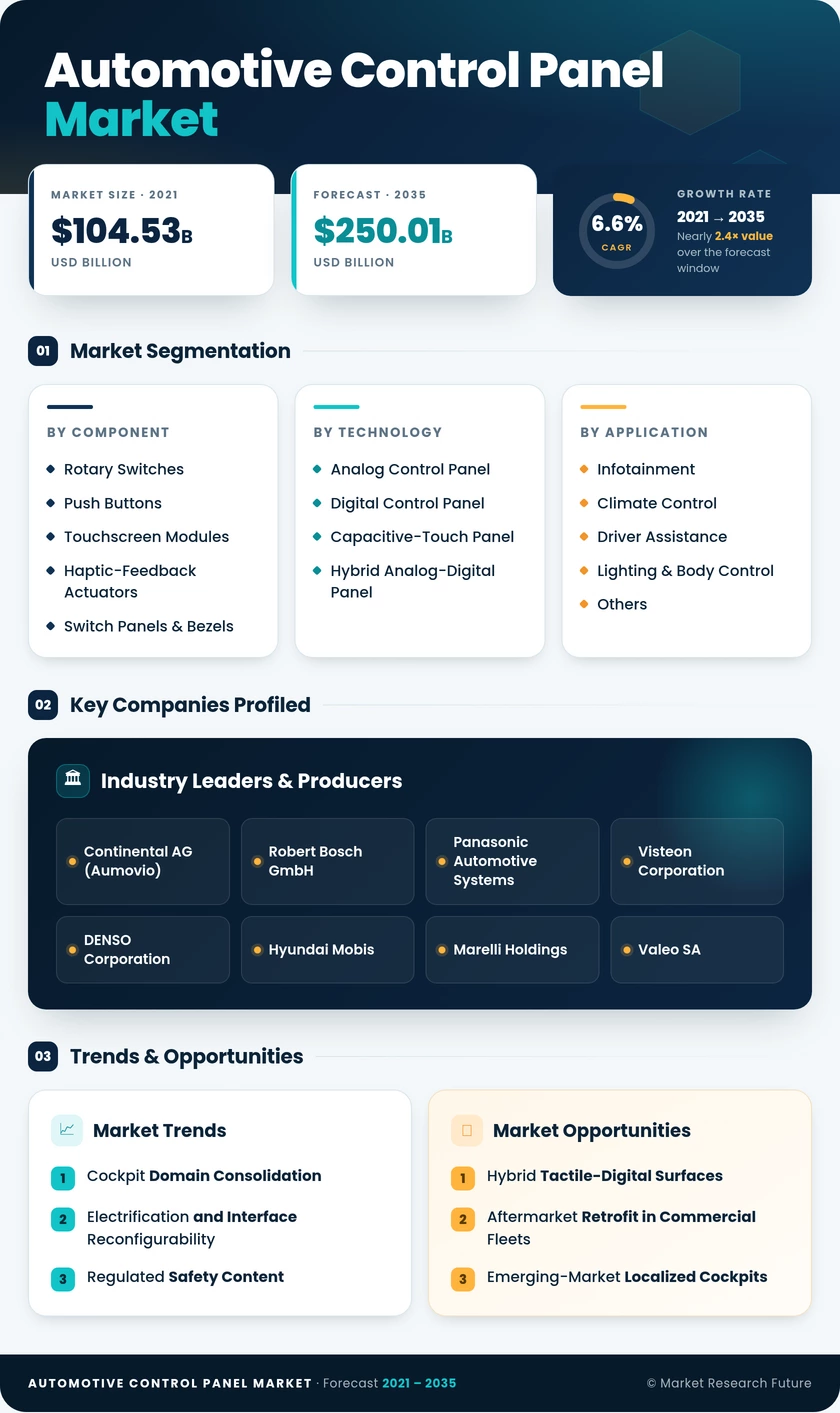
Automotive Control Panel Market (2026 - 2035)

ID: MRFR/AT/3871-HCR 100 Pages Triveni Bhoyar Last Updated: September 15, 2026
Automotive Control Panel Market Research Report By Component (Rotary Switches, Push Buttons, Touchscreen Modules, Haptic-Feedback Actuators, Switch Panels & Bezels, Others), By Technology (Analog Control Panel, Digital Control Panel, Capacitive-Touch Panel, Hybrid Analog-Digital Panel, Force-Sensing Panel), By Application (Infotainment, Climate Control, Driver Assistance, Lighting & Body Control, Others, Navigation), By Vehicle Type (Passenger Cars, Light Commercial Vehicles, Heavy Commercial Vehicles, Buses & Coaches), By Distribution Channel (OEM, Aftermarket) and By Regional (North America, Europe, South America, Asia Pacific, Middle East and Africa) - Growth & Industry Forecast to 2035
Automotive Control Panel Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)6.6%
2025 Market SizeUSD 131.94 Billion
2035 Market SizeUSD 250.01 Billion
Key Players
Continental AG
Robert Bosch GmbH
Panasonic Automotive Systems
Visteon Corporation
DENSO Corporation
Hyundai Mobis
Opportunities
  • Hybrid Tactile-Digital Surfaces
  • Aftermarket Retrofit in Commercial Fleets
  • Emerging-Market Localized Cockpits
  1. 1 Market Overview |
    1. 1.1 Study Assumptions & Market Definition |
    2. 1.2 Scope of the Study |
    3. 1.3 Research Methodology
  2. 2 Market Summary & Key Takeaways |
    1. 2.1 Key Takeaways by Technology |
    2. 2.2 Key Takeaways by Sector |
    3. 2.3 Key Takeaways by Region
  3. 3 Global Market Size & Forecast (2021–2035) |
    1. 3.1 Historical Market Size (2021–2025) |
    2. 3.2 Current & Forecast Market Size (2026–2035) |
    3. 3.3 Market Size by Revenue (USD Billion) |
    4. 3.4 Year-over-Year Growth Analysis
  4. 4 Market Drivers Analysis |
    1. 4.1 Cockpit Domain Consolidation |
    2. 4.2 Electrification and Interface Reconfigurability |
    3. 4.3 Regulated Safety Content |
    4. 4.4 Cost Deflation in Display Supply |
    5. 4.5 Driver Impact Matrix
  5. 5 Market Restraints Analysis |
    1. 5.1 The Return of the Physical Button |
    2. 5.2 Certification Cost and Cycle Time |
    3. 5.3 Affordability Pressure in Volume Segments |
    4. 5.4 Restraint Impact Matrix
  6. 6 Market Opportunity Analysis |
    1. 6.1 Hybrid Tactile-Digital Surfaces |
    2. 6.2 Aftermarket Retrofit in Commercial Fleets |
    3. 6.3 Emerging-Market Localized Cockpits |
    4. 6.4 Feature-on-Demand Monetization |
    5. 6.5 Sustainable and Recyclable Panel Materials |
    6. 6.6 Industry Value Chain Analysis |
    7. 6.7 Porter's Five Forces Analysis
  7. 7 Regional Analysis |
    1. 7.1 North America | |
      1. 7.1.1 United States | |
      2. 7.1.2 Canada | |
      3. 7.1.3 Mexico |
    2. 7.2 Europe | |
      1. 7.2.1 Germany | |
      2. 7.2.2 United Kingdom | |
      3. 7.2.3 France | |
      4. 7.2.4 Italy | |
      5. 7.2.5 Spain | |
      6. 7.2.6 Nordic Countries | |
      7. 7.2.7 Russia | |
      8. 7.2.8 Rest of Europe |
    3. 7.3 Asia-Pacific | |
      1. 7.3.1 China | |
      2. 7.3.2 India | |
      3. 7.3.3 Japan | |
      4. 7.3.4 South Korea | |
      5. 7.3.5 ASEAN | |
      6. 7.3.6 Rest of Asia-Pacific |
    4. 7.4 South America | |
      1. 7.4.1 Brazil | |
      2. 7.4.2 Argentina | |
      3. 7.4.3 Rest of South America |
    5. 7.5 Middle East & Africa | |
      1. 7.5.1 Saudi Arabia | |
      2. 7.5.2 UAE | |
      3. 7.5.3 South Africa | |
      4. 7.5.4 Egypt | |
      5. 7.5.5 Rest of Middle East & Africa
  8. 8 Future Outlook (2026–2035) |
    1. 8.1 Generative Interfaces and In-Cabin AI |
    2. 8.2 Platform Economics and Supplier Consolidation |
    3. 8.3 The Electrification Supercycle |
    4. 8.4 Circularity and Interior Emissions Reporting
  9. 9 Segmentation Analysis |
    1. 9.1 By Component | |
      1. 9.1.1 Rotary Switches | |
      2. 9.1.2 Push Buttons | |
      3. 9.1.3 Touchscreen Modules | |
      4. 9.1.4 Haptic-Feedback Actuators | |
      5. 9.1.5 Switch Panels & Bezels | |
      6. 9.1.6 Others |
    2. 9.2 By Technology | |
      1. 9.2.1 Analog Control Panel | |
      2. 9.2.2 Digital Control Panel | |
      3. 9.2.3 Capacitive-Touch Panel | |
      4. 9.2.4 Hybrid Analog-Digital Panel | |
      5. 9.2.5 Force-Sensing Panel |
    3. 9.3 By Application | |
      1. 9.3.1 Infotainment | |
      2. 9.3.2 Climate Control | |
      3. 9.3.3 Driver Assistance | |
      4. 9.3.4 Lighting & Body Control | |
      5. 9.3.5 Others | |
      6. 9.3.6 Navigation |
    4. 9.4 By Vehicle Type | |
      1. 9.4.1 Passenger Cars | |
      2. 9.4.2 Light Commercial Vehicles | |
      3. 9.4.3 Heavy Commercial Vehicles | |
      4. 9.4.4 Buses & Coaches |
    5. 9.5 By Distribution Channel | |
      1. 9.5.1 OEM | |
      2. 9.5.2 Aftermarket
  10. 10 Competitive Landscape |
    1. 10.1 Market Share Analysis (2026) |
    2. 10.2 Competitive Benchmarking Matrix |
    3. 10.3 Company Profiles | |
      1. 10.3.1 Continental AG (Aumovio) | |
      2. 10.3.2 Robert Bosch GmbH | |
      3. 10.3.3 Panasonic Automotive Systems | |
      4. 10.3.4 Visteon Corporation | |
      5. 10.3.5 DENSO Corporation | |
      6. 10.3.6 Hyundai Mobis | |
      7. 10.3.7 Marelli Holdings | |
      8. 10.3.8 Valeo SA | |
      9. 10.3.9 LG Electronics (Vehicle Solutions) | |
      10. 10.3.10 Harman International | |
      11. 10.3.11 Alps Alpine | |
      12. 10.3.12 Yanfeng
  11. 11 Recent Developments & News
  12. 12 Report Scope & Methodology |
    1. 12.1 Study Period & Base Year |
    2. 12.2 Data Sources & Citations |
    3. 12.3 Abbreviations
  13. 13 Detailed Sources and Citations
  14. 14 Frequently Asked Questions (FAQs)
  15. 15 LIST OF TABLES |
  16. TABLE 1 Global Automotive Control Panel Market Size & Forecast, by Revenue (USD Billion), 2021–2035 |
  17. TABLE 2 Global Automotive Control Panel Market – Year-over-Year Growth Analysis, 2021–2035 |
  18. TABLE 3 Driver Impact Analysis Matrix, 2026–2035 |
  19. TABLE 4 Restraint Impact Analysis Matrix, 2026–2035 |
  20. TABLE 5 Global Market Size, by Component, 2021–2035 (USD Billion) |
  21. TABLE 6 Global Market Size, by Technology, 2021–2035 (USD Billion) |
  22. TABLE 7 Global Market Size, by Application, 2021–2035 (USD Billion) |
  23. TABLE 8 Global Market Size, by Vehicle Type, 2021–2035 (USD Billion) |
  24. TABLE 9 Global Market Size, by Distribution Channel, 2021–2035 (USD Billion) |
  25. TABLE 10 Global Market Size, by Region, 2021–2035 (USD Billion) |
  26. TABLE 11 Regional Summary – Share, Value and Investment Themes, 2025 |
  27. TABLE 12 North America Market Size, by Country, 2021–2035 (USD Billion) |
  28. TABLE 13 Europe Market Size, by Country, 2021–2035 (USD Billion) |
  29. TABLE 14 Asia-Pacific Market Size, by Country, 2021–2035 (USD Billion) |
  30. TABLE 15 South America Market Size, by Country, 2021–2035 (USD Billion) |
  31. TABLE 16 Middle East & Africa Market Size, by Country, 2021–2035 (USD Billion) |
  32. TABLE 17 North America Market Size, by Component, 2021–2035 (USD Billion) |
  33. TABLE 18 North America Market Size, by Technology, 2021–2035 (USD Billion) |
  34. TABLE 19 North America Market Size, by Application, 2021–2035 (USD Billion) |
  35. TABLE 20 North America Market Size, by Vehicle Type, 2021–2035 (USD Billion) |
  36. TABLE 21 North America Market Size, by Distribution Channel, 2021–2035 (USD Billion) |
  37. TABLE 22 Europe Market Size, by Component, 2021–2035 (USD Billion) |
  38. TABLE 23 Europe Market Size, by Technology, 2021–2035 (USD Billion) |
  39. TABLE 24 Europe Market Size, by Application, 2021–2035 (USD Billion) |
  40. TABLE 25 Europe Market Size, by Vehicle Type, 2021–2035 (USD Billion) |
  41. TABLE 26 Europe Market Size, by Distribution Channel, 2021–2035 (USD Billion) |
  42. TABLE 27 Asia-Pacific Market Size, by Component, 2021–2035 (USD Billion) |
  43. TABLE 28 Asia-Pacific Market Size, by Technology, 2021–2035 (USD Billion) |
  44. TABLE 29 Asia-Pacific Market Size, by Application, 2021–2035 (USD Billion) |
  45. TABLE 30 Asia-Pacific Market Size, by Vehicle Type, 2021–2035 (USD Billion) |
  46. TABLE 31 Asia-Pacific Market Size, by Distribution Channel, 2021–2035 (USD Billion) |
  47. TABLE 32 South America Market Size, by Component, 2021–2035 (USD Billion) |
  48. TABLE 33 South America Market Size, by Technology, 2021–2035 (USD Billion) |
  49. TABLE 34 South America Market Size, by Application, 2021–2035 (USD Billion) |
  50. TABLE 35 South America Market Size, by Vehicle Type, 2021–2035 (USD Billion) |
  51. TABLE 36 Middle East & Africa Market Size, by Component, 2021–2035 (USD Billion) |
  52. TABLE 37 Middle East & Africa Market Size, by Technology, 2021–2035 (USD Billion) |
  53. TABLE 38 Middle East & Africa Market Size, by Application, 2021–2035 (USD Billion) |
  54. TABLE 39 Middle East & Africa Market Size, by Vehicle Type, 2021–2035 (USD Billion) |
  55. TABLE 40 United States Market Size, by Component, 2021–2035 (USD Billion) |
  56. TABLE 41 China Market Size, by Component, 2021–2035 (USD Billion) |
  57. TABLE 42 Germany Market Size, by Component, 2021–2035 (USD Billion) |
  58. TABLE 43 India Market Size, by Technology, 2021–2035 (USD Billion) |
  59. TABLE 44 Japan Market Size, by Application, 2021–2035 (USD Billion) |
  60. TABLE 45 Competitive Benchmarking Matrix, 2026 |
  61. TABLE 46 Company Profiles – Key Players |
  62. TABLE 47 Recent Developments & Strategic Announcements, 2023–2025 |
  63. TABLE 48 Report Scope & Methodology Summary |
  64. TABLE 49 Detailed Sources and Citations
  65. 16 LIST OF FIGURES |
  66. FIGURE 1 Market Dynamics – Drivers, Restraints, Opportunities and Challenges |
  67. FIGURE 2 Industry Value Chain Analysis |
  68. FIGURE 3 Porter's Five Forces Analysis |
  69. FIGURE 4 Global Market Size Trend and Forecast, 2021–2035 (USD Billion) |
  70. FIGURE 5 Year-over-Year Growth Rate Trend, 2022–2035 (%) |
  71. FIGURE 6 Market Share by Component, 2025 vs 2035 (%) |
  72. FIGURE 7 Market Share by Technology, 2025 vs 2035 (%) |
  73. FIGURE 8 Market Share by Application, 2025 vs 2035 (%) |
  74. FIGURE 9 Market Share by Vehicle Type, 2025 (%) |
  75. FIGURE 10 Market Share by Distribution Channel, 2025 vs 2035 (%) |
  76. FIGURE 11 Regional Market Share Distribution, 2025 (%) |
  77. FIGURE 12 Regional Market Share Distribution, 2035 (%) |
  78. FIGURE 13 Regional CAGR Comparison, 2026–2035 (%) |
  79. FIGURE 14 North America Country-Level Share, 2025 (%) |
  80. FIGURE 15 Europe Country-Level Share, 2025 (%) |
  81. FIGURE 16 Asia-Pacific Country-Level Share, 2025 (%) |
  82. FIGURE 17 Competitive Landscape – Estimated Revenue Share Distribution, 2026 |
  83. FIGURE 18 Competitive Positioning Matrix – Capability vs Scale |
  84. FIGURE 19 Driver Impact Contribution Ranking |
  85. FIGURE 20 Restraint Severity Ranking |
  86. FIGURE 21 Content-per-Vehicle Trend by Vehicle Segment, 2021–2035 (USD) |
  87. FIGURE 22 Technology Adoption S-Curve – Analog to Hybrid to Digital

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
By ComponentRotary Switches, Push Buttons, Touchscreen Modules, Haptic-Feedback Actuators, Switch Panels & Bezels, OthersTouchscreen ModulesHaptic-Feedback Actuators
By TechnologyAnalog Control Panel, Digital Control Panel, Capacitive-Touch Panel, Hybrid Analog-Digital PanelDigital Control PanelCapacitive-Touch Panel
By ApplicationInfotainment, Climate Control, Driver Assistance, Lighting & Body Control, OthersInfotainmentDriver Assistance
By Vehicle TypePassenger Cars, Light Commercial Vehicles, Heavy Commercial Vehicles, Buses & CoachesPassenger CarsBuses & Coaches
By Distribution ChannelOEM, AftermarketOEMAftermarket
By RegionNorth America, Europe, Asia-Pacific, South America, Middle East & AfricaAsia-PacificAsia-Pacific


Market Segmentation Overview

By Component

Sub-SegmentKey Trend
Rotary SwitchesReinstated for climate and volume control after ergonomic backlash against touch sliders
Push ButtonsProtected by safety rating criteria requiring physical operation of core functions
Touchscreen ModulesMigration to curved and pillar-to-pillar formats in premium and mid-tier platforms
Haptic-Feedback ActuatorsPiezoelectric and electromagnetic actuators moving from premium showcase to mainstream fitment
Switch Panels & BezelsMaterial differentiation through anodized metal, textured polymer, and ambient backlighting
OthersProximity sensing and gesture layers supplementing primary touch surfaces


Component strategy now hinges on a single question: which functions deserve a dedicated physical control and which can share a screen. Suppliers who answer that well win platform awards; those who simply enlarge displays are competing on a commoditizing axis.

By Technology

Sub-SegmentKey Trend
Analog Control PanelPersisting in entry hatchbacks, commercial vans and heavy trucks where cost governs
Digital Control PanelStandard across C-segment and above; reconfigurability enables over-the-air feature delivery
Capacitive-Touch PanelController silicon cost decline extending capacitive surfaces to rear zones and door panels
Hybrid Analog-Digital PanelEmerging consensus architecture pairing large displays with hardware controls for core functions


Hybrid architectures are the quiet winner of the current cycle. They satisfy safety assessors, address customer complaints about menu depth, and preserve the visual impact that showroom differentiation still demands.

By Application

Sub-SegmentKey Trend
InfotainmentSmartphone projection and connected services driving screen diagonal escalation
  
Climate ControlMulti-zone HVAC and electric-vehicle thermal preconditioning expanding control complexity
Driver AssistanceRegulatory indication requirements converting directly into dedicated interface content
Lighting & Body ControlAdaptive matrix lighting and keyless access adding secondary control surfaces
OthersSeat, mirror and comfort adjustment consolidating into shared menus


Application mix reveals where regulation and consumer preference diverge. Infotainment grows on desire; driver assistance grows on compliance, and compliance-driven demand is the more predictable of the two.

By Vehicle Type

Sub-SegmentKey Trend
Passenger CarsFeature competition among electric-native brands compressing refresh cycles to under 24 months
Light Commercial VehiclesLast-mile delivery operators specifying telematics-integrated driver interfaces
Heavy Commercial VehiclesCabin comfort investment used as a driver recruitment and retention tool
Buses & CoachesPassenger information systems and safety indication driving fastest segment growth


Commercial segments were once an afterthought in cockpit electronics. Fleet total-cost-of-ownership models now credit interface quality with measurable driver retention benefits, which has changed procurement behaviour.

By Distribution Channel

Sub-SegmentKey Trend
OEMFactory integration deepening as panels bind to cockpit domain controllers and vehicle security architecture
AftermarketRetrofit displays and fleet telematics upgrades expanding faster than factory fitment


Aftermarket growth is constrained less by demand than by architecture. As vehicles adopt secured gateways and signed firmware, only suppliers with OEM-sanctioned interfaces will be able to serve the retrofit opportunity at scale.




Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.