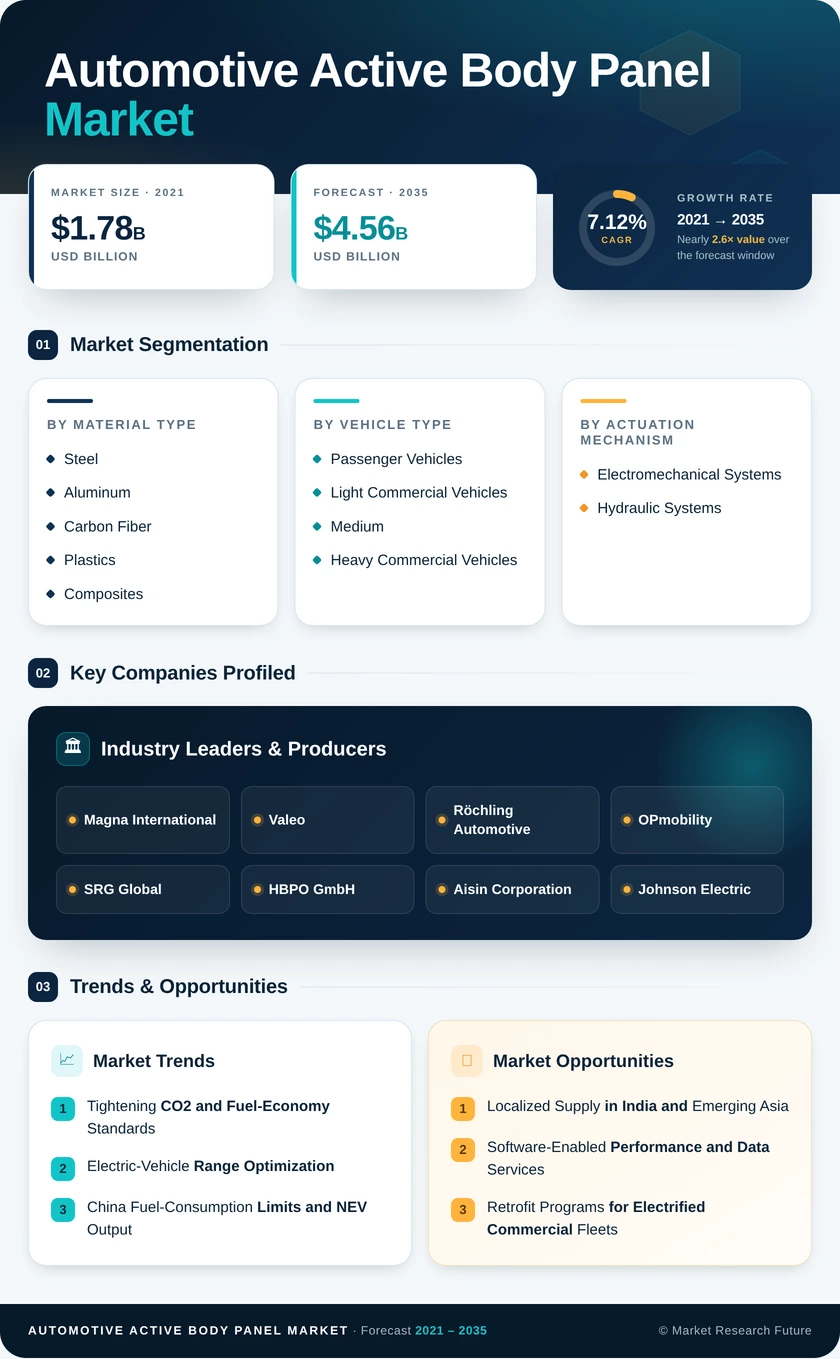
Automotive Active Body Panel Market (2026 - 2035)

ID: MRFR/AT/4792-HCR 100 Pages Triveni Bhoyar Last Updated: September 22, 2026
Automotive Active Body Panel Market Research Report By Material Type (Steel, Aluminum, Carbon Fiber, Plastics and Composites), By Vehicle Type (Passenger Vehicles, Light Commercial Vehicles, Medium and Heavy Commercial Vehicles), By Actuation Mechanism (Electromechanical Systems, Hydraulic Systems), By End User (OEMs, Aftermarket Suppliers) - Forecast to 2035
Automotive Active Body Panel Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)7.12%
2025 Market SizeUSD 2.29 Billion
2035 Market SizeUSD 4.56 Billion
Key Players
Magna International
Valeo
Röchling Automotive
OPmobility
SRG Global
HBPO GmbH
Opportunities
  • Localized Supply in India and Emerging Asia
  • Software-Enabled Performance and Data Services
  • Retrofit Programs for Electrified Commercial Fleets
  1. 1 Market Summary | |
  2. 2 Key Report Takeaways | |
    1. 2.1 By Material Type | |
    2. 2.2 By Vehicle Type | |
    3. 2.3 By Actuation Mechanism | |
    4. 2.4 By End User | |
    5. 2.5 By Region | |
  3. 3 Market Size and Forecast (2021–2035) | |
  4. 4 Driver Impact Analysis | |
    1. 4.1 Tightening CO2 and Fuel-Economy Standards | |
    2. 4.2 Electric-Vehicle Range Optimization | |
    3. 4.3 China Fuel-Consumption Limits and NEV Output | |
    4. 4.4 Powertrain and Battery Thermal-Management Demand | |
    5. 4.5 48 V Architectures Enabling Compact Actuation | |
    6. 4.6 Heavy-Duty Freight-Efficiency Programs | |
  5. 5 Restraints Impact Analysis | |
    1. 5.1 High System Cost and Added Mass | |
    2. 5.2 US Fuel-Economy Enforcement Rollback | |
    3. 5.3 Cybersecurity and Functional-Safety Compliance Burden | |
    4. 5.4 Durability Risk From Ice, Debris and Contamination | |
    5. 5.5 Material Cost Volatility and Carbon-Border Charges | |
  6. 6 Opportunities | |
    1. 6.1 Localized Supply in India and Emerging Asia | |
    2. 6.2 Software-Enabled Performance and Data Services | |
    3. 6.3 Retrofit Programs for Electrified Commercial Fleets | |
    4. 6.4 Circular Materials for Panel Skins and Housings | |
  7. 7 Regional Market Share and Country-Level Analysis | |
    1. 7.1 North America | | |
      1. 7.1.1 US | | |
      2. 7.1.2 Canada | | |
      3. 7.1.3 Mexico | |
    2. 7.2 Europe | | |
      1. 7.2.1 Germany | | |
      2. 7.2.2 UK | | |
      3. 7.2.3 France | | |
      4. 7.2.4 Italy | | |
      5. 7.2.5 Spain | | |
      6. 7.2.6 Nordic Countries | | |
      7. 7.2.7 Russia | | |
      8. 7.2.8 Rest of Europe | |
    3. 7.3 Asia-Pacific | | |
      1. 7.3.1 China | | |
      2. 7.3.2 India | | |
      3. 7.3.3 Japan | | |
      4. 7.3.4 South Korea | | |
      5. 7.3.5 ASEAN | | |
      6. 7.3.6 Rest of Asia-Pacific | |
    4. 7.4 South America | | |
      1. 7.4.1 Brazil | | |
      2. 7.4.2 Argentina | | |
      3. 7.4.3 Rest of South America | |
    5. 7.5 Middle East & Africa | | |
      1. 7.5.1 Saudi Arabia | | |
      2. 7.5.2 UAE | | |
      3. 7.5.3 South Africa | | |
      4. 7.5.4 Egypt | | |
      5. 7.5.5 Rest of MEA | |
  8. 8 Future Outlook (2026–2035) | |
    1. 8.1 Predictive Control and Software-Defined Deployment | |
    2. 8.2 The Electrification Supercycle | |
    3. 8.3 Automated Driving and Integrated Exterior Systems | |
    4. 8.4 Sustainability Reporting and Product Carbon Footprints | |
  9. 9 Segmentation Analysis | |
    1. 9.1 By Material Type | | |
      1. 9.1.1 Steel | | |
      2. 9.1.2 Aluminum | | |
      3. 9.1.3 Carbon Fiber | | |
      4. 9.1.4 Plastics and Composites | |
    2. 9.2 By Vehicle Type | | |
      1. 9.2.1 Passenger Vehicles | | |
      2. 9.2.2 Light Commercial Vehicles | | |
      3. 9.2.3 Medium and Heavy Commercial Vehicles | |
    3. 9.3 By Actuation Mechanism | | |
      1. 9.3.1 Electromechanical Systems | | |
      2. 9.3.2 Hydraulic Systems | |
    4. 9.4 By End User | | |
      1. 9.4.1 OEMs | | |
      2. 9.4.2 Aftermarket Suppliers | |
  10. 10 Competitive Landscape | |
  11. 11 Recent News & Developments | |
  12. 12 Report Scope and Methodology | |
  13. 13 Detailed Sources and Citations | |
  14. 14 Frequently Asked Questions (FAQs) | | LIST OF TABLES | |
  15. TABLE 1 Global Market Snapshot, 2025–2035 | |
  16. TABLE 2 Global Market Size & Forecast, by Revenue (USD Billion), 2021–2035 | |
  17. TABLE 3 Driver Impact Analysis, 2026–2035 | |
  18. TABLE 4 Restraints Impact Analysis, 2026–2035 | |
  19. TABLE 5 Regional Summary, 2025 | |
  20. TABLE 6 North America Country-Level Analysis | |
  21. TABLE 7 Europe Country-Level Analysis | |
  22. TABLE 8 Asia-Pacific Country-Level Analysis | |
  23. TABLE 9 South America Country-Level Analysis | |
  24. TABLE 10 Middle East & Africa Country-Level Analysis | |
  25. TABLE 11 Market Segmentation, by Material Type | |
  26. TABLE 12 Market Segmentation, by Vehicle Type | |
  27. TABLE 13 Market Segmentation, by Actuation Mechanism | |
  28. TABLE 14 Market Segmentation, by End User | |
  29. TABLE 15 Competitive Benchmarking Matrix | |
  30. TABLE 16 Report Scope and Methodology | |
  31. TABLE 17 Detailed Sources and Citations | | LIST OF FIGURES | |
  32. FIGURE 1 Market Dynamics Overview (Drivers, Restraints, Opportunities) | |
  33. FIGURE 2 Industry Value Chain Analysis | |
  34. FIGURE 3 Porter's Five Forces Analysis | |
  35. FIGURE 4 Global Market Size Trend, 2021–2035 (USD Billion) | |
  36. FIGURE 5 Market Share, by Material Type, 2025 | |
  37. FIGURE 6 Market Share, by Vehicle Type, 2025 | |
  38. FIGURE 7 Market Share, by Actuation Mechanism, 2025 | |
  39. FIGURE 8 Market Share, by End User, 2025 | |
  40. FIGURE 9 Regional Market Share, 2025 | |
  41. FIGURE 10 Country-Level Share Within Asia-Pacific, 2025 | |
  42. FIGURE 11 Competitive Positioning Matrix | |
  43. FIGURE 12 Estimated Revenue Share Ranges, Key Players

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
By Material TypeSteel, Aluminum, Carbon Fiber, Plastics and CompositesAluminum (39.2% share)Carbon Fiber (7.15% CAGR)
By Vehicle TypePassenger Vehicles, Light Commercial Vehicles, Medium and Heavy Commercial VehiclesPassenger Vehicles (70.9% share)Light Commercial Vehicles (7.6% CAGR)
By Actuation MechanismElectromechanical Systems, Hydraulic SystemsElectromechanical Systems (85.7% share)Electromechanical Systems (85.7% share)
By End UserOEMs, Aftermarket SuppliersOEMs (82.6% share)Aftermarket Suppliers (7.8% CAGR)
By RegionNorth America, Europe, Asia-Pacific, South America, Middle East & AfricaAsia-Pacific (42.6% share (2025))Asia-Pacific (42.6% share (2025))


Market Segmentation Overview

By Material Type

Sub-SegmentKey Trend
SteelRetained for hinge mounts and localized reinforcement
AluminumDefault skin material on volume electric platforms
Carbon FiberFast-cycle forming narrows the cost gap on premium models.
Plastics and CompositesRecycled thermoplastics gain share in shutter vanes.


Aluminum leads because its cost-to-weight ratio suits high-volume electric crossovers that are stamped on existing lines. Carbon Fiber grows fastest as premium OEMs accept higher part costs to offset battery mass, helped by shorter cure cycles. Plastics and Composites benefit from recycled-content proposals, while Steel stays confined to load-bearing brackets.

By Vehicle Type

Sub-SegmentKey Trend
Passenger VehiclesMulti-panel systems spread from flagships to mid-segment EVs
Light Commercial VehiclesElectric vans adopt shutters and roof fairings for range.
Medium and Heavy Commercial VehiclesDeployable fairings and skirts follow SuperTruck findings.


Passenger Vehicles dominate because electrified crossovers and sedans rely on rated range to compete, and active spoilers and shutters recover that range cheaply. Light Commercial Vehicles grow fastest as last-mile fleets electrify and need every kilometre between charges. Medium and Heavy Commercial Vehicles adopt more slowly because of long development and validation cycles.

By Actuation Mechanism

Sub-SegmentKey Trend
Electromechanical SystemsBrushless actuators on 48 V networks enable faster, multi-axis motion
Hydraulic SystemsRetained for high-force heavy-duty panels


Electromechanical Systems both lead and grow faster, because compact gearset actuators connect directly to 48 V architectures and need no fluid lines. Hydraulic Systems persist only where panels demand high force across extreme temperatures, mainly on heavy commercial vehicles. Continued gains in actuator power density will keep widening the gap between the two.

By End User

Sub-SegmentKey Trend
OEMsPanels sourced as part of full front-end modules
Aftermarket SuppliersRetrofit kits target electrified commercial fleets.


OEMs dominate because active panels must be engineered together with body structure, cooling and vehicle electronics, and they are sourced years before launch. Aftermarket Suppliers grow fastest as fleets retrofit shutters and fairings to extend electric-van range. Cybersecurity certification and sealed diagnostics keep safety-critical functions with OEMs.




Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.