Automatic High Beam Control Market (2026 - 2035)

ID: MRFR/AT/6851-HCR 100 Pages Triveni Bhoyar Last Updated: September 15, 2026
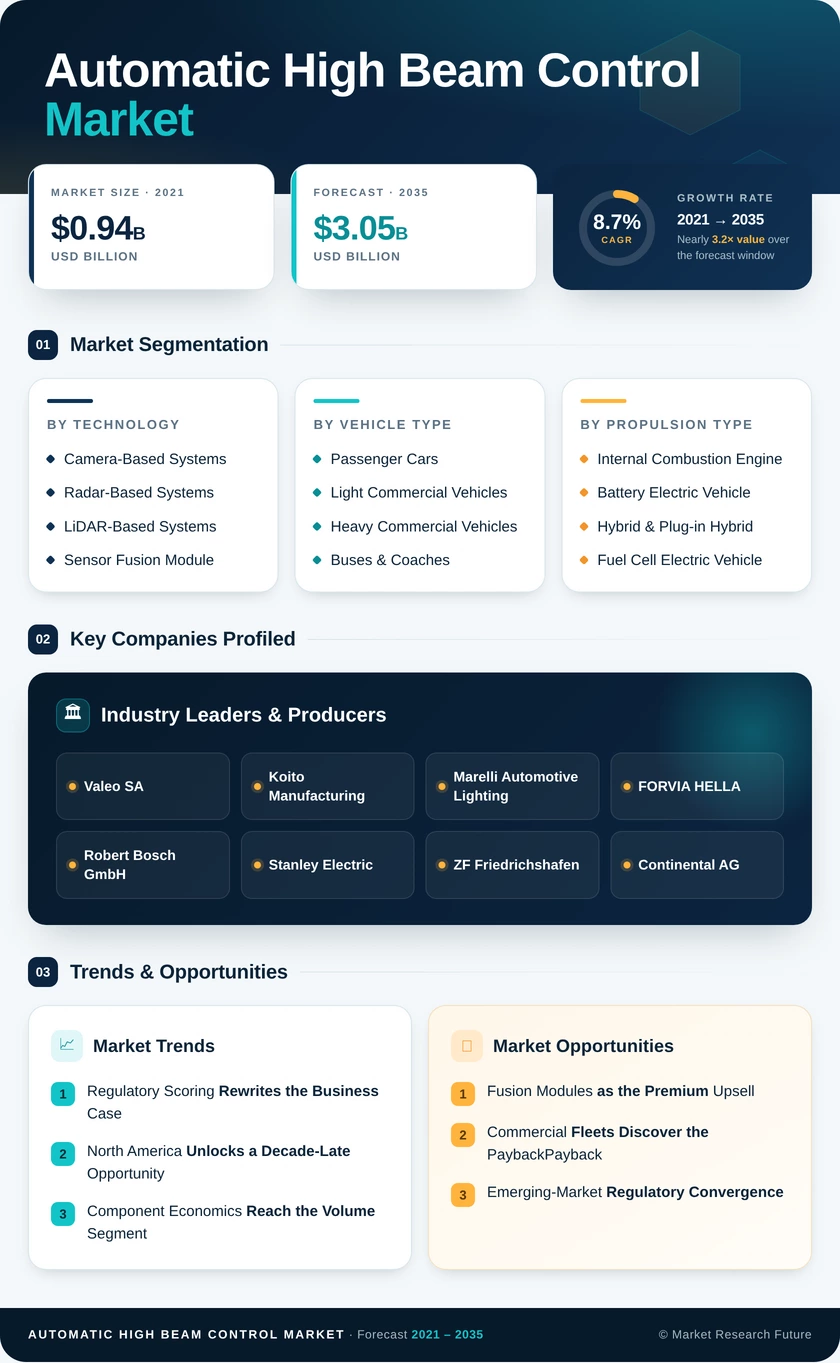
Automatic High Beam Control Market Research Report By Technology (Camera-Based Systems, Radar-Based Systems, LiDAR-Based Systems, Sensor Fusion Module), By Vehicle Type (Passenger Cars, Light Commercial Vehicles, Heavy Commercial Vehicles, Buses & Coaches), By Propulsion Type (Internal Combustion Engine, Battery Electric Vehicle, Hybrid & Plug-in Hybrid, Fuel Cell Electric Vehicle), By Distribution Channel (OEM, Aftermarket) and By Regional (North America, Europe, South America, Asia Pacific, Middle East and Africa) - Forecast to 2035
Automatic High Beam Control Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)8.7%
2025 Market SizeUSD 1.33 Billion
2035 Market SizeUSD 3.05 Billion
Key Players
Valeo SA
Koito Manufacturing
Marelli Automotive Lighting
FORVIA HELLA
Robert Bosch GmbH
Stanley Electric
Opportunities
  • Fusion Modules as the Premium Upsell
  • Commercial Fleets Discover Payback
  • Emerging-Market Regulatory Convergence
  1. 1 Market Summary |
    1. 1.1 Study Assumptions & Market Definition |
    2. 1.2 Scope of the Study |
    3. 1.3 Research Methodology
  2. 2 Key Report Takeaways |
    1. 2.1 By Technology |
    2. 2.2 By Sector |
    3. 2.3 By Geography
  3. 3 Market Size and Forecast (2021–2035) |
    1. 3.1 Historical Market Size (2021–2025) |
    2. 3.2 Current & Forecast Market Size (2026–2035) |
    3. 3.3 Year-over-Year Growth Analysis
  4. 4 Driver Impact Analysis |
    1. 4.1 Regulatory Scoring Rewrites the Business Case |
    2. 4.2 North America Unlocks a Decade-Late Opportunity |
    3. 4.3 Component Economics Reach the Volume Segment |
    4. 4.4 Electrification Reshapes the Specification
  5. 5 Restraints Impact Analysis |
    1. 5.1 Entry-Segment Cost Sensitivity |
    2. 5.2 Homologation Fragmentation |
    3. 5.3 Adverse-Weather Sensing Limitations
  6. 6 Opportunities |
    1. 6.1 Fusion Modules as the Premium Upsell |
    2. 6.2 Commercial Fleet Retrofit Economics |
    3. 6.3 Emerging-Market Regulatory Convergence |
    4. 6.4 Beam Data as a Recurring Revenue Stream |
    5. 6.5 Software-Defined Vehicle Integration
  7. 7 Regional Market Share and Country-Level Analysis |
    1. 7.1 North America | |
      1. 7.1.1 US | |
      2. 7.1.2 Canada | |
      3. 7.1.3 Mexico |
    2. 7.2 Europe | |
      1. 7.2.1 Germany | |
      2. 7.2.2 UK | |
      3. 7.2.3 France | |
      4. 7.2.4 Italy | |
      5. 7.2.5 Spain | |
      6. 7.2.6 Nordic Countries | |
      7. 7.2.7 Russia | |
      8. 7.2.8 Rest of Europe |
    3. 7.3 Asia-Pacific | |
      1. 7.3.1 China | |
      2. 7.3.2 India | |
      3. 7.3.3 Japan | |
      4. 7.3.4 South Korea | |
      5. 7.3.5 ASEAN | |
      6. 7.3.6 Rest of Asia-Pacific |
    4. 7.4 South America | |
      1. 7.4.1 Brazil | |
      2. 7.4.2 Argentina | |
      3. 7.4.3 Rest of South America |
    5. 7.5 Middle East & Africa | |
      1. 7.5.1 Saudi Arabia | |
      2. 7.5.2 UAE | |
      3. 7.5.3 South Africa | |
      4. 7.5.4 Egypt | |
      5. 7.5.5 Rest of Middle East & Africa
  8. 8 Future Outlook (2026–2035) |
    1. 8.1 Perception Stack Consolidation |
    2. 8.2 Predictive Beam Shaping |
    3. 8.3 Electrification Content Premium |
    4. 8.4 Safety Reporting in Fleet Procurement
  9. 9 Market Segmentation Analysis |
    1. 9.1 By Technology | |
      1. 9.1.1 Camera-Based Systems | |
      2. 9.1.2 Radar-Based Systems | |
      3. 9.1.3 LiDAR-Based Systems | |
      4. 9.1.4 Sensor Fusion Module |
    2. 9.2 By Vehicle Type | |
      1. 9.2.1 Passenger Cars | |
      2. 9.2.2 Light Commercial Vehicles | |
      3. 9.2.3 Heavy Commercial Vehicles | |
      4. 9.2.4 Buses & Coaches |
    3. 9.3 By Propulsion Type | |
      1. 9.3.1 Internal Combustion Engine | |
      2. 9.3.2 Battery Electric Vehicle | |
      3. 9.3.3 Hybrid & Plug-in Hybrid | |
      4. 9.3.4 Fuel Cell Electric Vehicle |
    4. 9.4 By Distribution Channel | |
      1. 9.4.1 OEM | |
      2. 9.4.2 Aftermarket
  10. 10 Competitive Landscape |
    1. 10.1 Market Concentration Analysis (2026) |
    2. 10.2 Competitive Benchmarking Matrix |
    3. 10.3 Company Profiles | |
      1. 10.3.1 Valeo SA | |
      2. 10.3.2 Koito Manufacturing | |
      3. 10.3.3 Marelli Automotive Lighting | |
      4. 10.3.4 FORVIA HELLA | |
      5. 10.3.5 Robert Bosch GmbH | |
      6. 10.3.6 Stanley Electric | |
      7. 10.3.7 ZF Friedrichshafen | |
      8. 10.3.8 Continental AG | |
      9. 10.3.9 DENSO Corporation | |
      10. 10.3.10 Aptiv PLC | |
      11. 10.3.11 Hyundai Mobis | |
      12. 10.3.12 Varroc Lighting Systems
  11. 11 Recent News & Developments
  12. 12 Report Scope and Methodology |
    1. 12.1 Study Period & Base Year |
    2. 12.2 Data Sources & Citations |
    3. 12.3 Abbreviations
  13. 13 Detailed Sources and Citations
  14. 14 Frequently Asked Questions
  15. 15 LIST OF TABLES |
  16. TABLE 1 Automatic High Beam Control Market Size & Forecast, by Revenue (USD Billion), 2021–2035 |
  17. TABLE 2 Automatic High Beam Control Market — Year-over-Year Growth Analysis, 2021–2035 |
  18. TABLE 3 Driver Impact Analysis Matrix, 2026–2035 |
  19. TABLE 4 Restraint Impact Analysis Matrix, 2026–2035 |
  20. TABLE 5 Market Size, by Technology, 2021–2035 (USD Billion) |
  21. TABLE 6 Market Size, by Vehicle Type, 2021–2035 (USD Billion) |
  22. TABLE 7 Market Size, by Propulsion Type, 2021–2035 (USD Billion) |
  23. TABLE 8 Market Size, by Distribution Channel, 2021–2035 (USD Billion) |
  24. TABLE 9 Market Size, by Region, 2021–2035 (USD Billion) |
  25. TABLE 10 North America Market Size, by Country, 2021–2035 (USD Billion) |
  26. TABLE 11 Europe Market Size, by Country, 2021–2035 (USD Billion) |
  27. TABLE 12 Asia-Pacific Market Size, by Country, 2021–2035 (USD Billion) |
  28. TABLE 13 South America Market Size, by Country, 2021–2035 (USD Billion) |
  29. TABLE 14 Middle East & Africa Market Size, by Country, 2021–2035 (USD Billion) |
  30. TABLE 15 North America Market Size, by Technology, 2021–2035 (USD Billion) |
  31. TABLE 16 Europe Market Size, by Technology, 2021–2035 (USD Billion) |
  32. TABLE 17 Asia-Pacific Market Size, by Technology, 2021–2035 (USD Billion) |
  33. TABLE 18 North America Market Size, by Vehicle Type, 2021–2035 (USD Billion) |
  34. TABLE 19 Europe Market Size, by Vehicle Type, 2021–2035 (USD Billion) |
  35. TABLE 20 Asia-Pacific Market Size, by Propulsion Type, 2021–2035 (USD Billion) |
  36. TABLE 21 Competitive Benchmarking Matrix, 2026 |
  37. TABLE 22 Company Profiles — Key Players |
  38. TABLE 23 Recent Developments & Strategic Announcements, 2023–2025 |
  39. TABLE 24 Report Scope & Methodology Summary |
  40. TABLE 25 Detailed Sources and Citations
  41. 16 LIST OF FIGURES |
  42. FIGURE 1 Market Dynamics — Drivers, Restraints, and Opportunities Framework |
  43. FIGURE 2 Industry Value Chain Analysis |
  44. FIGURE 3 Porter's Five Forces Analysis |
  45. FIGURE 4 Market Size Trend and Forecast Curve, 2021–2035 (USD Billion) |
  46. FIGURE 5 Year-over-Year Growth Trajectory, 2022–2035 (%) |
  47. FIGURE 6 Segment Share by Technology, 2025 vs 2035 (%) |
  48. FIGURE 7 Segment Share by Vehicle Type, 2025 vs 2035 (%) |
  49. FIGURE 8 Segment Share by Propulsion Type, 2025 vs 2035 (%) |
  50. FIGURE 9 Distribution Channel Split, 2025 vs 2035 (%) |
  51. FIGURE 10 Regional Revenue Share, 2025 (%) |
  52. FIGURE 11 Regional CAGR Comparison, 2026–2035 (%) |
  53. FIGURE 12 Country-Level Heat Map — Fitment Penetration, 2025 |
  54. FIGURE 13 Competitive Landscape — Revenue Share Ranges, 2026 |
  55. FIGURE 14 Supplier Positioning Matrix — Optics Depth vs Software Depth |
  56. FIGURE 15 Per-Vehicle Content Cost Curve, 2021–2035 (USD)

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
By TechnologyCamera-Based Systems; Radar-Based Systems; LiDAR-Based Systems; Sensor Fusion ModuleCamera-Based SystemsSensor Fusion Module
By Vehicle TypePassenger Cars; Light Commercial Vehicles; Heavy Commercial Vehicles; Buses & CoachesPassenger CarsPassenger Cars
By Propulsion TypeInternal Combustion Engine; Battery Electric Vehicle; Hybrid & Plug-in Hybrid; Fuel Cell Electric VehicleInternal Combustion EngineBattery Electric Vehicle
By Distribution ChannelOEM; AftermarketOEMAftermarket
By GeographyNorth America; Europe; Asia-Pacific; South America; Middle East & AfricaAsia-PacificMiddle East & Africa


Market Segmentation Overview

By Technology

Sub-SegmentKey Trend
Camera-Based SystemsCost advantage from shared ADAS sensor reuse keeps this the default architecture
Radar-Based SystemsPositioned as a weather-robustness supplement rather than a standalone solution
LiDAR-Based SystemsConfined to Level 3 programs where the sensor is already specified
Sensor Fusion ModuleFastest expansion as suppliers target false-hold elimination and premium pricing


Technology choice is being decided by bill-of-materials logic rather than pure performance. Cameras win volume because they are already present; fusion wins growth because it fixes the reliability gap owners complain about. Radar and LiDAR remain enabling components inside broader perception packages rather than distinct product lines.

By Vehicle Type

Sub-SegmentKey Trend
Passenger CarsNCAP scoring drives platform-level standardization across new models
Light Commercial VehiclesLast-mile delivery fleets adopt for night-shift safety and premium relief
Heavy Commercial VehiclesLong-haul operators justify fitment through documented crash-rate reduction
Buses & CoachesPublic transit procurement specifications increasingly mandate the function


By Propulsion Type

Sub-SegmentKey Trend
Internal Combustion EngineRetains the largest installed base through the forecast, with slowing attachment growth
Battery Electric VehicleZonal architectures and brand-signature lighting drive the highest growth rate
Hybrid & Plug-in HybridPremium trim positioning sustains above-average attachment
Fuel Cell Electric VehicleLimited to commercial demonstration fleets with high specification levels


Powertrain increasingly predicts whether a vehicle carries advanced beam control. Electric platforms integrate the function more cheaply because the supporting electrical architecture already exists, so attachment rates run well above combustion equivalents even at comparable price points.

By Distribution Channel

Sub-SegmentKey Trend
OEMHomologation and calibration requirements keep factory fitment overwhelmingly dominant.
AftermarketFleet retrofit kits mature as installed-base vehicles reach camera-equipped generations.


Factory installation dominates for a practical reason: beam calibration must be validated against a specific headlamp geometry. Aftermarket growth depends entirely on the installed base aging into camera-equipped model years, which begins in earnest around 2028 for commercial fleets.

By Geography

Sub-SegmentKey Trend
North AmericaPost-FMVSS 108 adoption concentrated in pickups and full-size SUVs
EuropeScored NCAP protocols and deep homologation expertise sustain premium fitment
Asia-PacificElectric-vehicle volume and domestic optics manufacturing anchor regional leadership
South AmericaLatin NCAP alignment lifts fitment from a low base, constrained by currency exposure.
Middle East & AfricaAssembly localization imports European specifications, producing the fastest growth.


Geographic performance correlates almost perfectly with the presence of a scored safety protocol. Where regulators attach points, fitment follows within two model cycles; where they do not, adoption tracks premium-segment mix alone.




Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.