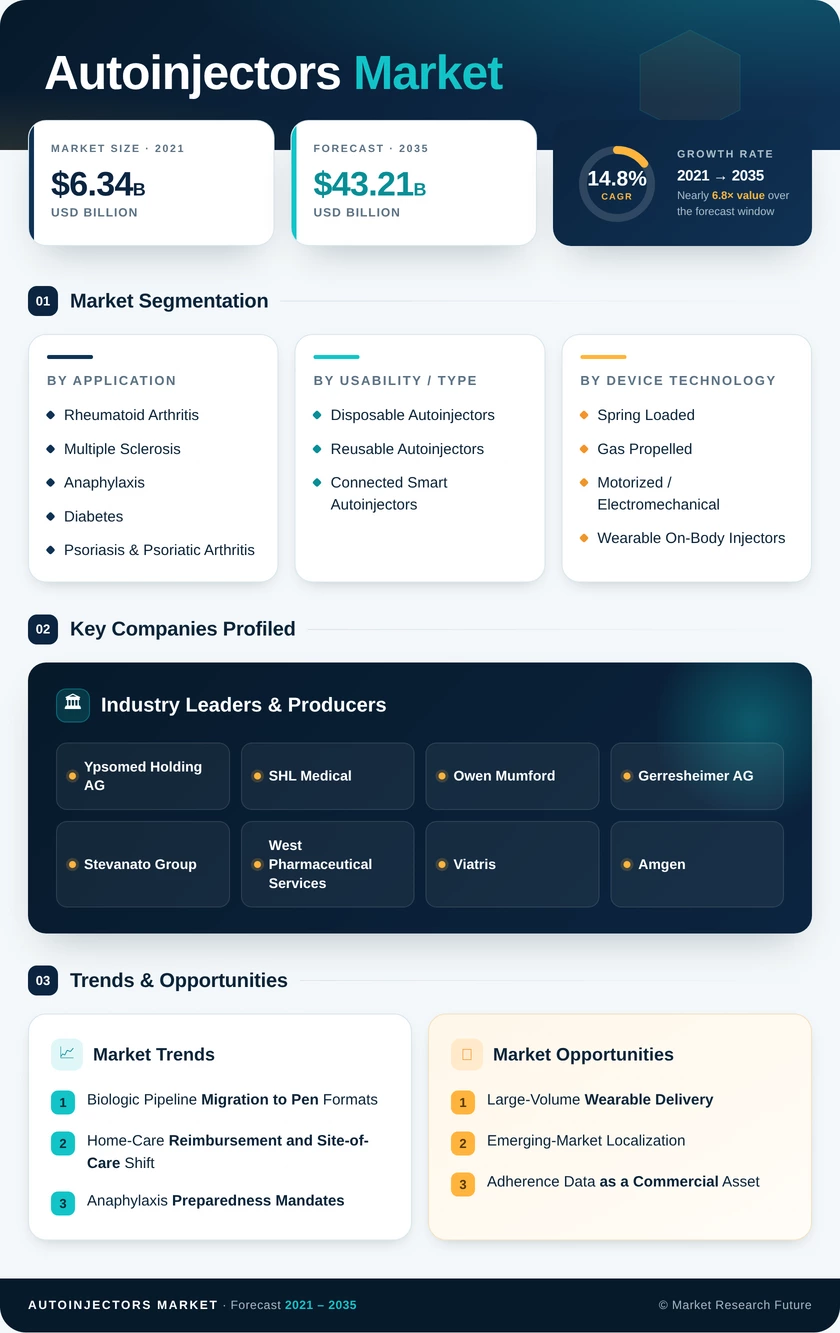
Autoinjectors Market (2026 - 2035)

ID: MRFR/HC/4850-CR 200 Pages Rahul Gotadki Last Updated: September 15, 2026
Autoinjectors Market Research Report: Size, Share, Trend Analysis By Product Type (Pre-filled Autoinjectors, Fillable Autoinjectors, Smart Autoinjectors, Biologics Autoinjectors), By Therapeutic Area (Autoimmune Disorders, Diabetes, Cancer, Anaphylaxis, Multiple Sclerosis), By End-user (Hospitals, Homecare Settings, Ambulatory Surgical Centers, Specialty Clinics), By Material (Plastic, Metal, Glass), and By Regional (North America, Europe, South America, Asia Pacific, Middle East and Africa) - Growth Outlook & Industry Forecast 2025 To 2035
Autoinjectors Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)14.8%
2025 Market SizeUSD 10.80 Billion
2035 Market SizeUSD 43.21 Billion
Key Players
Ypsomed Holding AG
SHL Medical
Owen Mumford
Gerresheimer AG
Stevanato Group
West Pharmaceutical Services
Opportunities
  • Large-Volume Wearable Delivery
  • Emerging-Market Localization
  • Adherence Data as a Commercial Asset
  1. 1 Market Summary |
    1. 1.1 Study Assumptions & Market Definition |
    2. 1.2 Scope of the Study |
    3. 1.3 Research Methodology
  2. 2 Key Report Takeaways |
    1. 2.1 By Technology |
    2. 2.2 By Sector |
    3. 2.3 By Geography
  3. 3 Market Size & Forecast (2021–2035) |
    1. 3.1 Historical Market Size (2021–2025) |
    2. 3.2 Current & Forecast Market Size (2026–2035) |
    3. 3.3 Year-over-Year Growth Analysis
  4. 4 Driver Impact Analysis |
    1. 4.1 Biologic Pipeline Migration to Pen Formats |
    2. 4.2 Home-Care Reimbursement and Site-of-Care Shift |
    3. 4.3 Anaphylaxis Preparedness Mandates |
    4. 4.4 Device Differentiation Under Biosimilar Pressure
  5. 5 Restraints Impact Analysis |
    1. 5.1 Component Concentration Risk |
    2. 5.2 Regulatory Complexity for Combination Products |
    3. 5.3 Cost Premium Versus Prefilled Syringes
  6. 6 Opportunities |
    1. 6.1 Large-Volume Wearable Delivery |
    2. 6.2 Emerging-Market Localization |
    3. 6.3 Adherence Data as a Commercial Asset |
    4. 6.4 Reusable Core Architectures |
    5. 6.5 Emergency and Defense Stockpiling |
    6. 6.6 Industry Value Chain Analysis |
    7. 6.7 Porter's Five Forces Analysis
  7. 7 Regional Market Share & Country-Level Analysis |
    1. 7.1 North America | |
      1. 7.1.1 US | |
      2. 7.1.2 Canada | |
      3. 7.1.3 Mexico |
    2. 7.2 Europe | |
      1. 7.2.1 Germany | |
      2. 7.2.2 UK | |
      3. 7.2.3 France | |
      4. 7.2.4 Italy | |
      5. 7.2.5 Spain | |
      6. 7.2.6 Nordic Countries | |
      7. 7.2.7 Russia | |
      8. 7.2.8 Rest of Europe |
    3. 7.3 Asia-Pacific | |
      1. 7.3.1 China | |
      2. 7.3.2 India | |
      3. 7.3.3 Japan | |
      4. 7.3.4 South Korea | |
      5. 7.3.5 ASEAN | |
      6. 7.3.6 Rest of Asia-Pacific |
    4. 7.4 South America | |
      1. 7.4.1 Brazil | |
      2. 7.4.2 Argentina | |
      3. 7.4.3 Rest of South America |
    5. 7.5 Middle East & Africa | |
      1. 7.5.1 Saudi Arabia | |
      2. 7.5.2 UAE | |
      3. 7.5.3 South Africa | |
      4. 7.5.4 Egypt | |
      5. 7.5.5 Rest of Middle East & Africa
  8. 8 Future Outlook (2026–2035) |
    1. 8.1 Intelligent Devices and Closed-Loop Feedback |
    2. 8.2 Platform Economics Displacing Bespoke Engineering |
    3. 8.3 Viscosity Frontier and Formulation Convergence |
    4. 8.4 Circularity and Regulatory Sustainability Pressure
  9. 9 Market Segmentation Analysis |
    1. 9.1 By Application | |
      1. 9.1.1 Rheumatoid Arthritis | |
      2. 9.1.2 Multiple Sclerosis | |
      3. 9.1.3 Anaphylaxis | |
      4. 9.1.4 Diabetes | |
      5. 9.1.5 Psoriasis & Psoriatic Arthritis | |
      6. 9.1.6 Others |
    2. 9.2 By Usability / Type | |
      1. 9.2.1 Disposable Autoinjectors | |
      2. 9.2.2 Reusable Autoinjectors | |
      3. 9.2.3 Connected Smart Autoinjectors |
    3. 9.3 By Device Technology | |
      1. 9.3.1 Spring Loaded | |
      2. 9.3.2 Gas Propelled | |
      3. 9.3.3 Motorized / Electromechanical | |
      4. 9.3.4 Wearable On-Body Injectors |
    4. 9.4 By Route of Administration | |
      1. 9.4.1 Subcutaneous | |
      2. 9.4.2 Intramuscular | |
      3. 9.4.3 Intradermal |
    5. 9.5 By End User | |
      1. 9.5.1 Home Care Settings | |
      2. 9.5.2 Hospitals | |
      3. 9.5.3 Clinics | |
      4. 9.5.4 Ambulatory Surgical Centers
  10. 10 Competitive Landscape |
    1. 10.1 Market Share Analysis (2026) |
    2. 10.2 Competitive Benchmarking Matrix |
    3. 10.3 Company Profiles | |
      1. 10.3.1 Becton, Dickinson and Company | |
      2. 10.3.2 Ypsomed Holding AG | |
      3. 10.3.3 SHL Medical | |
      4. 10.3.4 Owen Mumford | |
      5. 10.3.5 Gerresheimer AG | |
      6. 10.3.6 Stevanato Group | |
      7. 10.3.7 West Pharmaceutical Services | |
      8. 10.3.8 Viatris | |
      9. 10.3.9 Eli Lilly and Company | |
      10. 10.3.10 Amgen | |
      11. 10.3.11 Novo Nordisk
  11. 11 Recent News & Developments
  12. 12 Report Scope & Methodology |
    1. 12.1 Study Period & Base Year |
    2. 12.2 Data Sources & Triangulation |
    3. 12.3 Abbreviations
  13. 13 Detailed Sources & Citations
  14. 14 Frequently Asked Questions
  15. 15 LIST OF TABLES Source: Market Research Future Analysis
  16. 16 LIST OF FIGURES Source: Market Research Future Analysis

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
By ApplicationRheumatoid Arthritis; Multiple Sclerosis; Anaphylaxis; Diabetes; Psoriasis & Psoriatic Arthritis; OthersRheumatoid ArthritisAnaphylaxis
By Usability / TypeDisposable Autoinjectors; Reusable Autoinjectors; Connected Smart AutoinjectorsDisposable AutoinjectorsConnected Smart Autoinjectors
By Device TechnologySpring Loaded; Gas Propelled; Motorized / Electromechanical; Wearable On-Body InjectorsSpring LoadedWearable On-Body Injectors
By Route of AdministrationSubcutaneous; Intramuscular; IntradermalSubcutaneousIntradermal
By End UserHome Care Settings; Hospitals; Clinics; Ambulatory Surgical CentersHome Care SettingsAmbulatory Surgical Centers
By GeographyNorth America; Europe; Asia-Pacific; South America; Middle East & AfricaNorth AmericaAsia-Pacific


Market Segmentation Overview

By Application

Sub-SegmentKey Trend
Rheumatoid ArthritisBiosimilar anti-TNF pens sustain the largest installed patient base
Multiple SclerosisOral competition slows growth, but injectable maintenance persists
AnaphylaxisExpiry-driven replacement cycles create predictable reorder demand
DiabetesMetabolic pen platforms converge with obesity therapy delivery
Psoriasis & Psoriatic ArthritisIL-17 and IL-23 launches favor low-force injection designs
OthersOncology support, osteoporosis and migraine broaden the base


Autoimmune indications supply the volume foundation, while emergency and metabolic applications supply the growth. Buyers evaluating this dimension should weight expiry-driven replacement demand separately from adherence-driven refill demand — the two behave differently under prescription volatility.

By Usability / Type

Sub-SegmentKey Trend
Disposable AutoinjectorsRemains the default for simplicity and minimal training burden
Reusable AutoinjectorsSustainability rules and cost-per-dose economics revive interest
Connected Smart AutoinjectorsAdherence telemetry becomes a tender scoring criterion


Disposables will hold majority volume through the decade, yet the incremental revenue is migrating toward connected and reusable designs. Device makers positioning for 2030 tenders are already building connectivity into base architectures rather than as an accessory layer.

By Device Technology

Sub-SegmentKey Trend
Spring LoadedMature, high-yield architecture with well-characterized failure modes
Gas PropelledDelivers consistent force profiles for high-viscosity formulations
Motorized / ElectromechanicalEnables programmable delivery rates and dose adjustment
Wearable On-Body InjectorsAbsorbs large-volume subcutaneous regimens leaving infusion suites


Mechanism selection is increasingly dictated by formulation viscosity rather than cost. As antibody concentrations climb past 150 mg/mL, spring-only designs reach their practical limit and hybrid or motorized systems take over.

By Route of Administration

Sub-SegmentKey Trend
SubcutaneousDominant route aligned with biologic formulation development
IntramuscularAnchored by emergency epinephrine and long-acting antipsychotics
IntradermalEmerging in vaccine and immunotherapy applications


Subcutaneous delivery will remain the structural centre of gravity because it is where formulation science is investing. Intradermal remains niche in revenue terms but carries the steepest relative growth as immunotherapy protocols mature.

By End User

Sub-SegmentKey Trend
Home Care SettingsReimbursement policy has made self-administration the default
HospitalsRetains initiation dosing and complex-patient administration
ClinicsSpecialist supervision for titration and monitoring
Ambulatory Surgical CentersDay-case migration lifts procedural device demand


End-user mix is the clearest evidence of the site-of-care shift. Where payers reimburse home administration, hospital share erodes within three to four years — a pattern already visible across North America and the larger European systems.




Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.