Animal Genetics Market (2026 - 2035)

Animal Genetics Market Research Report: Size, Share, Trend Analysis By Products (Genetic Materials, Live Animals, and Others), By Services (Genetic Disease Tests, DNA Typing, and Gene Trait Tests), By End Userss (Veterinary Hospitals & Clinics and Diagnostic Centers), And By Region (North America, Europe, Asia-Pacific, And the Rest Of The World) - Growth Outlook & Industry Forecast 2025 To 2035
ID: MRFR/LS/5539-HCR 90 Pages Rahul Gotadki, Vikita Thakur Last Updated: October 27, 2026
Animal Genetics Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)6.52%
2025 Market SizeUSD 6.54 Billion
2035 Market SizeUSD 12.04 Billion
Key Players
Genus plc (ABS
PIC)
Hendrix Genetics
EW Group (Aviagen
Hy-Line)
URUS Group (CRV
Opportunities
  • Sexed Semen Penetration in Emerging Dairy Systems
  • Aquaculture Genetics as an Underbuilt Category
  • Data Monetization Through Genomic Subscription Platforms

Animal Genetics Market Summary

The Animal Genetics Market reached USD 6.54 billion in 2025 and opens the forecast window at USD 6.81 billion in 2026, advancing to USD 12.04 billion by 2035 at a 6.52% CAGR. Two catalysts anchor that trajectory. The USDA Agricultural Research Service sustained roughly USD 1.9 billion in annual in-house research funding across food animal production programs, a share of which underwrites genomic selection reference populations [1]. The FAO's Global Plan of Action for Animal Genetic Resources, adopted by 109 countries, obliges signatories to maintain breed characterization and cryoconservation programs, which converts genetic recordkeeping from a discretionary cost into a reporting obligation [2].

Selection methodology inside the Animal Genetics Market is being rebuilt. Pedigree-and-progeny testing — a system that required four to six years to validate a dairy sire — is giving way to genomic estimated breeding values derived from 50K–777K SNP arrays that return a reliability score within weeks. Sequencing economics made the substitution viable: per-genome costs fell from roughly USD 10,000 in 2011 to under USD 200 by 2024 [3]. The European Commission committed EUR 8.9 billion to Horizon Europe Cluster 6, which funds livestock genomics and animal health resilience work [4].

North America holds 37.1% of the Animal Genetics Market on the strength of integrated poultry and swine operations and a dense laboratory network. Asia-Pacific grows fastest at 7.94% CAGR as China's dairy consolidation and India's Rashtriya Gokul Mission scale artificial insemination coverage. Europe follows at 28.4%, supported by breed association datasets that stretch back decades. Genomic infrastructure built this decade will define competitive position in the next.

Key Report Takeaways

• By Product Type (Value)

  • Live animals commanded 58.4% of Animal Genetics Market revenue in 2025, sustained by buyer willingness to pay premiums for validated sires
  • Genetic material — semen, embryos, DNA libraries — advances at 7.20% CAGR as vitrification lifts post-thaw viability above 90%

• By Testing Service Type (Value)

  • Genetic trait and performance testing generated USD 3.34 billion in 2025, the largest service pool in the Animal Genetics Market
  • DNA typing and parentage testing posts 7.25% CAGR on falling per-sample sequencing costs

• By Technology (Value)

  • Artificial insemination delivered 52.9% of 2025 revenue across bovine, porcine and ovine herds
  • CRISPR and gene editing records the fastest 7.88% CAGR despite a modest current base

• By End User (Value)

  • Breeding companies and associations held 35.6% of revenue, backed by proprietary lines and global distribution
  • Veterinary hospitals and clinics expand at 8.15% CAGR as genomic diagnostics enter routine care

• By Region

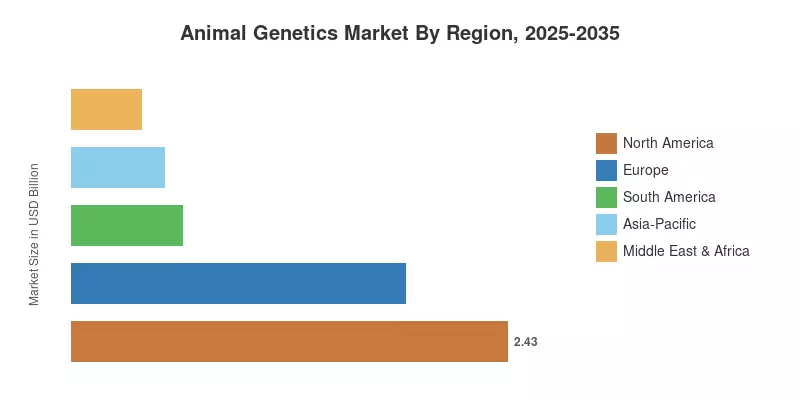
  • North America contributed USD 2.43 billion in 2025, the largest regional pool
  • Asia-Pacific compounds at 7.94% through 2035, the fastest of any region
  • Europe holds a 28.4% share, anchored by long-running breed association pedigree databases

Market Size and Forecast (2021–2035)

Sizing combines bottom-up revenue modelling of semen and embryo unit volumes, laboratory test throughput, and breeding stock transaction values, triangulated against company filings, FAO livestock census data, and national herd registries. Historical years are reconstructed from audited revenue disclosures of the ten largest participants and regulatory trade statistics; forecast years apply species-level herd growth assumptions to per-head genetic spend.
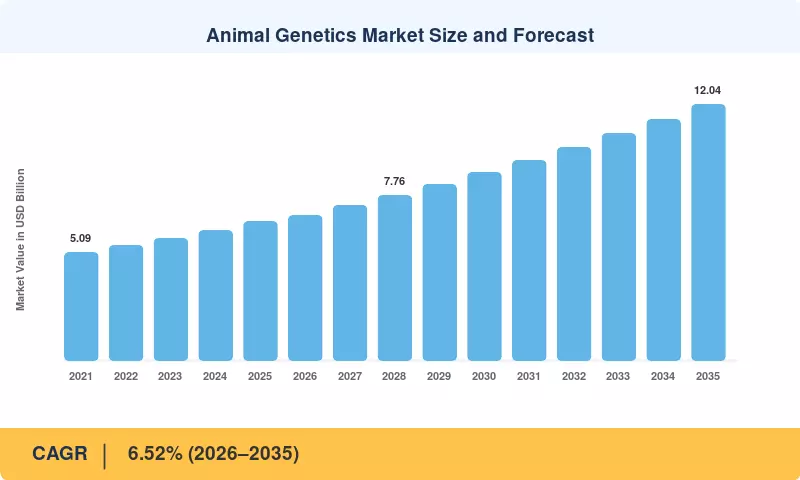
Animal Genetics Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Collapsing sequencing and genotyping costs 1.5 Global Short-term (≤2 yr)
Protein demand growth in emerging economies 1.2 Asia-Pacific, South America Long-term (≥4 yr)
Government artificial insemination programs 1.0 Asia-Pacific, MEA Medium-term (2–4 yr)
Disease resistance breeding mandates 0.9 Europe, North America Medium-term (2–4 yr)
Dairy and swine operation consolidation 0.8 Global Long-term (≥4 yr)
Companion animal genomic diagnostics 0.7 North America, Europe Short-term (≤2 yr)
Feed conversion efficiency economics 0.6 Global Long-term (≥4 yr)


Collapsing Sequencing and Genotyping Costs

By 2024, per-sample genotyping on mid-density bovine SNP arrays was less than USD 30, compared to about USD 250 ten years prior [3]. Genomic testing shifted from elite seedstock to commercial herds as a result of this reduction. Through the Council on Dairy Cattle Breeding, US dairy farmers now genotype more than 500,000 heifers each year, and the reference population has more than 8 million animals. This scale directly improves breeding value reliability and increases the value of each subsequent test.


Protein Demand Growth in Emerging Economies

In comparison to a 2020 baseline, FAO predicts that worldwide meat consumption would increase by 14% by 2030, with nearly all of the additional volume occurring in low- and middle-income nations [10]. Growth in output must come from per-animal productivity if producers are unable to increase land area proportionately. Vietnamese, Brazilian, and Indonesian integrators have shifted to imported grandparent stock and structured selection indices because genetic improvement accounts for almost half of the realized productivity gain in intensive poultry systems.


Government Artificial Insemination Programs

India's Rashtriya Gokul Mission received INR 2,400 crore under the 2021–2026 plan cycle and has delivered free artificial insemination to more than 80 million animals across 605 districts . Ethiopia, Kenya and Pakistan run analogous schemes with World Bank co-financing. These programs build technician networks and liquid nitrogen distribution infrastructure that private semen suppliers subsequently use, converting public spend into durable commercial channel capacity.

Disease Resistance Breeding Mandates

The European Union's Animal Health Law, Regulation 2016/429, requires member states to operate surveillance and eradication programs for listed diseases, pushing breeders toward genetically resistant lines [12]. Scrapie-resistant genotype selection in sheep, mandatory under UK and EU national plans, established the template. PRRS-resistant swine and avian influenza tolerance in poultry now follow the same regulatory logic, with resistance markers embedded directly into commercial selection indices.

Dairy and Swine Operation Consolidation

USDA census data shows US dairy operations fell from 39,300 in 2017 to under 24,500 by 2024 while total cow numbers held near 9.3 million [13]. Larger units justify dedicated reproduction staff, on-farm sensors, and structured genetic programs that 60-cow herds could not. Average genetic spend per head rises roughly 2.5 times when herd size crosses 1,000 animals, so consolidation mechanically lifts addressable revenue without any change in underlying technology.

Companion Animal Genomic Diagnostics

Breed-specific hereditary disease panels now screen for over 250 variants in dogs, and uptake among US veterinary practices reached an estimated 18% of clinics offering in-house genetic screening by 2024 [14]. The expanded 21,000-square-foot UC Davis Veterinary Genetics Laboratory processes tens of thousands of samples monthly at turnaround times supporting same-week clinical decisions. This channel carries higher gross margins than livestock testing and grows independently of agricultural commodity cycles.

Feed Conversion Efficiency Economics

Feed represents 60–70% of broiler production cost, so a 0.01 improvement in feed conversion ratio saves an integrator processing 500 million birds annually roughly USD 12 million [15]. Genetic selection has cut broiler FCR from 2.0 to below 1.55 over three decades. With soybean meal and maize prices volatile since 2022, integrators treat residual feed intake selection as a hedge rather than an optimization, which sustains genetic spend through commodity downturns.

Restraints Impact Analysis

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
Gene-editing regulatory uncertainty -0.9 Europe, Asia-Pacific Medium-term (2–4 yr)
Smallholder capital constraints -0.7 Asia-Pacific, MEA Long-term (≥4 yr)
Genetic diversity erosion concerns -0.5 Global Long-term (≥4 yr)
Cold chain and logistics failure rates -0.4 MEA, South America Short-term (≤2 yr)
Data ownership disputes between breeders and platforms -0.3 North America, Europe Medium-term (2–4 yr)


Gene-Editing Regulatory Uncertainty

Gene-edited creatures were placed under Directive 2001/18/EC by the Court of Justice of the European Union's 2018 judgment, and animals are still not included in the New Genomic Techniques proposal, which was proposed in July 2023 [16]. As a result, developers are unable to sell modified cattle to 450 million people. European investment is stifled by this imbalance against the United States, which authorized gene-edited pork in 2025.


Smallholder Capital Constraints

A significant portion of the world's livestock is kept on 500 million smallholder farms, according to estimates, yet the median annual household income in these systems is less than USD 2,500 [17]. In contrast to unclear conception rates, a USD 25 semen straw plus technician cost is a material expenditure. Genetic upgrading stops at the point where it would yield the largest proportionate productivity gain in the absence of subsidies or cooperative aggregation.


Genetic Diversity Erosion Concerns

FAO's Domestic Animal Diversity Information System classifies 26% of reported livestock breeds as at risk of extinction, with intensive selection on narrow elite lines a documented contributor [2]. Holstein effective population size has fallen below 50 in some national herds. Regulators and breed associations increasingly impose inbreeding coefficient ceilings, which constrain how aggressively suppliers can market top-ranked sires.

Cold Chain and Logistics Failure Rates

Frozen semen and embryos require uninterrupted liquid nitrogen at -196°C. Field audits in sub-Saharan artificial insemination programs have recorded conception rates 15–20 percentage points below temperate benchmarks, with tank failure and thaw mishandling the leading causes [18]. Each failed insemination destroys the product's value and damages producer confidence, slowing repeat purchase in precisely the markets with the largest untapped herd base.

Data Ownership Disputes Between Breeders and Platforms

Genomic evaluations depend on pooled phenotype data, but producers increasingly contest who owns performance records uploaded to proprietary herd management platforms. US litigation and European Data Act provisions applying from September 2025 have forced renegotiation of contributor agreements [19]. Where terms remain unsettled, producers withhold records, thinning the reference populations that make evaluations accurate.

Animal Genetics Market Opportunities

Sexed Semen Penetration in Emerging Dairy Systems

Sexed semen now exceeds 70% of dairy inseminations in the United States but remains under 15% across most of South and Southeast Asia. Flow cytometry throughput improvements and licensing arrangements have cut the price premium over conventional straws from roughly 3x to 1.7x. For a smallholder with three cows, guaranteeing heifer replacements materially changes herd economics. Suppliers that pair sexed product with financing and technician training capture a channel competitors cannot easily replicate.

Aquaculture Genetics as an Underbuilt Category

Farmed fish supply over half of aquatic food consumed globally, yet fewer than 10% of aquaculture species have structured breeding programs. Atlantic salmon demonstrates the prize: four decades of selection roughly doubled growth rate and cut production cycles. Tilapia, shrimp, and pangasius programs remain early-stage. Genomic selection applied to disease resistance in shrimp, where white spot syndrome causes billions in annual loss, represents the clearest near-term commercial opening.

Data Monetization Through Genomic Subscription Platforms

Laboratories historically sold discrete tests. The emerging model licenses ongoing access to evaluation engines, benchmarking dashboards, and mating allocation algorithms for a per-cow annual fee. Recurring revenue carries higher multiples than transactional testing and lifts switching costs sharply, because a producer who exports raw genotypes still loses the comparative benchmarks. Companies building proprietary phenotype pools alongside genotype libraries create a data asset competitors cannot buy.

Methane-Efficiency Trait Selection

New Zealand and Ireland have added methane-related traits to national breeding indices, and low-emission sires show measurable heritability around 0.20. With agricultural emissions entering national inventories and carbon markets, a genetic route to reduction that costs nothing per animal after selection is commercially distinctive. Breeding companies that build methane phenotype reference populations first will hold a durable advantage as reporting obligations tighten across the EU and Oceania.

African Livestock Genetic Upgrading

Sub-Saharan Africa holds roughly 350 million cattle, producing a fraction of temperate per-animal output. Crossbreeding programs pairing indigenous heat and disease tolerance with exotic productivity — rather than wholesale breed replacement — have shown durable results in Ethiopia and Tanzania. Donor-funded infrastructure creates the distribution backbone; commercial suppliers then sell into an established channel. The gap is large enough that even modest penetration shifts regional totals.

Animal Genetics Market Future Outlook

Machine Learning in Genomic Prediction

Linear mixed models have carried genomic selection for fifteen years, but they capture additive effects poorly when marker density reaches whole-genome resolution. Deep learning approaches trained on combined genotype, phenotype, and environmental datasets show accuracy gains of 3–8% for complex traits in published trials. With whole-genome sequencing costs now under USD 200 per animal [3], reference populations will shift from array genotypes to sequence data across the forecast period, and the computational method becomes the differentiator rather than the assay.

Gene Editing Moves From Trials to Herds

Commercial precedent now exists. Field trials with BMPRIB-edited fine-wool sheep achieved 47.4% editing efficiency with measurably higher litter sizes, and United States regulators cleared gene-edited pork for market. Disease resistance is the first commercial application because it addresses losses producers already quantify — PRRS alone costs North American swine producers over USD 1.2 billion annually . Adoption speed depends less on the biology than on labelling policy and consumer acceptance in export destination markets.

Sustainability Reporting Pulls Genetics Into Scope

Agriculture accounts for roughly 12% of global greenhouse gas emissions on IPCC accounting, with enteric fermentation the dominant livestock source. As the EU Corporate Sustainability Reporting Directive extends Scope 3 disclosure into food supply chains, processors will demand emissions data from suppliers. Breeding indices that weight feed efficiency and methane traits offer permanent, cumulative reduction rather than annual operational adjustment, which makes genetics unusually attractive against alternatives requiring continuous input spend.

Consolidation Reshapes the Supplier Base

The Animal Genetics Market retains medium concentration, but the economics favor scale: reference population size directly determines evaluation accuracy, and accuracy determines product performance. That creates a reinforcing advantage larger players compound each cycle. Expect continued acquisition of species specialists and laboratory networks by diversified animal health groups seeking to bundle genetics with nutrition and pharmaceuticals. Regional champions in Brazil, India, and China represent the most likely acquisition targets through 2030.

Regional Market Share Analysis

Region Metric Primary Investment Themes
North America USD 2.43 B (2025) Genomic dairy evaluation, gene-edited swine, companion animal panels
Europe 28.4% share Breed association datasets, disease resistance breeding, methane traits
Asia-Pacific 7.94% CAGR Public artificial insemination schemes, dairy consolidation, poultry integration
South America USD 0.62 B (2025) Beef genetics export, tropical adaptation traits
Middle East & Africa 5.9% share Crossbreeding programs, donor-funded infrastructure
Total USD 6.54 B (2025) —

Regional distribution in the Animal Genetics Market reflects herd structure, laboratory density, and the maturity of national recording schemes rather than livestock population alone.


North America

Country Metric Key Driver
United States 84.2% of region Dense genomic evaluation infrastructure and integrated swine and poultry operations


United States leadership rests on institutional scale rather than herd size. The Council on Dairy Cattle Breeding maintains genomic evaluations on a reference population exceeding 8 million animals, giving domestic breeding values reliability levels no other national system matches. FDA's 2025 approval pathway for gene-edited swine established the first major regulatory green light for edited food animals, and USDA Agricultural Research Service programs continue funding phenotype collection that private breeders could not economically replicate on their own [1].

Europe

Country Metric Key Driver
Rest of Europe 28.4% of global market Long-horizon breed association pedigree databases and EU animal health regulation


European strength derives from data depth. Scandinavian and Dutch recording schemes hold continuous performance records stretching back decades, which supports evaluation of low-heritability traits such as fertility and health that shorter datasets cannot resolve. Horizon Europe Cluster 6 directs EUR 8.9 billion toward food, bioeconomy and agriculture research, with livestock genomics a recurring call topic [4]. Regulatory exclusion of edited animals, however, redirects European investment toward conventional genomic selection.

Asia-Pacific

Country Metric Key Driver
Rest of Asia-Pacific 7.94% CAGR State artificial insemination programs and rapid dairy and swine consolidation


Asia-Pacific growth is policy-led. India's Rashtriya Gokul Mission has extended free artificial insemination coverage to over 80 million animals and built a technician network numbering in the tens of thousands . China's post-African swine fever rebuild replaced fragmented backyard production with integrated units running structured genetic programs, permanently raising per-head genetic spend. Vietnamese and Indonesian poultry integrators import grandparent stock at scale, embedding dependence on external genetic supply.

South America

Country Metric Key Driver
Rest of South America USD 0.62 B (2025) Beef cattle genetics and tropical adaptation trait selection


Brazil anchors the region with the world's largest commercial cattle herd and a Nelore genetic improvement program that has run structured performance recording since the 1980s. Embrapa's breeding work on tropical adaptation — heat tolerance, tick resistance, forage efficiency — produces genetics with export value into Africa and Southeast Asia. Argentine and Uruguayan beef exporters increasingly use genomic testing to certify marbling and tenderness for premium Asian buyers, adding a traceability dimension to genetic spend.

Middle East & Africa

Country Metric Key Driver
Rest of Middle East & Africa 5.9% of global market Donor-financed crossbreeding schemes and dairy import substitution


Gulf states pursue dairy self-sufficiency through large intensive units importing elite Holstein genetics, with Saudi Arabia's Almarai operating herds exceeding 90,000 head under climate-controlled conditions. Sub-Saharan activity follows a different logic, centered on crossbreeding programs that retain indigenous disease and heat tolerance. Cold chain reliability remains the binding constraint; field conception rates trail temperate benchmarks by 15–20 percentage points where liquid nitrogen distribution is intermittent [18].

Animal Genetics Market By Region, 2025-2035

Animal Genetics Market Segmentation

By Product Type (Value)

Segment Metric Primary Demand Driver
Live Animals 58.4% share (2025) Buyer premium for proven sires with validated production records
Genetic Material 7.20% CAGR Cryopreservation advances and digital germplasm ordering


Live animals remain the revenue anchor because commercial buyers pay heavily for demonstrated on-farm performance, with elite sires transacting above USD 50,000. Improved quarantine and logistics infrastructure has simplified cross-border movement of breeding stock. Genetic material grows faster: embryo vitrification now delivers post-thaw viability above 90%, letting emerging-market dairies achieve rapid genetic gain without importing live cattle. Semen carries volume; premium embryos and DNA libraries carry margin.

By Testing Service Type (Value)

Segment Metric Primary Demand Driver
Genetic Trait Tests USD 3.34 B (2025) Selection index refinement across milk yield, carcass, and feed traits
DNA Typing and Parentage Testing 7.25% CAGR Falling sequencing costs and mail-in collection kits
Genetic Disease Testing 6.10% CAGR Breed-specific hereditary screening in companion animals and seedstock


Genetic trait testing leads because integrated pork and poultry operations compound small feed efficiency gains across millions of head, making the service economics unambiguous. Cloud dashboards now return real-time benchmarking each breeding cycle. DNA typing grows fastest as per-sample costs collapse and handheld collection kits reach clinics; laboratories bundle typing with trait panels to upsell analytics. Genetic disease testing tracks companion animal demand, where hereditary variant panels have become standard practice in specialty veterinary care.

By Technology (Value)

Segment Metric Primary Demand Driver
Artificial Insemination (AI) 52.9% share (2025) Cost-effective propagation of desirable genetics across large herds
Embryo Transfer (ET) USD 1.21 B (2025) Multiplication of elite female genetics in dairy and beef
CRISPR and Gene Editing 7.88% CAGR Disease resistance traits and regulatory clearance in the United States


By End User (Value)

Segment Metric Primary Demand Driver
Breeding Companies & Associations 35.6% share (2025) Proprietary lines, R&D pipelines and global distribution networks
Livestock Producers/Farms USD 2.09 B (2025) Direct genetic procurement by consolidated dairy and swine operations
Veterinary Hospitals and Clinics 8.15% CAGR Integration of genomic diagnostics into routine health management


Breeding companies and associations lead on scale, and many now bundle scenario-modelling software that raises client switching costs before a straw is purchased. Consolidation continues as firms buy species coverage or editing capability. Veterinary hospitals and clinics grow fastest: laboratory expansion — the UC Davis facility now runs tens of thousands of samples monthly — supports same-week clinical decisions, pulling genetic testing into standard practice well beyond traditional breeding operations.

Competitive Benchmarking

Concentration sits in the medium band. The top five participants hold an estimated 38–44% of global revenue, producing an HHI in the 550–750 range — competitive by antitrust standards, but with a clear tier structure. Scale matters asymmetrically: reference population size determines evaluation accuracy, so leaders compound advantage each breeding cycle. Fragmentation persists at the species and regional level, where poultry, aquaculture, and companion animal specialists operate largely outside the bovine mainstream.

Company Est. Revenue Share Range Key Offerings for Animal Genetics Market Strategic Positioning
Genus plc (ABS, PIC) ~11–14% Bovine semen, porcine breeding stock, sexed genetics Dual-species scale leader with gene-editing pipeline
Hendrix Genetics ~7–9% Layer, turkey, swine, aquaculture breeding programs Broadest species portfolio among private players
EW Group (Aviagen, Hy-Line) ~7–9% Broiler and layer grandparent stock Poultry genetics incumbent with global hatchery reach
URUS Group (CRV, Alta, GENEX) ~5–7% Bovine genetics, herd management data services Cooperative-rooted network with strong data assets
Neogen Corporation ~4–6% Genomic testing, DNA typing, food safety diagnostics Laboratory-led model spanning livestock and companion animals
Zoetis Inc. ~4–6% Precision livestock genomics, companion animal diagnostics Animal health platform bundling genetics with therapeutics
Topigs Norsvin ~3–5% Porcine breeding programs and boar semen Swine specialist with strong European and Brazilian presence
Groupe Grimaud ~3–4% Waterfowl, rabbit and specialty poultry genetics Niche species leader with biopharma adjacency
Alltech (Coppens, ETALON) ~2–4% Equine and livestock genotyping services Nutrition-plus-genetics integration play
VetGen / Mars Petcare (Wisdom Panel) ~2–4% Companion animal DNA panels and hereditary screening Consumer-facing genomics with clinical channel expansion


Recent News & Developments

  • US Food and Drug Administration (April 2025): Cleared gene-edited swine carrying PRRS resistance for the food supply, the first such approval for a major livestock species and a template for subsequent editing submissions .
  • Genus plc (October 2024): Reported regulatory progress on its PRRS-resistant pig programme across multiple export markets, advancing the commercial timeline for edited breeding stock distribution .
  • Neogen Corporation (June 2024): Expanded genomic testing capacity at its Lincoln, Nebraska laboratory, targeting faster turnaround for large-herd bovine genotyping contracts [14].
  • European Commission (July 2023): Tabled the New Genomic Techniques regulation covering plants but excluding animals, preserving the existing GMO framework for edited livestock across the bloc [16].
  • Hendrix Genetics (March 2024): Announced expansion of its shrimp breeding programme in Latin America, targeting white spot syndrome resistance traits for commercial hatchery customers [20].
  • Government of India (February 2024): Reported the Rashtriya Gokul Mission surpassing 80 million animals covered under nationwide free artificial insemination, with coverage extended across 605 districts .
  • Zoetis Inc. (September 2023): Launched an expanded precision livestock genomics offering integrating genotype results with herd health monitoring data for dairy clients [21].
  • UC Davis Veterinary Genetics Laboratory (May 2024): Opened a 21,000-square-foot expanded facility capable of processing tens of thousands of diagnostic samples monthly for companion and production animals [14].

Animal Genetics Market Report Scope

Report Attribute/Metric Details
Market Scope Global animal genetics products and services spanning live breeding animals, genetic material, testing services, and reproductive technologies across bovine, porcine, poultry, ovine, aquaculture, and companion animals
Study Period 2021-2035
Base Year 2025
Historical Data 2021–2024
Forecast Period 2026–2035
Market Size in 2025 USD 6.54 Billion
Market Size in 2035 USD 12.04 Billion
CAGR (2026–2035) 6.52%
Fastest Growing Segments Genetic Material (7.20% CAGR); CRISPR and Gene Editing (7.88% CAGR); Veterinary Hospitals and Clinics (8.15% CAGR); Asia-Pacific (7.94% CAGR)
Regions Covered Asia-Pacific (7.94% CAGR); North America, Europe, APAC, South America, MEA
Companies Profiled Genus plc, Hendrix Genetics, EW Group, URUS Group, Neogen Corporation, Zoetis Inc., Topigs Norsvin, Groupe Grimaud, Alltech, VetGen / Mars Petcare
Valuation Currency USD Billion
Methodology Triangulated approach: top-down (manufacturer revenue), bottom-up (unit shipment × ASP), econometric (housing starts, hospitality pipeline correlation)

FAQs

How should a buyer evaluate vendors in the Animal Genetics Market beyond price per straw?
Reference population size and phenotype depth determine evaluation reliability more than list price. Ask for reliability percentages on the specific traits you select for, not aggregate index figures [22].
What contractual terms matter most when signing a genomic testing agreement?
Data ownership and portability clauses. Confirm you can export raw genotypes and retain rights to phenotype records if you switch providers, since European Data Act provisions now support that position [19].
How does the Animal Genetics Market treat intellectual property in breeding lines?
Protection relies on trade secrecy and terminal-cross structures rather than patents for conventional genetics. Gene-edited traits are patentable, which is shifting competitive strategy toward editing portfolios .
What integration problems arise when adding genomic data to existing herd software?
Identifier mismatches between laboratory sample codes and on-farm animal IDs cause most failures. Resolve tagging conventions before the first batch ships, or reconciliation costs exceed the testing spend [21].
Is embryo transfer worth the cost premium over artificial insemination for mid-sized herds?
Only where individual female genetic merit justifies multiplication — typically the top 5% of a herd. Below that threshold, conventional insemination with sexed semen delivers better return per dollar.
How do investors assess risk in the Animal Genetics Market given commodity cycle exposure?
Recurring testing and service revenue proves more cycle-resistant than live animal sales. Companion animal diagnostics exposure further decouples earnings from agricultural commodity prices [14].
What regulatory nuance should exporters of genetic material watch most closely?
Destination-market rules on gene-edited progeny differ sharply from origin-market approvals. Product cleared in the United States may be blocked in the European Union, stranding inventory mid-chain [16].
Author
Author Author Profile Rahul Gotadki LinkedIn Research Manager
He holds an experience of about 9+ years in Market Research and Business Consulting, working under the spectrum of Life Sciences and Healthcare domains. Rahul conceptualizes and implements a scalable business strategy and provides strategic leadership to the clients. His expertise lies in market estimation, competitive intelligence, pipeline analysis, customer assessment, etc.
Co-Author Co-Author Profile Vikita Thakur LinkedIn Senior Research Analyst
She holds an experience of about 5+ years in market research and business consulting projects for sectors such as life sciences, medical devices, and healthcare IT. She possesses a robust background in data analysis, market estimation, competitive intelligence, pipeline analysis market trend identification, and consumer behavior insights. Her expertise lies in technical Sales support, client interaction and project management, designing and implementing market research studies, conducting competitive analysis, and synthesizing complex data into actionable recommendations that drive business growth.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of regulatory databases, peer-reviewed veterinary and agricultural journals, livestock industry publications, and authoritative food and agriculture organizations. Key sources included the US Department of Agriculture (USDA) National Agricultural Statistics Service (NASS), European Food Safety Authority (EFSA), Food and Agriculture Organization of the United Nations (FAO) Animal Production and Health Division, National Institute of Food and Agriculture (NIFA), International Society for Animal Genetics (ISAG), World Organisation for Animal Health (WOAH), OECD-FAO Agricultural Outlook Database, National Center for Biotechnology Information (NCBI/PubMed), CDC National Center for Emerging and Zoonotic Infectious Diseases (NCEZID), WHO Department of Control of Neglected Tropical Diseases (veterinary genetics division), EU Commission Directorate-General for Agriculture and Rural Development, and national livestock registries from key markets (Canadian Food Inspection Agency, Australian Gene Technology Regulator, Brazil's Ministry of Agriculture MAPA).

These sources were employed to compile data on the population statistics of livestock, the regulatory approval data for gene-edited animals, the statistics of artificial insemination and embryo transfer, the trends in breed registration, and the market landscape analysis for genetic materials (semen/embryos), genetic testing services, and live animal genetics.


Primary Research

Qualitative and quantitative insights were obtained by interviewing supply-side and demand-side stakeholders during the primary research process. The supply-side sources consist of CEOs, VPs of Research & Development, heads of regulatory affairs for genetically modified organisms, and commercial directors from animal genetics companies, artificial insemination service providers, livestock breeding corporations, and veterinary diagnostic laboratories. Chief veterinary officers, livestock breeding managers, dairy and beef cattle producers, poultry genetics specialists, diagnostic center directors, and procurement leads from large-scale farming cooperatives, veterinary hospitals, and academic research institutions constituted demand-side sources. Primary research has confirmed the product pipeline timelines for CRISPR-based breeding technologies, gathered insights on the adoption patterns of assisted reproductive technologies, pricing strategies for genetic material, and regulatory dynamics for gene-edited livestock, and validated market segmentation across live animals (bovine, porcine, poultry, canine), genetic materials (semen, embryos), and testing services (genetic disease, DNA typing, gene trait analysis).

Primary Respondent Breakdown:

By Designation: C-level Primaries (40%), Director Level (32%), Others (28%)

By Region: North America (32%), Europe (28%), Asia-Pacific (34%), Rest of World (6%)


Market Size Estimation

Revenue mapping and procedure volume analysis were implemented to determine global market valuation. The methodology comprised the following:

The identification of over 50 significant manufacturers in North America, Europe, Asia-Pacific, and Latin America who specialize in animal genetics, including animal breeding companies, artificial insemination providers, and genetic testing service laboratories.

Product mapping encompasses genetic testing services (genetic disease testing, DNA parentage verification, gene trait analysis for milk production, disease resistance, and growth traits), genetic materials (bovine semen, porcine embryos, ovine embryos), and live animals (dairy cattle, beef cattle, swine, poultry).

Examination of the annual revenues of animal genetics portfolios, including the volumes of artificial insemination procedures, embryo transfer cycles, and genetic test samples, as reported and modeled.

Coverage of manufacturers and service providers that account for 72-76% of the global market share in 2024

Segment-specific valuations for genetic materials, live animals, and genetic testing services are derived through extrapolation using bottom-up (live animal population × genetic testing penetration rates × ASP by country; procedure volumes for AI and embryo transfer × average service fees) and top-down (manufacturer revenue validation through genetic material sales and service contracts) approaches.

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.

















