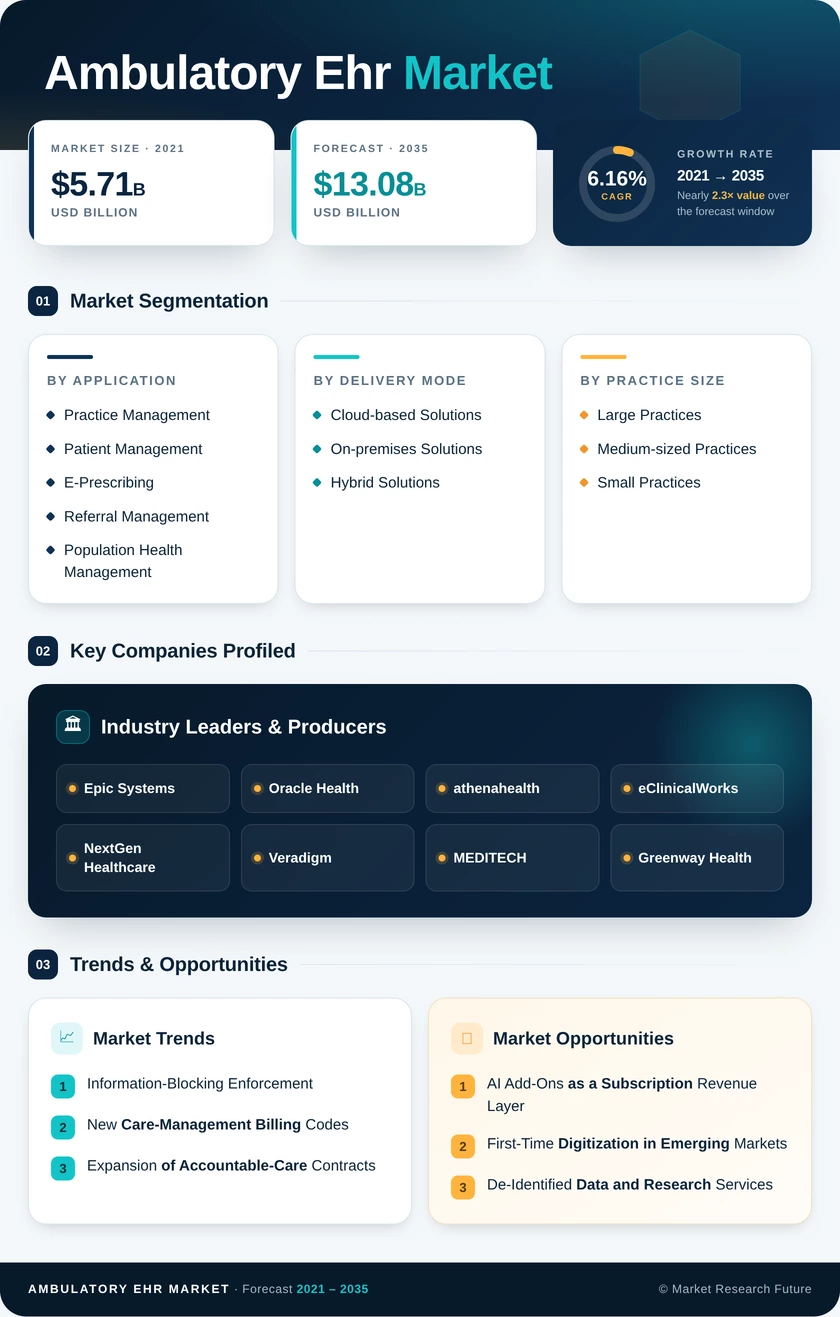
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
|---|
| By Application | Practice Management; Patient Management; E-Prescribing; Referral Management; Population Health Management; Others | Practice Management (25.9% share) | Population Health Management (6.8% CAGR) |
| By Delivery Mode | Cloud-based Solutions; On-premises Solutions; Hybrid Solutions | Cloud-based Solutions (72.0% share) | Hybrid Solutions (7.9% CAGR) |
| By Practice Size | Large Practices; Medium-sized Practices; Small Practices | Large Practices (60.8% share) | Small Practices (7.3% CAGR) |
| By End-User | Hospital-owned Ambulatory Centers; Independent Ambulatory Centers; Health-system Affiliated Physician Groups | Hospital-owned Ambulatory Centers (59.2% share) | Independent Ambulatory Centers (7.0% CAGR) |
| By Region | North America; Europe; Asia-Pacific; Middle East and Africa; South America | North America (45.2% share) | Asia-Pacific (8.1% CAGR (2026–2035)) |
Market Segmentation Overview
| Sub-Segment | Key Trend |
|---|
| Practice Management | Automated eligibility checks and claims scrubbing |
| Patient Management | Self-scheduling, digital intake and telehealth |
| E-Prescribing | Controlled-substance e-prescribing and benefit checks |
| Referral Management | Network-based exchange replacing fax referrals |
| Population Health Management | Risk stratification tied to APCM and ACO contracts |
| Others | Specialty modules and AI add-ons |
Practice Management leads because scheduling and billing are the first tools any clinic buys. Population Health Management grows fastest since APCM codes and shared-savings contracts pay practices to track chronic patients across a full panel. Referral Management gains from network exchange that replaces fax-based referrals.
| Sub-Segment | Key Trend |
|---|
| Cloud-based Solutions | Subscription pricing and automatic updates |
| On-premise Solutions | Retained for data-sovereignty and research needs |
| Hybrid Solutions | Local record copies for outage resilience |
Cloud-based Solutions lead on lower upfront cost and automatic regulatory updates. Hybrid Solutions grow fastest because the 2024 Change Healthcare outage pushed large systems to keep a local copy of core records. On-premise Solutions persist mainly in academic groups that manage research data.
| Sub-Segment | Key Trend |
|---|
| Large Practices | Enterprise analytics and integration |
| Medium-sized Practices | Managed-service partnerships for IT support |
| Small Practices | Templated cloud packages with fast go-lives |
Large Practices hold the most revenue through enterprise licences and integration work. Small Practices grow fastest as vendors offer templated cloud packages that go live in weeks. Medium-sized Practices increasingly rely on managed-service partners to run enterprise-grade features without in-house IT teams.
| Sub-Segment | Key Trend |
|---|
| Hospital-owned Ambulatory Centers | Enterprise EHR extended to acquired outpatient sites |
| Independent Ambulatory Centers | Cloud platforms with lower switching costs |
| Health-system Affiliated Physician Groups | Shared records under affiliation agreements |
Hospital-owned Ambulatory Centers lead because health systems roll their enterprise EHR out to every clinic they acquire. Independent Ambulatory Centers grow fastest, choosing cloud platforms that cost less and deploy faster. Health-system Affiliated Physician Groups often adopt the partner hospital's system to share records and quality data.


 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA