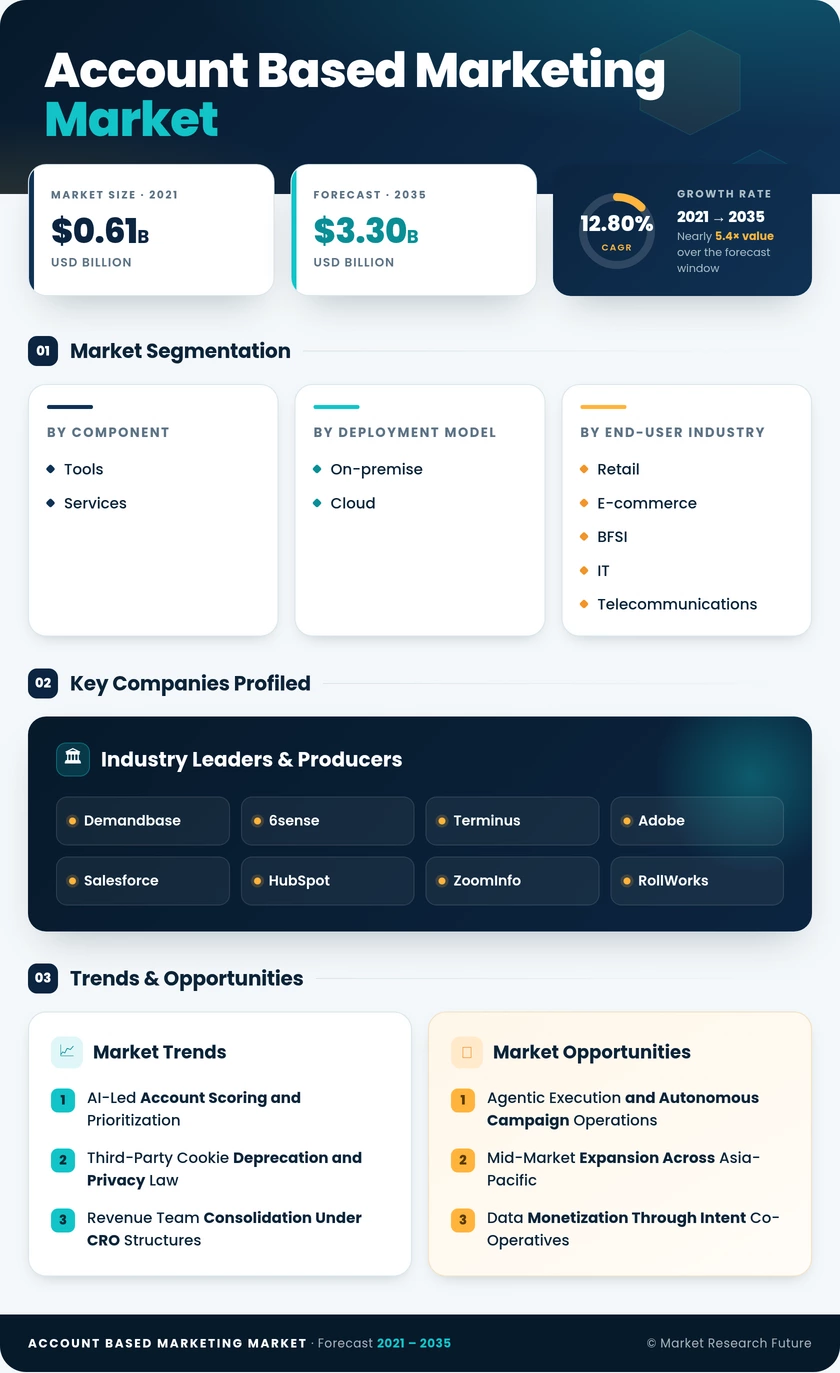
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
|---|---|---|---|
| By Component | Tools, Services | Tools (68.4% share, 2025) | Services (15.05% CAGR) |
| By Deployment Model | On-premise, Cloud | Cloud (76.2% share, 2025) | Cloud (76.2% share, 2025) |
| By End-user Industry | Retail and E-commerce, BFSI, IT and Telecommunications, Government, Healthcare and Life Sciences | IT and Telecommunications (27.3% share, 2025) | Healthcare and Life Sciences (15.65% CAGR) |
| By Organization Size | Large Enterprises, Mid-sized Enterprises, Small Businesses | Large Enterprises (61.1% share, 2025) | Mid-sized Enterprises (15.30% CAGR) |
| By Channel | Email, Display Advertising, Social Media | Display Advertising (31.5% share, 2025) | Social Media (16.10% CAGR) |
| By Region | North America, Europe, Asia-Pacific, South America, Middle East & Africa | North America (51.2% share, 2025) | Asia-Pacific (15.60% CAGR) |
Market Segmentation Overview
By Component
| Sub-Segment | Key Trend |
|---|---|
| Tools | AI-powered account selection and multi-channel orchestration consolidate into single platforms |
| Services | Vertical playbooks, attribution consulting, and first-party data architecture engagements expand |
Tools carry the larger share because every program begins with a platform licence, and buyers still evaluate vendors primarily on scoring accuracy and connector breadth. Services grow faster since execution capability — not software access — determines whether programs convert coverage into pipeline. Providers packaging managed campaign delivery alongside licences report materially lower first-year churn, which is why platform vendors are building services arms rather than leaving delivery to partners.
By Deployment Model
| Sub-Segment | Key Trend |
|---|---|
| On-premise | Retained in data-residency-bound financial services and public-sector-linked environments |
| Cloud | Elastic compute and turnkey CRM, CDP, and intent connectors drive default selection |
Cloud both leads and grows fastest here, since SaaS delivery removes the integration work that once made account-based deployment a multi-quarter project. On-premise holds a shrinking but durable base wherever India's DPDP Act, GDPR residency provisions, or Gulf sovereign cloud rules require local processing. Hybrid architectures — local stores with cloud orchestration — are steadily converting former on-premise holdouts as zero-trust controls satisfy security review.
By End-user Industry
| Sub-Segment | Key Trend |
|---|---|
| Retail and E-commerce | B2B commerce platforms demand personalized buyer journeys at account level |
| BFSI | Digital transformation and sustainable-finance deal pursuit drive account targeting |
| IT and Telecommunications | Technographic depth and large buying committees sustain heaviest usage |
| Government | Procurement-cycle timing and contractor engagement shape campaign design |
| Healthcare and Life Sciences | Compliance-validated playbooks open clinical and research stakeholder access |
IT and Telecommunications leads because enterprise technology deals involve the largest buying committees and the richest technographic signal, making account prioritization directly measurable. Healthcare and Life Sciences grows fastest as pre-validated promotional review workflows remove the legal bottleneck that previously kept pharmaceutical and device vendors out. BFSI sits second by value, applying account programs to long-cycle transformation deals where relationship mapping matters more than reach.
By Organization Size
| Sub-Segment | Key Trend |
|---|---|
| Large Enterprises | Multi-tier one-to-one, one-to-few, and one-to-many motions run concurrently |
| Mid-sized Enterprises | Tiered account-volume pricing and templated playbooks compress time to launch |
| Small Businesses | Self-service editions with pre-built segments lower the entry threshold |
Large Enterprises dominate because only they fund the intent licences, personalization studios, and sales-enablement integrations that full multi-tier programs require. Mid-sized Enterprises grow fastest as entry pricing fell roughly 40% from 2021 levels and onboarding shrank from quarters to weeks. Small Businesses remain a small contributor but validate modular product editions, pushing vendor roadmaps toward capability tiers that scale with program maturity rather than monolithic suites.
By Channel
| Sub-Segment | Key Trend |
|---|---|
| Consent provenance scrutiny reshapes sequencing and deliverability practice | |
| Display Advertising | Account-level programmatic inventory remains the broadest reach mechanism |
| Social Media | Professional network firmographic targeting reaches executive buying committees |
Display Advertising holds the largest allocation because account-level programmatic targeting is mature, inventory is plentiful, and impression-level reporting maps cleanly to account coverage metrics. Social Media grows fastest as professional networks sharpen firmographic precision and senior decision-makers concentrate their attention there. Email continues to carry heavy absolute spend as the conversion channel, though tightening deliverability rules are shifting incremental budget toward channels with documented consent trails.

 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA