Superalloys Market (2026 - 2035)

Superalloys Market Research Report Information By Base Material (Nickel-based, Iron-based, Cobalt-based, and Others (Titanium-based and Niobium-based)), and By End-user Industry (Aerospace and Defense, Power Generation, Oil and Gas, Automotive, Electronics, and Other Industries (Medical Devices, Marine, Chemical, Electronics)) – Forecast Till 2035.
ID: MRFR/CnM/6003-CR 174 Pages Chitranshi Jaiswal Last Updated: September 09, 2026
Superalloys Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)6.69%
2025 Market SizeUSD 31.28 Billion
2035 Market SizeUSD 59.75 Billion
Key Players
Precision Castparts Corp.
Carpenter Technology Corporation
ATI Inc.
Haynes International, Inc.
thyssenkrupp AG
PROTERIAL, Ltd.
Opportunities
  • Powder Metallurgy and Additive Supply Chains
  • Closed-Loop Revert and Recycling Economics
  • Emerging Market Localization

Superalloys Market 摘要

根据市场研究未来的分析,超级合金市场产品形式在2024年的估值为68.929亿美元。声纳浮标行业预计将从2025年的75.3394亿美元增长到2035年的183.3259亿美元,在预测期(2025 - 2035年)内显示出9.3%的年复合增长率(CAGR)。

主要市场趋势和亮点

超级合金市场正受到与航空航天与国防需求、能源转型需求、先进制造、合金材料创新、可持续性和区域供应链重组相关的多个汇聚级趋势的重塑。

  • 石油与天然气行业继续依赖超级合金用于井下工具、井口设备和高压/高腐蚀组件,特别是在深水和酸气田。
  • 增材制造(AM),或金属3D打印,可以说是当今超级合金领域中最具变革性的趋势。
  • 原始设备制造商(OEM)和供应商越来越多地为激光和电子束增材制造工艺认证镍基超级合金,特别是用于涡轮叶片和燃烧室原型以及小批量生产。
  • 材料科学的前沿正在超越传统的镍、铁和钴基超级合金,向高熵合金(HEAs)和其他“下一代”成分发展。

市场规模与预测

2024市场规模 6,892.9(百万美元)
2035市场规模 18,332.59(百万美元)
年均增长率(2025 - 2035) 9.3%

主要参与者

精密铸件公司,Aubert & Duval,HAYNES国际,日立冶金工业株式会社,通用不锈钢(Aperam),VDM金属,Cannon‑Muskegon,CRS控股公司,蒂森克虏伯材料贸易有限公司,阿勒格尼技术公司(ATI)。

Superalloys Market Drivers

航空航天和国防的需求上升

航空航天和国防支出的增加是超级合金市场的一个关键驱动因素,因为这些领域在很大程度上依赖于能够承受极端温度、压力和机械应力的材料。国防支出已超过2718亿美元,反映出地缘政治紧张局势加剧和长期军事现代化努力。这一持续的支出增长支持对高性能材料的需求,这些材料用于飞机发动机、燃气涡轮、海军推进系统和航天平台等领域,而超级合金在这些领域中至关重要。

在发电和石油与天然气行业中日益使用燃气涡轮

在发电和石油与天然气作业中燃气涡轮的日益部署是超级合金市场的一个关键增长驱动因素。燃气涡轮在极高的温度和旋转应力下运行,特别是在联合循环发电厂、海上平台、液化天然气设施和管道压缩系统中。超级合金,特别是以镍为基础的等级,对于涡轮叶片、导向叶片、燃烧室和盘片至关重要,因为它们能够在超过1000°C的温度下保持强度、抵抗蠕变并承受氧化。随着各国投资于可靠和灵活的发电以支持工业增长和能源安全,燃气发电厂因其较低的排放和能够补充可再生能源而越来越受到青睐。这直接推动了对用于高效涡轮组件的先进超级合金的需求。

市场细分洞察

Based on Product Form, the Superalloys Market has been segmented into Cast Ingot, Wrought Superalloys, Powder Metallurgy (PM) Superalloys, Others. Wrought superalloys are increasingly in demand due to their superior mechanical properties, fatigue resistance, and dimensional stability, making them essential for high-performance components in aerospace, power generation, and industrial sectors. Unlike cast alloys, wrought superalloys can be processed into complex shapes such as sheets, plates, and forged parts with controlled microstructure, enabling precise engineering of turbine disks, blades, and high-stress structural components. Powder metallurgy superalloys are increasingly adopted in aerospace, defense, and high-performance industrial applications due to their ability to produce components with superior mechanical properties, fine microstructure, and near-net-shape precision. Nickel-based powders are widely used in turbine blades, disks, and hot-section components, where high-temperature strength, creep resistance, and oxidation tolerance are critical. Cobalt-based powders find application in components subjected to extreme wear, corrosion, and thermal cycling, including combustor liners, vanes, and specialized industrial machinery.

By Application: Aerospace (largest market) vs Power Generation (fastest-Growing)

获取关于Superalloys Market的更多详细见解

区域洞察

North America: Expanding dense cluster of aerospace

North America dominates by value, accounting for about 45–50% of the superalloys market in 2024–2025, with a market size of roughly USD 3.1–3.2 billion and projected growth to over USD 5 billion by the early 2030s at around 7% CAGR. This leadership stems from a dense cluster of aerospace and defense OEMs (Boeing, Lockheed Martin, GE Aviation) and a strong industrial‑gas‑turbine and power‑generation base. The region is also at the forefront of advanced manufacturing, including additive‑manufactured superalloy components and high‑performance turbine systems.

Europe: Strong Production dense cluster of aerospace

Europe is the second‑largest region, valued at about USD 2.18 billion in 2024 and forecast to reach ~USD 3.7 billion by 2032, growing at roughly 6.8% CAGR. Germany leads within Europe, driven by aerospace, premium automotive, and energy‑sector demand for nickel‑ and cobalt‑based superalloys. European manufacturers emphasize innovation, sustainability, and strict quality standards, which supports steady adoption in engines, turbines, and industrial‑machinery components across the EU.

Asia Pacific: Growing dense cluster of aerospace

Asia‑Pacific (APAC) is the most dynamic region, valued at USD 1.78 billion in 2024 and expected to grow to around USD 3.1 billion by 2032, implying a CAGR of about 7.3%. China is the largest APAC market, followed by India, Japan, and South Korea, where demand is being driven by aerospace‑OEM localization, industrial‑gas‑turbines, power plants, and expanding automotive and turbocharger production. APAC is also becoming a center for indigenous superalloy R&D and capacity expansion, particularly in China and India, supported by government‑backed industrial‑modernization programs.

South America: Protection of dense cluster of aerospace

South America is a small but emerging market in the sonobuoy industry, driven by maritime South America is currently the smallest reported regional segment, but it is expected to grow steadily, piggybacking on aerospace‑maintenance, power‑plant modernization, and automotive‑turbocharger demand, particularly in Brazil and Mexico. While detailed market‑size figures are scarcer, the region benefits from spillover demand from North American and European OEMs, as well as regional industrial‑modernization efforts. Overall, South America remains a niche but increasingly relevant node in the superalloys supply and service network.

Middle East & Africa: Emerging dense cluster of aerospace

Middle East & Africa (MEA) represents a smaller but structurally growing segment, valued at USD 311 million in 2024 and projected to reach around USD 515 million by 2032, with a CAGR near 6.5%. Growth is anchored in oil & gas, power generation, and desalination infrastructure, especially in the Gulf Cooperation Council (GCC) states, where high‑temperature and corrosion‑resistant superalloys are used in turbines, compressors, and offshore equipment. North Africa is also gradually increasing its share as energy‑infrastructure projects expand.
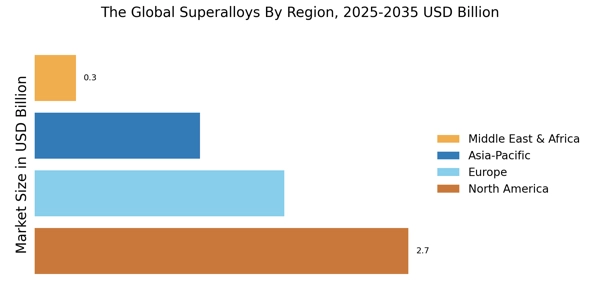
Superalloys Market Regional Image

主要参与者和竞争洞察

超级合金市场的特点是许多全球、区域和地方供应商。市场竞争激烈,所有参与者都在争夺市场份额。激烈的竞争、材料的快速进步、政府政策的频繁变化以及环境法规是影响市场增长的关键因素。供应商在成本、产品质量、可靠性和政府法规方面展开竞争。供应商必须提供具有成本效益的高质量产品,以在竞争激烈的市场中生存和成功。
市场的主要参与者包括精密铸件公司,Aubert & Duval,HAYNES国际,日立冶金工业株式会社,通用不锈钢(Aperam),VDM金属,Cannon‑Muskegon,CRS控股公司,蒂森克虏伯材料贸易有限公司,阿勒格尼技术公司(ATI),战略市场发展和改善运营效率的决策。

Superalloys Market市场的主要公司包括

行业发展

August 2025: EOS expanded its additive manufacturing (AM) material portfolio by introducing nickel-based superalloy powders, EOS IN738 and EOS K500. These materials were integrated into its Laser Beam Powder Bed Fusion (PBF-LB) machines. The EOS Nickel Alloy IN738 and EOS Nickel Alloy K500 became commercially available for the EOS M 290 machine series in December 2024 and are expected to be compatible with the EOS M 400-4 machines in the first half of 2025, enabling advanced applications in high-performance additive manufacturing.

April 2025: Mitsubishi Materials Co., Ltd. launched a new heat-resistant superalloy grade, MV9005, designed for machining nickel-based alloys in the aviation sector. The new grade supports medium finishing processes, where coated inserts provide enhanced tool life, even when only one corner of the insert is used for machining large components.

March 2025: Aubert & Duval’s strategy revolves around material innovation and specialized alloy solutions for aerospace, defense, and energy industries. The company leverages advanced metallurgy capabilities to produce high-strength, high-temperature alloys, targeting clients requiring tailored solutions for extreme conditions. Aubert & Duval enhances its market position through close collaboration with OEMs and engineering partners, enabling customization, rapid prototyping, and just-in-time supply. The company also invests in digitalization and quality management systems to ensure consistent performance and reliability for critical industrial applications.

未来展望

Superalloys Market 未来展望

超级合金市场预计将在2025年至2035年间以9.3%的年均增长率增长,推动因素是对高性能计算和增强安全功能的需求增加。

到2035年,市场预计将实现强劲增长,巩固其作为关键行业的地位。

市场细分

超级合金市场按应用

  • 汽车
  • 发电
  • 石油和天然气
  • 航空航天
  • 其他

超级合金市场按材料类型

  • 镍基
  • 铁基
  • 钴基

超级合金市场按应用前景

  • 航空航天与国防
  • 能源
  • 工业燃气轮机
  • 汽车
  • 石油与天然气
  • 其他

报告范围

Parameter Detail
Market Scope Global Superalloys Market by base material and end-user industry across five regions and 27 countries
Study Period 2021–2035 (Historical 2021–2024; Base Year 2025; Forecast 2026–2035)
CAGR 6.69% (2026–2035)
Market Size Checkpoints USD 31.28 Billion (2025); USD 33.37 Billion (2026); USD 43.23 Billion (2030); USD 59.75 Billion (2035)
Fastest Growing Segments Cobalt-based (Base Material); Electronics (End-user Industry); Europe (Region)
Companies Profiled Precision Castparts, Carpenter Technology, ATI, Haynes International, thyssenkrupp, PROTERIAL, Doncasters, Cannon-Muskegon, Aperam, MIDHANI, Aubert & Duval
Valuation Currency USD Billion, end-user value at current prices

FAQs

How should procurement teams structure long-term supply agreements in the Superalloys Market?
Index pricing to LME nickel with a separate conversion-cost escalator, since melt and remelt energy costs move independently of metal. Lock capacity allocation rather than volume, because furnace slots are the binding constraint [13].
What lead times should buyers plan for premium rotating-grade material?
Vacuum arc remelted bar for rotating applications typically runs 40–60 weeks, and large closed-die forgings extend beyond 80 weeks during peak demand. Order coverage below twelve months invites program disruption [21].
Does the Superalloys Market face meaningful antitrust or export-control exposure?
Yes. Several rotating grades fall under ITAR and EU dual-use controls, requiring licensing for cross-border transfer. Buyers sourcing outside their home jurisdiction should validate classification before contracting [14].
How do single-crystal and directionally solidified castings differ commercially?
Single-crystal castings eliminate grain boundaries entirely, permitting roughly 30–50°C higher operating temperature, but yield rates run materially lower. That yield gap, not raw material, drives the price premium [15].
What integration challenges arise when qualifying a second source in the Superalloys Market?
Statistical allowables must be regenerated from the new supplier's own heats, typically demanding thirty or more lots and eighteen to thirty months. Process equivalence, not chemistry match, governs approval [14].
Are recycled-content claims commercially verifiable in this sector?
Aerospace revert is traceable by heat number, so recycled content is auditable in ways scrap-based claims in other metals are not. European buyers increasingly require this documentation under CSRD reporting [20].
Which emerging use case deserves the most attention from Superalloys Market investors?
Small modular reactor components. Intermediate heat exchangers and control-rod hardware require creep-resistant nickel grades qualified to nuclear codes, a small but high-margin channel opening after 2030 [2].
作者
Author
Author Profile
Chitranshi Jaiswal LinkedIn Team Lead - Research
Chitranshi is a Team Leader in the Chemicals & Materials (CnM) and Energy & Power (EnP) domains, with 6+ years of experience in market research. She leads and mentors teams to deliver cross-domain projects that equip clients with actionable insights and growth strategies. She is skilled in market estimation, forecasting, competitive benchmarking, and both primary & secondary research, enabling her to turn complex data into decision-ready insights. An engineer and MBA professional, she combines technical expertise with strategic acumen to solve dynamic market challenges. Chitranshi has successfully managed projects that support market entry, investment planning, and competitive positioning, while building strong client relationships. Certified in Advanced Excel & Power BI she leverages data-driven approaches to ensure accuracy, clarity, and impactful outcomes.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of regulatory filings, industry technical standards, commodity trade databases, and specialized aerospace & defense publications. Key sources included the US Federal Aviation Administration (FAA) certification databases, European Union Aviation Safety Agency (EASA) type certificates, US Department of Defense (DoD) procurement records & Defense Logistics Agency (DLA) strategic material reports, US Geological Survey (USGS) Mineral Commodity Summaries for nickel, cobalt, and refractory metals, US Department of Energy (DOE) Oak Ridge National Laboratory (ORNL) advanced materials research, National Institute of Standards and Technology (NIST) metallurgical standards, Bureau of Industry and Security (BIS) export control classifications, Aerospace Industries Association (AIA) manufacturing statistics, SAE International (Society of Automotive Engineers) standards databases, ASM International (American Society for Metals) technical journals, International Air Transport Association (IATA) fleet forecasts, Energy Industries Council (EIC) power generation infrastructure data, International Nickel Study Group (INSG) supply statistics, Cobalt Institute production reports, and national aviation authorities from key markets including China's CAAC, Russia's FATA, and Brazil's ANAC.

For nickel-based, cobalt-based, iron-based, and developing refractory metal superalloys, these sources were used to gather production statistics, aerospace order books, defense material specifications, raw material pricing trends, melt shop capacity data, and regulatory clearance procedures.


Primary Research

To gather both qualitative and quantitative insights, supply-side and demand-side stakeholders were interviewed during the primary research process. CEOs, vice presidents of metallurgy, chief technology officers, heads of regulatory compliance, and commercial directors from precision casters, integrated superalloy producers, and makers of specialty mill products were examples of supply-side sources. Chief metallurgists from industrial gas turbine manufacturers, supply chain executives from oilfield services firms, maintenance directors from commercial aviation MRO facilities, procurement leads from defense contractors, and chief engineers from aerospace OEMs (airframers and engine manufacturers) were examples of demand-side sources. Primary research verified additive manufacturing qualification timescales, established market segmentation between wrought and cast forms, and obtained information on long-term supply agreements, strategic stockpile dynamics, and raw material hedging tactics.

Primary Respondent Breakdown:

• By Designation: C-level Primaries (32%), Director Level (35%), Others (33%)

• By Region: North America (32%), Europe (28%), Asia-Pacific (32%), Rest of World (8%)


Market Size Estimation

Bill-of-materials (BOM) quantification for end-use applications and capacity utilization analysis were used to determine the global market valuation. The following were part of the methodology:

• More than 35 major manufacturers from North America, Europe, Asia-Pacific, and developing Eastern European specialty alloy producers were identified.

• Product mapping between powder metallurgy superalloy categories, nickel-based (Inconel, Rene, Nimonic series), cobalt-based (Haynes, Stellite alloys), and iron-based (A-286, Incoloy).

• Examination of modeled aerospace alloy allocations from Tier 1 suppliers and reported segment revenues

• Manufacturers that will account for 75–80% of the world's superalloy melt capacity in 2024

• Extrapolation by base metal composition and manufacturing process (wrought, conventionally cast, directionally solidified, single crystal, powder metallurgy) to derive segment-specific valuations using top-down (primary metal producer revenue validation adjusted for value-add processing) and bottom-up (aircraft engine deliveries × alloy content per engine + industrial gas turbine installations × alloy tonnage per turbine) approaches

下载免费样本

请填写以下表格以获取本报告的免费样本

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.
















