Smart Doorbell Market

智能门铃市场规模、份额和研究报告按类型(有线门铃和无线门铃)、组件(硬件和软件)、最终用户(住宅和商业)、销售渠道(基于商店和非基于商店)和地区(北美、欧洲、亚太和其他地区) - 行业预测至2035年
ID: MRFR/SEM/7155-HCR 100 Pages Ankit Gupta, Shubham Munde Last Updated: September 19, 2026
Smart Doorbell Market
Market Size
Forecast Period2025 - 2035
CAGR (2025 - 2035)17.19%
2024 Market Size$ 2.52 Million
2025 Market Size$ 3.01 Million
2035 Market Size$ 22.93 Million
Key Players
Ring
Nest
Arlo
Eufy
August
RemoBell
Opportunities
  • Market Growth Projections
  • Rising Demand for Home Security Solutions
  • Growing Urbanization and Population Density

Smart Doorbell Market 摘要

根据MRFR的分析,智能门铃市场规模在2024年预计为252万美元。智能门铃行业预计将从2025年的301万美元增长到2035年的2293万美元,在2025年至2035年的预测期内,年均复合增长率(CAGR)为17.19%。

主要市场趋势和亮点

智能门铃市场正在经历强劲增长,推动因素包括技术进步和消费者对安全解决方案需求的增加。

  • 智能门铃与更广泛的智能家居生态系统的集成在北美变得越来越普遍。
  • 增强的安全功能是主要关注点,特别是在家庭安全领域,该领域仍然是最大的市场。
  • 可持续性和能源效率正在获得关注,尤其是在亚太地区,该地区是增长最快的市场。
  • 对家庭安全解决方案的需求上升以及智能门铃功能的技术进步是推动市场增长的关键因素。

市场规模与预测

2024市场规模 2.52(百万美元)
2035市场规模 22.93(百万美元)
年均增长率(2025 - 2035) 17.19%

主要参与者

Ring(美国),Nest(美国),Arlo(美国),Eufy(中国),August(美国),RemoBell(美国),TMEZON(美国),Amcrest(美国),SkyBell(美国)

Smart Doorbell Market Drivers

市场增长预测

全球智能门铃市场预计在未来几年将经历显著增长。预计到2024年市场价值为12.5亿美元,该行业将显著扩展,预计到2035年达到256亿美元。这一增长轨迹表明,从2025年到2035年,复合年增长率(CAGR)将达到31.58%。这样的预测表明,消费者对智能门铃的强烈需求,推动因素包括技术进步、城市化加速和安全关注的增加。市场的扩展反映了家庭安全解决方案的不断演变以及智能技术的日益融合。

对家庭安全解决方案的需求上升

全球智能门铃市场经历了对增强家庭安全解决方案的显著需求激增。随着房主越来越重视安全,配备了视频监控和运动检测功能的智能门铃变得至关重要。这一趋势通过预计到2024年市场价值为12.5亿美元得到了强调,反映出消费者对智能家居技术的日益倾向。双向音频和云存储等先进功能的整合进一步增强了这些设备的吸引力,使其成为注重安全的消费者的首选。因此,随着更多家庭采用这些创新解决方案,该行业有望实现显著增长。

城市化和人口密度的增长

城市化和日益增加的人口密度对全球智能门铃市场产生了显著影响。随着越来越多的人迁移到城市地区,对增强安全解决方案的需求变得至关重要。智能门铃为应对人口密集环境所带来的挑战提供了实用的解决方案,在这些环境中,传统的安全措施可能无法满足需求。远程监控的便利性以及能够随时与访客互动的能力为城市居民提供了安心。这一人口结构的变化可能会推动对智能门铃的需求,因为城市居民寻求创新解决方案以在日益拥挤的居住条件中增强家庭安全。

智能家居生态系统的日益普及

全球智能门铃市场受益于全面智能家居生态系统的日益普及。随着消费者寻求各种智能设备的无缝集成,智能门铃作为这些生态系统的关键组成部分。与其他智能设备(如安全摄像头和智能锁)连接的能力提升了整体用户体验。这种互联性不仅提高了便利性,还提升了家庭内的安全措施。随着越来越多的消费者投资于智能家居技术,预计对智能门铃的需求将上升,进一步推动行业发展,并促成2025年至2035年间预计的31.58%的复合年增长率。

智能家居设备的技术进步

技术进步在推动全球智能门铃市场中发挥了关键作用。人工智能、机器学习和改进的连接选项等创新显著增强了智能门铃的功能。这些进步使得面部识别和实时警报等功能变得越来越吸引消费者。随着市场的发展,制造商可能会采用尖端技术来区分其产品。这种对创新的关注预计将有助于行业的预期增长,预计到2035年市场价值将达到256亿美元,表明这一轨迹受到持续技术进步的推动。

消费者对智能技术的认知和教育

消费者对智能技术的认知和教育是推动全球智能门铃市场的关键因素。随着个人对智能家居设备的好处(包括能源效率和增强的安全性)了解得越来越多,智能门铃的采用预计将上升。制造商和行业协会的教育举措在揭开这些技术的神秘面纱方面发挥了重要作用,使其对普通消费者更加可及。这种日益增长的认知可能会转化为销售和市场增长的增加,因为消费者认识到将智能门铃集成到家庭中的价值。

市场细分洞察

获取关于Smart Doorbell Market的更多详细见解

区域洞察

北美:智能门铃市场的领导者

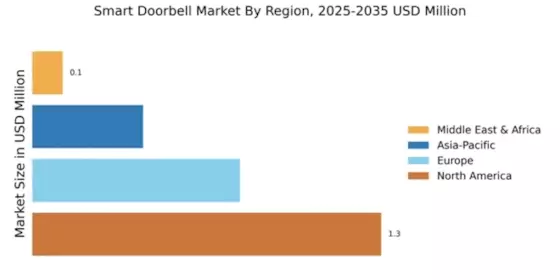
北美继续在智能门铃市场中领先,拥有12.6亿美元的显著份额。增长受到消费者对家庭安全解决方案需求增加、技术进步和有利的监管框架的推动。智能家居的普及和门铃中AI功能的集成是推动市场扩张的关键趋势。此外,政府倡导智能家居技术的举措进一步促进了市场增长。北美的竞争格局强劲,Ring、Nest和Arlo等主要参与者主导市场。这些公司不断创新,推出面部识别和双向音频等新功能。美国市场尤其强劲,得益于智能设备的高渗透率。随着消费者对安全解决方案的意识提高,成熟品牌和新进入者的存在预计将加剧竞争,推动该领域的进一步发展。

欧洲:具有增长潜力的新兴市场

欧洲对智能门铃的兴趣日益增长,市场规模为7.5亿美元。需求受到城市化加速、安全问题上升和向智能家居技术转变的推动。对节能和安全家庭解决方案的监管支持也是增长的催化剂。德国和英国等国家在这一趋势中处于领先地位,消费者越来越重视家庭中的智能安全功能。欧洲的竞争格局由成熟品牌和新兴参与者混合构成。Eufy和August等公司正在获得关注,提供针对欧洲消费者的创新解决方案。市场还看到科技公司与安全服务提供商之间的合作,增强产品供应。随着该地区拥抱智能家居技术,主要参与者的存在预计将扩大,进一步推动市场增长。

亚太地区:智能技术的快速增长

亚太地区正在成为智能门铃市场的重要参与者,市场规模为4亿美元。增长受到可支配收入增加、城市化和对家庭安全解决方案意识提高的推动。中国和日本等国处于前沿,消费者越来越多地采用智能技术。政府倡导智能城市项目的举措也在推动市场扩张,为智能门铃的采用创造了有利环境。亚太地区的竞争格局多样化,本地和国际参与者争夺市场份额。Eufy和其他地区品牌正在获得人气,提供价格合理且功能丰富的产品。随着消费者偏好向集成智能家居解决方案转变,主要参与者的存在预计将增长。随着市场成熟,创新和竞争定价将是这一快速发展的市场成功的关键。

中东和非洲:具有未开发潜力的新兴市场

中东和非洲地区在采用智能门铃技术的早期阶段,市场规模为1.1亿美元。增长受到城市化加速、安全问题上升和中产阶级增长的推动。随着越来越多的消费者寻求先进的安全解决方案,智能门铃的需求预计将上升。旨在增强智能城市基础设施的政府倡议也在推动市场增长,为该领域的创新创造机会。该地区的竞争格局仍在发展,本地和国际参与者混合进入市场。公司正专注于教育消费者了解智能门铃的好处,这对市场渗透至关重要。随着意识的提高和技术的可及性增强,主要参与者的存在预计将扩大,推动智能门铃市场的进一步增长。

Smart Doorbell Market Regional Image

主要参与者和竞争洞察

The Smart Doorbell Market is currently characterized by a dynamic competitive landscape, driven by technological advancements and increasing consumer demand for home security solutions. Major players such as Ring (US), Nest (US), and Arlo (US) are at the forefront, each adopting distinct strategies to enhance their market presence. Ring (US) focuses on innovation through continuous product enhancements and integration with smart home ecosystems, while Nest (US) leverages its strong brand reputation and Google’s backing to expand its product offerings. Arlo (US) emphasizes user-friendly designs and advanced features, positioning itself as a leader in high-definition video quality and cloud storage solutions. Collectively, these strategies contribute to a competitive environment that is increasingly centered around technological differentiation and customer-centric innovations. Key business tactics within the Smart Doorbell Market include localizing manufacturing and optimizing supply chains to enhance efficiency and reduce costs. The market structure appears moderately fragmented, with several key players holding substantial market shares while numerous smaller companies also compete. This fragmentation allows for a diverse range of products and price points, catering to various consumer preferences and needs. The collective influence of these key players shapes market dynamics, as they continuously innovate and adapt to changing consumer demands. In November 2025, Ring (US) announced the launch of its latest smart doorbell model, which features enhanced AI capabilities for facial recognition and package detection. This strategic move is significant as it not only reinforces Ring's commitment to innovation but also addresses growing consumer concerns regarding package theft, thereby potentially increasing its market share. The integration of advanced AI technology positions Ring to better compete against rivals by offering unique features that enhance user experience and security. In October 2025, Nest (US) unveiled a new subscription service that provides users with enhanced cloud storage options and advanced analytics for their doorbell cameras. This initiative is strategically important as it not only generates recurring revenue but also strengthens customer loyalty by offering added value. By enhancing its service offerings, Nest aims to differentiate itself in a crowded market, appealing to consumers who prioritize data security and accessibility. In September 2025, Arlo (US) entered into a partnership with a leading home automationplatform to integrate its smart doorbells with a broader range of smart home devices. This collaboration is crucial as it expands Arlo's ecosystem, allowing users to seamlessly connect their doorbells with other smart devices. Such strategic alliances are likely to enhance Arlo's competitive positioning by providing a more comprehensive solution for consumers seeking integrated smart home experiences. As of December 2025, current competitive trends in the Smart Doorbell Market are heavily influenced by digitalization, sustainability, and AI integration. The emphasis on strategic alliances is reshaping the landscape, enabling companies to leverage complementary strengths and enhance their product offerings. Looking ahead, competitive differentiation is expected to evolve, with a notable shift from price-based competition towards innovation, technology, and supply chain reliability. Companies that prioritize these aspects are likely to gain a competitive edge in an increasingly sophisticated market.

Smart Doorbell Market市场的主要公司包括

Recent Industry Developments

Q3 2026: Ring (US): Ring updated the names of multiple doorbell models between July 21 and August 5, 2026, introducing 2K and 4K resolution identifiers while retaining existing features, helping standardize product positioning and communicate video-resolution capabilities more clearly.

Q3 2026: SkyBell (US): SkyBell introduced customizable Modes and Schedules on September 2, enabling users to control recording, notifications, and indoor chime behavior by device and time interval, expanding operational flexibility for smart doorbell deployments.

According to a news published in 2024, Xalient’s customer, Abode, a leading provider of DIY smart home security solutions, has been recognized for their innovative new product, the Abode Edge Camera. The Abode Edge Camera has Xailient AI running inside it which can observe things like package delivery or people who do not belong there and filter out regular activities such as family members coming and going or natural movements that simple cameras may mistake for something else.

In 2022 Google released the 2nd generation wired Nest Doorbell. Google's second-generation Nest Doorbell has a wire which gives it an advantage over its battery-powered ones; it is approximately thirty percent smaller than its predecessor’s wired variant.

In December 2021, Irida Labs, a European AI vision solution provider, partnered with Hikvision.

In November 2021, Latch, Inc. announced a partnership with Marks USA, as well as Town Steel, Inc., coupled with another imminent partnership with dormakaba Holding AG. These series of developments are expected to increase the adoption of LatchOS among new visitors, tenants as well as property managers.

Vivint Smart Home Inc made an announcement that in July 2021 it entered into a strategic alliance with Freedom Forever.
未来展望

Smart Doorbell Market 未来展望

智能门铃市场预计在2025年至2035年期间以17.19%的年均增长率增长,推动因素包括技术进步、安全关注增加和智能家居集成。

到2035年,市场预计将强劲,反映出显著的增长和创新。

市场细分

智能门铃市场最终用户展望

  • 住宅
  • 商业
  • 机构

智能门铃市场特征展望

  • 视频录制
  • 双向音频
  • 运动检测
  • 夜视

智能门铃市场技术展望

  • 无线网络
  • 有线
  • 电池供电
  • 智能手机集成

智能门铃市场应用展望

  • 家庭安全
  • 包裹递送
  • 访客通知
  • 远程监控

智能门铃市场价格范围展望

  • 经济型
  • 中档
  • 高端

报告范围

2024年市场规模 252(万美元)
2025年市场规模 301(万美元)
2035年市场规模 2293(万美元)
年均复合增长率(CAGR) 17.19%(2025 - 2035)
报告覆盖范围 收入预测、竞争格局、增长因素和趋势
基准年 2024
市场预测期 2025 - 2035
历史数据 2019 - 2024
市场预测单位 万美元
关键公司简介 Ring(美国),Nest(美国),Arlo(美国),Eufy(中国),August(美国),RemoBell(美国),TMEZON(美国),Amcrest(美国),SkyBell(美国)
覆盖的细分市场 应用、技术、最终用户、功能、价格范围
关键市场机会 人工智能的集成增强了智能门铃市场的安全功能。
关键市场动态 消费者对增强安全功能的需求上升,推动智能门铃市场的创新和竞争。
覆盖的国家 北美、欧洲、亚太、南美、中东和非洲
<

Frequently Asked Questions

智能门铃市场目前的估值是多少?

截至2024年,智能门铃市场的估值为25.20亿美元。

到2035年,智能门铃市场的预计市场规模是多少?

智能门铃市场预计到2035年将达到229.30亿美元的估值。

在预测期内,智能门铃市场的预期年均增长率是多少?

智能门铃市场在2025年至2035年期间的预期年均增长率为17.19%。

哪些公司被认为是智能门铃市场的关键参与者?

智能门铃市场的关键参与者包括Ring、Nest、Arlo、Eufy、August、RemoBell、TMEZON、Amcrest和SkyBell。

推动智能门铃市场的主要应用是什么?

主要应用包括家庭安全、包裹递送、访客通知和远程监控,其中家庭安全以100.00亿美元领先。

智能门铃市场按技术如何细分?
市场按技术细分为Wi-Fi、有线、电池供电和智能手机集成,其中Wi-Fi以100.00亿美元占主导地位。
智能门铃市场的最终用户细分是什么?
最终用户细分包括住宅、商业和机构,其中住宅以100.00亿美元领先。
智能门铃中最受欢迎的功能是什么?
关键功能包括视频录制、双向音频、运动检测和夜视,每项功能的估值为45.80亿美元。
智能门铃市场按价格范围如何细分?
市场细分为预算、中档和高档类别,其中中档和高档的估值分别为91.60亿美元和101.90亿美元。
哪些趋势正在影响智能门铃市场的增长?
家庭安全需求增加和技术进步等趋势可能会推动智能门铃市场的增长。
作者
Author Author Profile Ankit Gupta LinkedIn Team Lead - Research
Ankit Gupta is a seasoned market intelligence and strategic research professional with over six plus years of experience in the ICT and Semiconductor industries. With academic roots in Telecom, Marketing, and Electronics, he blends technical insight with business strategy. Ankit has led 200+ projects, including work for Fortune 500 clients like Microsoft and Rio Tinto, covering market sizing, tech forecasting, and go-to-market strategies. Known for bridging engineering and enterprise decision-making, his insights support growth, innovation, and investment planning across diverse technology markets.
Co-Author Co-Author Profile Shubham Munde LinkedIn Team Lead - Research
Shubham brings over 7 years of expertise in Market Intelligence and Strategic Consulting, with a strong focus on the Automotive, Aerospace, and Defense sectors. Backed by a solid foundation in semiconductors, electronics, and software, he has successfully delivered high-impact syndicated and custom research on a global scale. His core strengths include market sizing, forecasting, competitive intelligence, consumer insights, and supply chain mapping. Widely recognized for developing scalable growth strategies, Shubham empowers clients to navigate complex markets and achieve a lasting competitive edge. Trusted by start-ups and Fortune 500 companies alike, he consistently converts challenges into strategic opportunities that drive sustainable growth.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of regulatory databases, consumer electronics standards, IoT security publications, and authoritative smart home industry organizations. Key sources included the Federal Communications Commission (FCC), European Telecommunications Standards Institute (ETSI), Consumer Technology Association (CTA), Security Industry Association (SIA), Electronic Security Association (ESA), Zigbee Alliance/Connectivity Standards Alliance, Z-Wave Alliance, Institute of Electrical and Electronics Engineers (IEEE Xplore), UL Solutions (Underwriters Laboratories), International Electrotechnical Commission (IEC), US Census Bureau (Housing and Homeownership Statistics), EU Eurostat Digital Economy and Society Database, National Institute of Standards and Technology (NIST) Cybersecurity Framework, US International Trade Commission (USITC), UN Comtrade Database, Consumer Product Safety Commission (CPSC), National Smart Home Standards initiatives from key markets, and smart city regulatory authorities from APAC and Middle East regions. These sources were used to collect device certification data, wireless communication standards compliance, smart home adoption statistics, IoT security protocols, household formation trends, and competitive landscape analysis for video doorbell systems, wireless connectivity technologies, cloud storage platforms, and AI-integrated security hardware.


Primary Research

In the primary research process, supply-side and demand-side stakeholders were interviewed to obtain qualitative and quantitative insights. Supply-side sources included CEOs, CTOs, VPs of IoT Product Development, heads of hardware engineering, cloud infrastructure directors, and commercial directors from smart doorbell manufacturers, smart home OEMs, and IoT security solution providers. Demand-side sources comprised smart home system integrators, security installation professionals, real estate developers, property management directors, procurement leads from consumer electronics retailers and e-commerce platforms, and risk management professionals from home insurance sectors. Primary research validated market segmentation across wired and wireless technologies, confirmed AI feature development roadmaps, and gathered insights on installation ecosystem dynamics, subscription service monetization models, and smart home interoperability standards.

Primary Respondent Breakdown:

By Designation: C-level Primaries (32%), Director Level (35%), Others (33%)

By Region: North America (38%), Europe (25%), Asia-Pacific (28%), Rest of World (9%)


Market Size Estimation

Global market valuation was derived through unit shipment analysis and average selling price (ASP) modeling across hardware and subscription services. The methodology included:

Identification of 40+ key manufacturers across North America, Europe, Asia-Pacific, and Middle East, spanning pure-play video doorbell companies, traditional security firms transitioning to smart hardware, and consumer electronics conglomerates

Product mapping across wired doorbells, wireless/battery-powered doorbells, hardware components (cameras, sensors, processors), and software/cloud subscription services

Analysis of reported and modeled annual revenues specific to smart doorbell and connected home security portfolios, including recurring revenue from cloud storage and AI feature subscriptions

Coverage of manufacturers representing 65-70% of global market share in 2024

Extrapolation using bottom-up (unit shipments × ASP by country plus cloud service attach rates) and top-down (manufacturer revenue validation and channel checks with distributors) approaches to derive segment-specific valuations for residential versus commercial end-users and store-based versus non-store-based sales channels

下载免费样本

请填写以下表格以获取本报告的免费样本

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.