Process Automation Instrumentation Market

过程自动化和仪器市场规模、份额及研究报告(按仪器(现场仪器、控制阀和分析仪)、按解决方案(APC、DCS、HMI、MES、PLC和安全自动化与SCADA)、按行业(化学、能源与电力、食品与饮料)以及按地区(北美、欧洲、亚太和其他地区)- 行业预测至2035年
ID: MRFR/SEM/4064-CR 100 Pages Nirmit Biswas, Aarti Dhapte Last Updated: September 23, 2026
Process Automation Instrumentation Market
Market Size
Forecast Period2025 - 2035
CAGR (2025 - 2035)5.7%
2024 Market Size$ 4.2 Billion
2025 Market Size$ 4.44 Billion
2035 Market Size$ 7.73 Billion
Key Players
Siemens
Rockwell Automation
Honeywell
Schneider Electric
Emerson Electric
ABB
Opportunities
  • Rising Demand for Efficiency
  • Technological Advancements in Automation
  • Regulatory Compliance and Safety Standards

Process Automation Instrumentation Market 摘要

主要市场趋势和亮点

市场规模与预测

CAGR (2025 - 2035) 5.7%

主要参与者

Siemens (DE), Rockwell Automation (US), Honeywell (US), Schneider Electric (FR), Emerson Electric (US), ABB (CH), Mitsubishi Electric (JP), Yokogawa Electric (JP), Endress+Hauser (CH)

Process Automation Instrumentation Market Drivers

对效率的需求上升

过程自动化和仪器市场正在经历对增强操作效率的显著需求激增。各行业越来越多地采用自动化解决方案来简化流程、降低运营成本并提高生产力。根据最近的数据,实施过程自动化的组织可以实现高达30%的效率提升。这一趋势在制造和能源行业尤为明显,自动化技术正在被整合以优化生产线和能源管理系统。随着公司努力保持竞争力,对效率的关注可能会推动对自动化技术的进一步投资,从而推动过程自动化和仪器市场的增长。

自动化技术的进步

技术进步在塑造过程自动化和仪器市场中发挥着关键作用。人工智能、机器学习和先进机器人等创新正在彻底改变传统的自动化流程。这些技术使实时数据分析和预测性维护成为可能,从而显著增强操作的可靠性。例如,人工智能在自动化系统中的集成允许更智能的决策和改进的过程控制。随着各行业越来越认识到这些技术的潜力,对复杂自动化解决方案的需求预计将上升,进一步推动过程自动化和仪器市场的增长。

合规性和安全标准

过程自动化和仪器市场还受到对合规性和遵循安全标准需求的推动。制药、食品和饮料以及化学等行业受到严格法规的约束,这些法规要求对流程进行精确监控和控制。自动化解决方案提供了确保遵守这些法规所需的工具,从而降低罚款风险并提高产品质量。对安全和质量保证的日益重视可能会推动自动化技术的采用,因为公司寻求降低与不合规相关的风险。这一趋势突显了自动化在维护过程自动化和仪器市场行业标准中的重要性。

对智能制造的投资增加

过程自动化和仪器市场正在见证对智能制造倡议的投资增加。公司正在认识到智能工厂的潜力,这些工厂利用互联设备和自动化技术来提高生产效率和灵活性。这一向智能制造的转变是由于生产过程中对更大定制化和更快响应时间的需求。根据行业报告,未来几年对智能制造技术的投资预计将达到可观的数字。随着组织努力采用更灵活的制造实践,支持智能制造的自动化解决方案的需求可能会增加,从而进一步推动过程自动化和仪器市场的增长。

对数据驱动决策的关注增加

对数据驱动决策的重视正在显著影响过程自动化和仪器市场。组织越来越多地利用数据分析来获取操作性能的洞察并做出明智的决策。实时收集和分析大量数据的能力使公司能够识别低效并优化流程。这一趋势在制造和物流等行业尤为明显,在这些行业中,数据分析可以带来可观的成本节省和改善的操作结果。随着企业继续优先考虑数据驱动的战略,预计对促进数据收集和分析的先进自动化解决方案的需求将增长,从而增强过程自动化和仪器市场。

市场细分洞察

In the Process Automation and Instrumentation Market, Field Instruments represent the largest segment, capturing a significant share due to their extensive application across various industries such as oil and gas, chemical, and pharmaceutical. Control Valves and Analyzers follow, but with a notably smaller market presence in the Process Automation and Instrumentation Market. Field Instruments encompass a wide range of devices essential for measurement and monitoring, making them indispensable for optimizing processes and maintaining efficiency. Meanwhile, Analyzers are rapidly gaining traction, driven by the rising demand for precise measurement solutions and quality assurance in production processes.

In the Process Automation and Instrumentation Market, the Distribution Control System (DCS) stands out as the largest segment, holding a significant portion of the overall market share. DCS is widely adopted due to its efficiency in managing complex industrial processes, offering extensive control features that appeal to various industries. In contrast, Human-Machine Interfaces (HMI) have emerged as the fastest-growing segment, primarily driven by the increasing demand for user-friendly interfaces in automation systems. This shift is propelled by advancements in technology that enhance usability and connectivity across various platforms. The growth of the HMI segment exemplifies an evolving market trend where user experience is prioritized. Factors such as the rising adoption of Industry 4.0, which focuses on smart manufacturing and real-time data monitoring, have catalyzed the demand for HMIs. As industries seek to optimize operations and enhance workforce productivity, HMI solutions are rapidly being integrated with IoT capabilities, further fueling their growth trajectory. In contrast, DCS remains robust, driven by the ongoing transformation in traditional manufacturing settings towards more integrated and automated systems.

In the Process Automation and Instrumentation Market, the Chemicals sector remains dominant due to its complex and hazardous nature, necessitating the implementation of automation for safety and efficiency. This industry extensively uses advanced sensors and control systems to optimize operations, reduce waste, and ensure compliance with environmental regulations. Conversely, the Food & Beverages sector is emerging rapidly, fueled by the increasing demand for automation to enhance food safety, maintain quality, and improve tracking in production lines. Trends like the adoption of Industry 4.0 and smart manufacturing are propelling this sector towards a more automated future.

获取关于Process Automation Instrumentation Market的更多详细见解

区域洞察

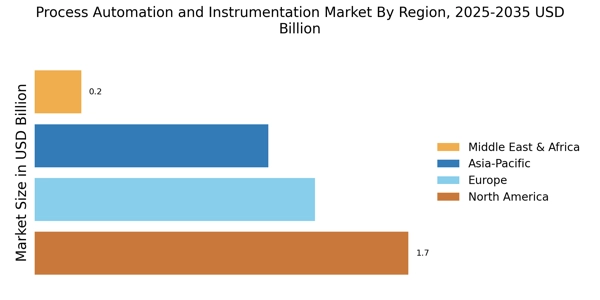
根据地区,研究提供了北美、欧洲、亚太地区和其他地区的市场洞察。2022年,北美过程自动化和仪器市场占据了17亿美元的份额,预计在研究期间将展现出显著的CAGR增长。美国以其创新能力而闻名,并在第四次工业革命的尖端技术方面处于领先地位。

此外,过程自动化和仪器市场报告中研究的主要国家包括:美国、加拿大、德国、法国、英国、意大利、西班牙、中国、日本、印度、澳大利亚、韩国和巴西。

欧洲过程自动化和仪器市场在2022年的预测期内占据第二大市场份额。该地区对过程自动化和仪器市场的需求预计将受到对提高运营效率、更高安全性和新技术进步的日益增长的需求的推动。欧盟中自动化程度最高的经济体在德国。德国目前约有230,000台工业机器人在运行。2020年,仅有22,300台新设备投入使用。

因此,德国工业使用的工业机器人数量约是意大利工厂的三倍(截至2021年为78,200台)、法国工厂的五倍(截至2021年为44,800台)和英国工厂的十倍(截至2021年为23,000台)。此外,德国过程自动化和仪器市场占据了最大的市场份额,而英国过程自动化和仪器市场在欧洲地区是增长最快的市场。

亚太地区的过程自动化和仪器市场预计将在2024年至2032年期间以最快的CAGR增长。这是由于政府项目对自动化技术的日益关注、广泛的国内制造和信息技术的发展。此外,中国的过程自动化和仪器市场占据了最大的市场份额,而印度的过程自动化和仪器市场在亚太地区是增长最快的市场。

例如,印度的过程自动化和仪器市场将在预测期内以亚太地区最快的CAGR增长。由于工业公司对降低成本和提高效率的关注增加,过程自动化和仪器市场正在显著扩展。由于生产力的提高和错误率的降低,过程自动化和仪器行业正在扩展。Gesrepair的帖子声称,全球制造公司正在投资现代制造技术,并做出明智的决策以改善其生产过程。

因此,全球过程自动化和仪器市场正在扩展,因为工业公司强调实现成本节约和更高效率。

Process Automation Instrumentation Market Regional Image

主要参与者和竞争洞察

The major market players are increasing their investments in their research and development departments to increase their product portfolios. They also focus on introducing various market developments such as new product launches, contractual agreements, mergers and acquisitions, increased investments, and collaboration with other organizations to widen their consumer base. Studies indicate that the Process Automation and Instrumentation industry is expected to decrease prices to appeal to a wider consumer base.One of the primary business strategies manufacturers adopt in the Process Automation and Instrumentation industry is to introduce regional and local manufacturing to keep their prices at a moderate pace. The Process Automation and Instrumentation market major player such as ABB Ltd (Switzerland), General Electric Co. (U.S), Mitsubishi Electric Corporation (Japan), Rockwell Automation Inc. (U.S), Emerson Electric Co. (U.S), and others are working to expand the market demand by investing in research and development activities.Swedish-Swiss multinational company ABB Ltd. has its headquarters in Zürich, Switzerland. Allmänna Svenska Elektriska Aktiebolaget (ASEA) of Sweden and Brown, Boveri & Cie of Switzerland combined in 1988 to establish ASEA Brown Boveri, which was eventually abbreviated to ABB. Both businesses were founded in the late 1800s and produced significant electrical equipment; ABB is still involved in this industry today. Since then, the business has also branched into robotics and automation technology. It has been a Fortune 500 company for 24 years and is currently rated 341 on the Fortune 500 list of 2018.ABB was the largest industrial employer in Switzerland up to the sale of its Power Grids segment in 2020.The General Electric Company (GE) is a worldwide business headquartered in Boston and was established in the United States in 1892. The business engages in venture capital and finance as well as aviation, power, renewable energy, the digital sector, and additive manufacturing. According to gross revenue, GE was the 33rd-largest company in the United States according to the Fortune 500 in 2020. GE was the 14th most profitable business in the Fortune 20 in 2011, but when its profitability declined, it significantly underperformed the market (by nearly 75%).Irving Langmuir (1932) and Ivar Giaever (1973), both GE employees, were given the Nobel Prize. The business intended to split into three investment-grade public entities on November 9, 2021.

Process Automation Instrumentation Market市场的主要公司包括

Recent Industry Developments

  • Q3 2026: Siemens (DE): Siemens announced a unified Automation organization combining Factory Automation, Motion Control, Customer Services and Process Automation, strengthening the organizational structure supporting industrial automation and process-control technologies.

  • Q3 2026: Rockwell Automation (US): Rockwell Automation and Cytiva launched Figurate SCADA for biopharmaceutical manufacturing, providing connectivity across multiple instrument vendors and modalities to integrate process data and automation systems.

  • Q3 2026: Schneider Electric (FR): Schneider Electric published an updated EcoStruxure Process Instrumentation catalog covering pressure, flow, level, temperature, analytical and valve-positioning instruments, providing an expanded reference for industrial measurement and process-control applications.

  • Q3 2026: Yokogawa Electric (JP): Yokogawa announced orders from Kawasaki Heavy Industries for integrated automation systems for a liquefied-hydrogen carrier and hydrogen-fueled vessels, extending process automation and instrumentation capabilities into hydrogen transport applications.

  • Q2 2024: ABB to acquire Siemens’ low voltage NEMA motor business ABB announced the acquisition of Siemens’ low voltage NEMA motor business, expanding its automation and instrumentation portfolio for industrial process customers. The deal is expected to strengthen ABB’s position in the North American market.
  • Q2 2024: Rockwell Automation Completes Acquisition of Clearpath Robotics Rockwell Automation completed its acquisition of Clearpath Robotics, a developer of autonomous mobile robots, to enhance its process automation solutions for manufacturing and industrial customers.
  • Q2 2024: Emerson Announces New DeltaV Automation Platform Release Emerson launched a new version of its DeltaV automation platform, featuring advanced process control and instrumentation capabilities aimed at improving operational efficiency in process industries.
  • Q1 2024: Honeywell Launches Experion PKS Release 520 for Process Automation Honeywell introduced Experion PKS Release 520, an updated process automation system with enhanced cybersecurity and digital integration features for industrial customers.
  • Q2 2024: Schneider Electric to open new smart manufacturing facility in India Schneider Electric announced the opening of a new smart manufacturing facility in India, focused on producing process automation and instrumentation solutions for global markets.
  • Q1 2024: Yokogawa and JSR Corporation to Jointly Develop AI-based Process Control System Yokogawa Electric Corporation and JSR Corporation announced a partnership to jointly develop an AI-based process control system for chemical manufacturing, aiming to improve automation and efficiency.
  • Q2 2024: Siemens and NVIDIA Announce Partnership to Advance Industrial Automation Siemens and NVIDIA announced a strategic partnership to integrate NVIDIA’s AI technology into Siemens’ process automation platforms, targeting enhanced real-time data analytics and process optimization.
  • Q1 2024: ABB wins $120 million automation contract for Middle East oil refinery ABB secured a $120 million contract to provide process automation and instrumentation systems for a major oil refinery project in the Middle East.
  • Q2 2024: Emerson Acquires Fluxa to Expand Life Sciences Automation Portfolio Emerson acquired Fluxa, a provider of process knowledge management software, to strengthen its automation and instrumentation offerings for the life sciences sector.
  • Q1 2024: Rockwell Automation and Microsoft Expand Partnership to Accelerate Industrial Automation Innovation Rockwell Automation and Microsoft expanded their partnership to co-develop cloud-based process automation solutions, leveraging Microsoft Azure for industrial customers.
  • Q2 2024: Honeywell to acquire Compressor Controls Corporation for $670 million Honeywell announced the acquisition of Compressor Controls Corporation, a provider of turbomachinery control and optimization solutions, to enhance its process automation portfolio.
  • Q1 2024: Schneider Electric Launches EcoStruxure Automation Expert 23.0 Schneider Electric launched EcoStruxure Automation Expert 23.0, a new version of its universal automation system designed to improve flexibility and efficiency in process industries.

未来展望

Process Automation Instrumentation Market 未来展望

预计过程自动化和仪器市场将在2025年至2035年间以5.7%的年均增长率增长,推动因素包括技术进步、效率需求增加和法规合规。

到2035年,过程自动化和仪器市场预计将实现强劲增长,反映出行业需求的演变和技术创新。

市场细分

过程自动化仪器市场终端用户展望

  • 化学
  • 能源与电力
  • 食品与饮料

过程自动化仪器市场解决方案展望

  • APC
  • DCS
  • HMI
  • MES
  • PLC
  • 安全自动化与SCADA

过程自动化仪器市场仪器展望

  • 现场仪器
  • 控制阀
  • 分析仪

报告范围

MARKET SIZE 2024 4.2(USD Billion)
MARKET SIZE 2025 4.439(USD Billion)
MARKET SIZE 2035 7.728(USD Billion)
COMPOUND ANNUAL GROWTH RATE (CAGR) 5.7% (2025 - 2035)
REPORT COVERAGE Revenue Forecast, Competitive Landscape, Growth Factors, and Trends
BASE YEAR 2024
Market Forecast Period 2025 - 2035
Historical Data 2019 - 2024
Market Forecast Units USD Billion
Key Companies Profiled Siemens (DE), Rockwell Automation (US), Honeywell (US), Schneider Electric (FR), Emerson Electric (US), ABB (CH), Mitsubishi Electric (JP), Yokogawa Electric (JP), Endress+Hauser (CH)
Segments Covered Instrument, Solution, Surgery, Region
Key Market Opportunities Integration of artificial intelligence in Process Automation and Instrumentation Market enhances operational efficiency and decision-making.
Key Market Dynamics Rising demand for automation technologies drives innovation and competition in the Process Automation and Instrumentation Market.
Countries Covered North America, Europe, APAC, South America, MEA

Frequently Asked Questions

2035年过程自动化和仪器市场的预计市场估值是多少?

2035年过程自动化和仪器市场的预计市场估值为77.28亿美元。

2024年过程自动化和仪器市场的整体市场估值是多少?

2024年过程自动化和仪器市场的整体市场估值为42亿美元。

2025年至2035年期间,过程自动化和仪器市场的预期年复合增长率(CAGR)是多少?

2025年至2035年期间,过程自动化和仪器市场的预期年复合增长率为5.7%。

哪些公司被认为是过程自动化和仪器市场的关键参与者?

过程自动化和仪器市场的关键参与者包括西门子、罗克韦尔自动化、霍尼韦尔、施耐德电气、艾默生电气、ABB、三菱电气、横河电机和恩德斯哈瑟。

到2035年,仪器细分市场中的现场仪器预计价值是多少?

到2035年,仪器细分市场中的现场仪器预计价值将达到28亿美元。

到2035年,控制阀细分市场预计价值是多少?

到2035年,控制阀细分市场预计价值为22亿美元。

到2035年,仪器细分市场中分析仪的预期市场规模是多少?
到2035年,仪器细分市场中分析仪的预期市场规模预计为27亿美元。
到2035年,解决方案类别中DCS细分市场的预计价值是多少?
到2035年,解决方案类别中DCS细分市场的预计价值将达到20亿美元。
到2035年,食品和饮料终端用户细分市场的预期市场规模是多少?
到2035年,食品和饮料终端用户细分市场的预期市场规模预计为27亿美元。
到2035年,解决方案细分市场中安全自动化和SCADA的预计价值是多少?
到2035年,解决方案细分市场中安全自动化和SCADA的预计价值将达到7.28亿美元。
作者
Author Author Profile Nirmit Biswas LinkedIn Senior Research Analyst
With 5+ years of expertise in Market Intelligence and Strategic Research, Nirmit Biswas specializes in ICT, Semiconductors, and BFSI. Backed by an MBA in Financial Services and a Computer Science foundation, Nirmit blends technical depth with business acumen. He has successfully led 100+ projects for global enterprises and startups, including Amazon, Cisco, L&T and Huawei, delivering market estimations, competitive benchmarking, and GTM strategies. His focus lies in transforming complex data into clear, actionable insights that drive growth, innovation, and investment decisions. Recognized for bridging engineering innovation with executive strategy, Nirmit helps businesses navigate dynamic markets with confidence.
Co-Author Co-Author Profile Aarti Dhapte LinkedIn AVP - Research
A consulting professional focused on helping businesses navigate complex markets through structured research and strategic insights. I partner with clients to solve high-impact business problems across market entry strategy, competitive intelligence, and opportunity assessment. Over the course of my experience, I have led and contributed to 100+ market research and consulting engagements, delivering insights across multiple industries and geographies, and supporting strategic decisions linked to $500M+ market opportunities. My core expertise lies in building robust market sizing, forecasting, and commercial models (top-down and bottom-up), alongside deep-dive competitive and industry analysis. I have played a key role in shaping go-to-market strategies, investment cases, and growth roadmaps, enabling clients to make confident, data-backed decisions in dynamic markets.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of industrial automation databases, peer-reviewed engineering journals, technical publications, and authoritative industry organizations. Key sources included the International Society of Automation (ISA.org), Institute of Electrical and Electronics Engineers (IEEE), International Electrotechnical Commission (IEC), National Institute of Standards and Technology (NIST), Occupational Safety and Health Administration (OSHA), US Department of Energy (DOE), International Energy Agency (IEA), Process Automation Users Group (PAUG), American National Standards Institute (ANSI), European Committee for Electrotechnical Standardization (CENELEC), VDMA (German Engineering Federation), Japan Electrical Manufacturers' Association (JEMA), China Instrument and Control Society (CIS), International Federation of Automatic Control (IFAC), FieldComm Group, OPC Foundation, ARC Advisory Group, MarkLines Automotive Industry Portal, US Bureau of Labor Statistics, Eurostat Industrial Production Database, and national industrial ministry reports from key manufacturing markets. These sources were used to collect industrial automation adoption statistics, regulatory compliance data, safety certification studies, productivity trends, and competitive landscape analysis for field instruments, control valves, distributed control systems, programmable logic controllers, and other automation technologies.
 

Primary Research

Qualitative and quantitative insights were obtained by interviewing supply-side and demand-side stakeholders during the primary research process. CEOs, VPs of Engineering, global product leaders, and strategic sales directors from process automation instrumentation manufacturers, system integrators, and component suppliers comprised the supply-side sources. Plant managers, automation engineers, control system specialists, maintenance supervisors, procurement directors, and automation engineers from oil and gas refineries, chemical processing plants, power generation facilities, food and beverage manufacturing units, and pharmaceutical production sites comprised demand-side sources. Market segmentation was validated, technology roadmap timelines were confirmed, and insights regarding cybersecurity implementation dynamics, total cost of ownership strategies, and digital transformation adoption patterns were obtained through primary research.

Primary Respondent Breakdown:

By Designation: C-level Primaries (32%), Director Level (31%), Others (37%)

By Region: North America (32%), Europe (30%), Asia-Pacific (31%), Rest of World (7%)


Market Size Estimation

Global market valuation was derived through revenue mapping and installation base analysis. The methodology included:

Identification of 50+ key manufacturers across North America, Europe, Asia-Pacific, and Latin America

Product mapping across field instruments (pressure, temperature, flow, level transmitters), control valves, analyzers, DCS, PLC, SCADA, HMI, MES, APC, and safety automation systems

Analysis of reported and modeled annual revenues specific to process automation portfolios

Coverage of manufacturers representing 75-80% of global market share in 2024

Extrapolation using bottom-up (installed base × service revenue by industry vertical) and top-down (manufacturer revenue validation) approaches to derive segment-specific valuations

下载免费样本

请填写以下表格以获取本报告的免费样本

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.