Privileged Access Management Solutions Market

特权访问管理(PAM)解决方案市场研究报告:按类型(软件、物理设备和虚拟设备)、按应用(Windows、Unix & Linux、Mac OS、基础设施设备和物联网)以及按地区(北美、欧洲、亚太和其他地区) - 预测市场到2035年。
ID: MRFR/ICT/8753-CR 123 Pages Ankit Gupta, Shubham Munde Last Updated: September 19, 2026
Privileged Access Management Solutions Market
Market Size
Forecast Period2025 - 2035
CAGR (2025 - 2035)24.21%
2024 Market Size$ 4.09 Billion
2025 Market Size$ 5.08 Billion
2035 Market Size$ 44.41 Billion
Key Players
CyberArk
BeyondTrust
Thycotic
Delinea
IBM
ManageEngine
Opportunities
  • Adoption of Remote Work Policies
  • Increasing Cybersecurity Threats
  • Digital Transformation Initiatives

Privileged Access Management Solutions Market 摘要

主要市场趋势和亮点

市场规模与预测

CAGR (2025 - 2035) 24.21%

主要参与者

CyberArk(IL), BeyondTrust (US), Thycotic (US), Delinea (US), IBM (US), ManageEngine (IN), One Identity (US), SailPoint (US)

Privileged Access Management Solutions Market Drivers

远程工作政策的采用

远程工作政策的采用正在重塑特权访问管理(PAM)解决方案市场的格局。随着大量员工远程工作,组织面临与远程访问敏感系统相关的更高风险。这一转变要求实施强大的PAM解决方案,以确保特权账户的安全管理,无论用户的位置如何。随着远程工作在许多组织中成为永久性特征,对PAM技术的需求预计将上升。公司可能会投资于提供安全访问控制和监控能力的解决方案,从而增强其在远程工作环境中的安全态势。

网络安全威胁的增加

网络安全威胁的增加是特权访问管理(PAM)解决方案市场的主要驱动因素。组织越来越多地成为复杂网络攻击的目标,这些攻击通常利用特权账户。根据最近的数据,超过80%的数据泄露涉及被盗用的凭证。这个令人担忧的统计数据突显了强大PAM解决方案的必要性,以保护敏感信息和关键系统。随着组织认识到此类泄露可能造成的财务和声誉损害,对PAM技术的投资可能会激增。预计PAM解决方案市场将显著增长,因为企业优先考虑保护其特权账户,从而增强整体安全态势。

数字化转型倡议

数字化转型倡议正在显著影响特权访问管理(PAM)解决方案市场的增长。随着组织采用数字技术以提高运营效率和客户参与度,安全访问管理的需求变得至关重要。云服务、物联网设备和移动应用的整合引入了新的脆弱性,如果管理不当,可能会被利用。因此,组织越来越多地投资于PAM解决方案,以保护其数字资产,并确保只有授权人员可以访问关键系统。随着企业认识到通过有效的访问管理策略保护其数字化转型努力的重要性,PAM解决方案市场可能会见证显著增长。

合规要求

合规要求是推动特权访问管理(PAM)解决方案市场的关键因素。各个行业的组织都受到严格法规的约束,这些法规要求保护敏感数据和管理访问控制。GDPR、HIPAA和PCI DSS等合规框架要求组织实施有效的PAM解决方案,以避免巨额罚款和法律后果。这些法规日益复杂,迫使组织采用确保合规并降低风险的PAM技术。因此,预计PAM解决方案市场将扩大,因为企业寻求将其访问管理实践与合规要求对齐,从而促进责任和透明文化。

对内部威胁的日益关注

对内部威胁的日益关注是推动特权访问管理(PAM)解决方案市场的关键驱动因素。组织越来越认识到威胁可能来自内部,无论是出于恶意意图还是无意行为。内部威胁可能导致重大数据泄露和财务损失,促使组织采用监控和控制特权访问的PAM解决方案。对用户活动和访问模式的全面可见性的需求变得愈加明显。因此,PAM解决方案市场可能会经历增长,因为企业寻求通过有效的访问管理策略来降低内部风险,从而增强安全性和责任感。

市场细分洞察

按类型:软件(最大)与物理设备(增长最快)

在特权访问管理(PAM)解决方案市场中,软件细分市场作为市场份额的最大贡献者,显著超越其他细分市场的价值。随着企业越来越认识到先进安全措施的必要性,提供灵活、可扩展和高效访问控制的软件解决方案已成为首选。对远程工作和基于云的服务的日益依赖进一步巩固了软件在市场中的地位。相比之下,物理设备细分市场虽然较小,但正在迅速崛起。优先考虑高安全环境和合规要求的组织正在推动PAM物理设备的采用,认识到其有形属性和专用安全措施是有效访问管理的重要组成部分。

技术:软件(主导)与物理设备(新兴)

在PAM解决方案市场中,软件细分市场由于其灵活性、易于集成和广泛的功能而占据主导地位。它满足各类组织的需求,提供会话管理、密码保护和详细审计功能等基本特性。这种适应性对于满足现代企业多样化的访问需求至关重要。相反,物理设备领域作为新兴细分市场正在获得动力,特别受到那些要求严格合规和增强安全的组织的青睐。这些设备提供硬件系统独特提供的强大安全措施,并与软件功能结合,确保全面的PAM战略。尽管仍处于早期阶段,物理设备的增长轨迹表明市场动态的显著变化。

按应用:Windows(最大)与Unix & Linux(增长最快)

在特权访问管理(PAM)解决方案市场中,应用细分市场在其价值分布上展示了显著的多样性。Windows系统领跑,因其在企业中的广泛使用而占据最大份额。这一强大的立足点得益于安全功能的不断增强,提供全面的覆盖。然而,Unix & Linux正迅速获得关注,因为越来越多的组织认识到在其独特环境中需要强大的PAM解决方案,这表明市场动态的显著变化。

Windows(主导)与Unix & Linux(新兴)

Windows仍然是PAM解决方案市场中的主导应用,主要是因为其在金融、医疗和政府等各个行业的广泛采用。它受益于与现有系统的先进集成能力以及丰富的工具生态系统,这些工具增强了安全性。相比之下,Unix & Linux系统被标记为该领域的新兴参与者。它们的增长受到混合和多云环境使用增加的推动,在这些环境中,独特的生产需求要求专门的PAM解决方案来满足其复杂的架构。

获取关于Privileged Access Management Solutions Market的更多详细见解

区域洞察

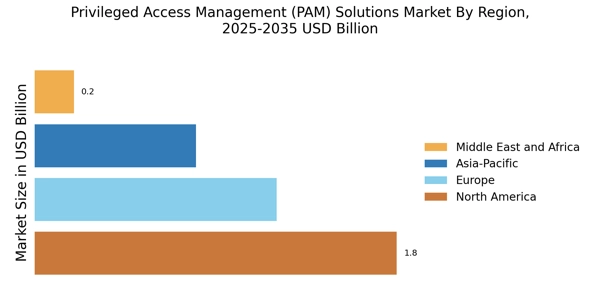
根据地区,报告提供了北美、欧洲、亚太地区和其他地区的市场洞察。北美的特权访问管理(PAM)解决方案市场将主导该市场。由于北美拥有更多的工业和商业实体,要求更高的数据保护量。由于该地区自雇和初创企业的增加,特权访问管理(PAM)解决方案市场得到了扩展。在美国,2022年将有3020万家小型企业。

此外,市场报告中研究的主要国家包括美国、加拿大、法国、德国、意大利、英国、西班牙、日本、中国、澳大利亚、印度、韩国和巴西。

图4:2022年特权访问管理(PAM)解决方案市场份额按地区划分(亿美元)

欧洲的特权访问管理(PAM)解决方案市场占据第二大市场份额,原因是对德国、意大利、西班牙等国家的安全和合规性的担忧。该地区特权访问管理(PAM)解决方案市场受到整个欧盟通用数据保护条例(GDPR)要求的推动。中小企业的增长推动了该地区对特权访问管理解决方案的需求,以遵守相关规定。

此外,德国的特权访问管理(PAM)解决方案市场占据了主要市场份额,而英国的特权访问管理(PAM)解决方案市场是该地区增长最快的市场。

亚太地区的特权访问管理(PAM)解决方案市场预计将在2023年至2032年间快速扩展。运营数字化的增长、互联网渗透率的提高、许多中小企业实施此类系统以及数字基础设施的快速发展都是推动亚太地区特权访问管理(PAM)解决方案市场发展的因素。此外,中国的特权访问管理(PAM)解决方案市场占据了主要市场份额,而印度的特权访问管理(PAM)解决方案市场是亚太地区增长最快的市场。

Privileged Access Management Solutions Market Regional Image

主要参与者和竞争洞察

Leading market players are largely investing in research and development to expand their product lines, which will help the privileged access management (PAM) solutions market, grow even more. The launch of new products, larger-scale mergers and acquisitions, contractual agreements, and collaboration with other organizations are significant market developments in which market participants engage to increase their presence. The privileged access management (PAM) solutions industry must provide affordable products to expand and thrive in a more competitive and challenging market environment.
One of the major business strategies manufacturers use in the privileged access management (PAM) solutions industry to increase market sector and benefits customers is local manufacturing to lower operational costs. In recent years, the privileged access management (PAM) solutions industry has stipulated some of the most important medicinal benefits. Major players in the privileged access management (PAM) solutions market, including Hitachi ID Systems, ARCON, Centrify, CA Technologies, and others, are attempting to increase market demand by heavily investing in research and development operations.
CyberArk Software Ltd offers information technology security solutions to protect the company's data, infrastructure, and assets. The company's software solutionswere centered on safeguarding credentials, privileged accounts, and secrets. Its products and services include Privileged Session Manager, Privileged Threat Analytics, Enterprise Password Vault, and CyberArk Privilege Cloud.
In May CyberArk Software Ltd., a US-based provider of privileged access control systems, acquired IDaptive Holdings Inc. for an undisclosed sum.
Through this acquisition, CyberArk Software Ltd. seeks to enhance its capacity to manage and secure identities with varied degrees of privileges across hybrid and multi-cloud systems to give customers an efficient and seamless user experience in supplying security.
Centrify is now Delinea, a leading provider of privileged access management (PAM) solutions for the modern, hybrid enterprise. They let businesses secure essential data, devices, code, and cloud infrastructure, reducing risk, ensuring compliance, and simplifying security. Delinea simplifies and specifies access boundaries for thousands of consumers worldwide.
In September Centrify Privilege Service, a cloud-based privileged access security solution, now supports hybrid IT systems (on-premises and cloud). CPS complements and extends the flagship Centrify Server Suite's broad capabilities for identity consolidation, privilege management, and privileged session auditing by providing shared account password management for servers, network devices, and Infrastructure-as-a-Service (IaaS).
Privileged Access Management Solutions Market市场的主要公司包括

Recent Industry Developments

Q3 2026: Delinea (US): Delinea introduced runtime authorization capabilities for AI agents, enabling policy enforcement on agent actions before execution and extending privileged-access controls across databases, SSH hosts, Kubernetes, cloud consoles, and MCP servers.

Q3 2026: ManageEngine (IN): ManageEngine PAM360 added Azure Cloud Services Discovery, enabling automated discovery and onboarding of privileged Azure resources and associated accounts while centralizing visibility and management of cloud-based privileged access.

Q3 2026: One Identity (US): One Identity partnered with READI to extend governance to legacy and specialized applications, combining identity governance, PAM, and automated provisioning controls to address access-management gaps across previously difficult-to-connect systems.

Q3 2026: SailPoint (US): SailPoint launched unified identity protection with Human Fabric and Agentic Fabric, adding real-time privilege discovery, just-in-time provisioning, and controls for human, machine, and AI-agent identities.

Q2 2025: Saviynt Named Market Leader in PAM at Global InfoSec Awards 2025 Saviynt was recognized as the Market Leader in Privileged Access Management (PAM) by Cyber Defense Magazine at the 13th Annual Global InfoSec Awards during RSA Conference 2025, following its 2024 win for Best Solution – PAM for Cloud Infrastructure.

未来展望

Privileged Access Management Solutions Market 未来展望

特权访问管理(PAM)解决方案市场预计在2025年至2035年期间以24.21%的年均增长率增长,推动因素包括网络安全威胁的增加和合规要求的提升。

到2035年,PAM解决方案市场预计将强劲增长,反映出显著的增长和创新。

市场细分

特权访问管理解决方案市场类型展望

  • 软件
  • 物理设备
  • 虚拟设备

特权访问管理解决方案市场应用展望

  • Windows
  • Unix 和 Linux
  • Mac OS
  • 基础设施设备
  • 物联网

报告范围

MARKET SIZE 2024 4.09(USD Billion)
MARKET SIZE 2025 5.08(USD Billion)
MARKET SIZE 2035 44.41(USD Billion)
COMPOUND ANNUAL GROWTH RATE (CAGR) 24.21% (2025 - 2035)
REPORT COVERAGE Revenue Forecast, Competitive Landscape, Growth Factors, and Trends
BASE YEAR 2024
Market Forecast Period 2025 - 2035
Historical Data 2019 - 2024
Market Forecast Units USD Billion
Key Companies Profiled CyberArk (IL), BeyondTrust (US), Thycotic (US), Delinea (US), IBM (US), ManageEngine (IN), One Identity (US), SailPoint (US)
Segments Covered Type, Application, Region
Key Market Opportunities Integration of artificial intelligence enhances security and efficiency in the Privileged Access Management (PAM) Solutions Market.
Key Market Dynamics Rising regulatory requirements drive demand for advanced Privileged Access Management solutions across various industries.
Countries Covered North America, Europe, APAC, South America, MEA

Frequently Asked Questions

特权访问管理(PAM)解决方案市场的当前市场估值是多少?

特权访问管理(PAM)解决方案市场的市场估值在2024年为40.9亿美元。

到2035年,PAM解决方案的预计市场规模是多少?

预计到2035年,PAM解决方案的市场规模将达到444.1亿美元。

在预测期内,PAM解决方案市场的预期年均增长率(CAGR)是多少?

预计2025年至2035年,PAM解决方案市场的年均增长率为24.21%。

哪些公司被视为PAM解决方案市场的关键参与者?

PAM解决方案市场的关键参与者包括CyberArk、BeyondTrust、Thycotic、Delinea、IBM、ManageEngine、One Identity和SailPoint。

市场上主要有哪些类型的PAM解决方案?

主要的PAM解决方案类型包括软件、物理设备和虚拟设备。

在2024年,软件细分市场的市场估值表现如何?

在2024年,软件细分市场的估值为16.3亿美元。

2024年物理设备细分市场的市场估值是多少?
2024年物理设备细分市场的估值为12.2亿美元。
哪些应用程序推动了PAM解决方案市场的发展?
推动PAM解决方案市场的主要应用程序包括Windows、Unix和Linux、Mac OS、基础设施设备和物联网。
2024年Unix和Linux应用细分市场的市场估值是多少?
2024年Unix和Linux应用细分市场的估值为10亿美元。
到2035年,物联网应用细分市场的预计增长是多少?
物联网应用细分市场预计到2035年将增长到64.1亿美元。
作者
Author Author Profile Ankit Gupta LinkedIn Team Lead - Research
Ankit Gupta is a seasoned market intelligence and strategic research professional with over six plus years of experience in the ICT and Semiconductor industries. With academic roots in Telecom, Marketing, and Electronics, he blends technical insight with business strategy. Ankit has led 200+ projects, including work for Fortune 500 clients like Microsoft and Rio Tinto, covering market sizing, tech forecasting, and go-to-market strategies. Known for bridging engineering and enterprise decision-making, his insights support growth, innovation, and investment planning across diverse technology markets.
Co-Author Co-Author Profile Shubham Munde LinkedIn Team Lead - Research
Shubham brings over 7 years of expertise in Market Intelligence and Strategic Consulting, with a strong focus on the Automotive, Aerospace, and Defense sectors. Backed by a solid foundation in semiconductors, electronics, and software, he has successfully delivered high-impact syndicated and custom research on a global scale. His core strengths include market sizing, forecasting, competitive intelligence, consumer insights, and supply chain mapping. Widely recognized for developing scalable growth strategies, Shubham empowers clients to navigate complex markets and achieve a lasting competitive edge. Trusted by start-ups and Fortune 500 companies alike, he consistently converts challenges into strategic opportunities that drive sustainable growth.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of cybersecurity frameworks, threat intelligence databases, industry analyst reports, and authoritative technology publications. Key sources included the National Institute of Standards and Technology (NIST), Cybersecurity and Infrastructure Security Agency (CISA), European Union Agency for Cybersecurity (ENISA), International Organization for Standardization (ISO/IEC 27001/62443), UK National Cyber Security Centre (NCSC), Australian Cyber Security Centre (ACSC), MRFR Research, MRFR Research, MRFR, MRFR, Verizon Data Breach Investigations Report (DBIR), IBM Security Cost of a Data Breach Report, MITRE ATT&CK Framework, and SANS Institute publications. These sources were used to collect threat landscape statistics, regulatory compliance requirements (GDPR, HIPAA, PCI DSS, SOX, NIS2), enterprise IAM adoption trends, breach incident data, and competitive intelligence for cloud-native PAM, on-premises solutions, and hardware security modules (HSMs).


Primary Research

Qualitative and quantitative insights were obtained by interviewing supply-side and demand-side stakeholders during the primary research process. The supply-side sources consisted of CEOs, CTOs, VPs of Product Management, Chief Revenue Officers, and channel strategy chiefs from pure-play PAM vendors, diversified cybersecurity conglomerates, and managed security service providers (MSSPs). Chief Information Security Officers (CISOs), Vice Presidents of Identity and Access Management, Chief Information Officers, enterprise architects, and procurement leads from Fortune 1000 enterprises, critical infrastructure operators, financial institutions, healthcare systems, and government agencies comprised demand-side sources. Market segmentation was validated across deployment models (cloud vs. on-premises), product roadmap timelines for AI-driven privileged analytics were confirmed, and insights on the adoption patterns of zero-trust architecture, enterprise license pricing dynamics, and competitive displacement trends were gathered through primary research.

Primary Respondent Breakdown:

By Designation: C-level Executives (32%), Director Level (33%), Others (35%)

By Region: North America (38%), Europe (28%), Asia-Pacific (24%), Rest of World (10%)


Market Size Estimation

Global market valuation was derived through revenue mapping and enterprise deployment volume analysis. The methodology included:

Identification of 35+ key PAM vendors across North America, Europe, Asia-Pacific, and Middle East

Product mapping across software (cloud/SaaS and on-premises), physical appliances (hardware security modules), and virtual appliances

Analysis of reported and modeled annual revenues specific to privileged access management portfolios, including session management, password vaulting, and endpoint privilege management

Coverage of vendors representing 75-80% of global market share in 2024

Extrapolation using bottom-up (enterprise endpoint counts × average selling price by deployment type and region) and top-down (vendor revenue triangulation) approaches to derive segment-specific valuations for Windows, Unix/Linux, Mac OS, infrastructure device, and IoT application environments

下载免费样本

请填写以下表格以获取本报告的免费样本

Global Diameter Signaling Market
案例研究
Information and Communications Technology
Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.