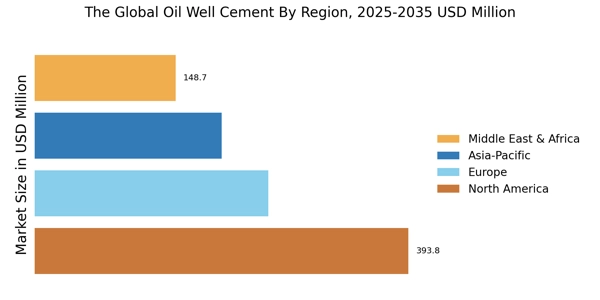
The global market valuation was triangulated by conducting a value-chain revenue analysis specific to oilfield cement consumption and modeling volume consumption. The methodology consisted of the following:
Identification of over 50 specialized cement manufacturers and oilfield service companies in North America, the Gulf Cooperation Council (GCC), the North Sea, Latin America, and the Asia-Pacific region
Product mapping for API Spec 10A categories (Class A, B, C, G, H) and specialty systems (salt-water-resistant, foamed, resin-based, and flexible formulations) An examination of the reported segment revenues that are attributed to primary and secondary (remedial) cementing from prominent oilfield service providers and dedicated cementing contractors
Supply-side entities that account for 75-80% of the global oil well cement consumption in 2024 are included in the coverage.
Extrapolation through a bottom-up approach (regional active rig count × average wells drilled per rig × average cement sacks per well type × composite average selling price per metric ton) was cross-validated with a top-down approach (total reported cementing services market).



 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA


