Integration Platform as a Service Market (2026 – 2035)

集成平台即服务(IPaaS)市场规模、份额和研究报告,按部署模型(公共云、混合云)、按最终用户垂直行业(银行、金融服务与保险、医疗保健与生命科学、制造业、信息技术与电信)、按组织规模(大型企业、中小型企业)、按服务类型(应用集成、数据/ETL集成、API与事件集成) - 行业预测至2035年。
ID: MRFR/ICT/4072-HCR 100 Pages Ankit Gupta, Aarti Dhapte Last Updated: September 15, 2026
Integration Platform as a Service (IPaaS) Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)19.50%
2025 Market SizeUSD 8.46 Billion
2035 Market SizeUSD 43.82 Billion
Key Players
Microsoft
Informatica
MuleSoft
Boomi
Workato
SAP Integration Suite
Opportunities
  • Vertical iPaaS for Regulated Industries
  • SME Penetration via Consumption-Based Pricing
  • Data Monetization and API Marketplaces

Integration Platform as a Service (IPaaS) Market Summary

The Integration Platform as a Service Market reached an estimated USD 8.46 Billion in 2025, with the forecast period beginning at USD 10.08 Billion in 2026 and climbing to USD 43.82 Billion by 2035 at a CAGR of 19.50%. Enterprises across every vertical are under pressure to unify fragmented SaaS estates, IoT telemetry streams, and edge computing nodes — and that pressure translates into sustained platform spending. The EU's Data Act, which mandates cross-border data portability by 2027, and the US CHIPS and Science Act's downstream digital infrastructure provisions are two policy catalysts channeling investment into cloud middleware solutions and enterprise cloud connectivity [2][3].

A technology shift is accelerating the Integration Platform as a Service Market: hand-coded point-to-point links and on-premises ESBs are giving way to intelligent, policy-aware integration fabrics. GenAI-powered design assistants now auto-generate data mappings, reducing connector development time by 40–60% according to industry benchmarks [4]. Event-driven architectures built on Apache Kafka and cloud-native pub/sub services are replacing batch ETL pipelines, letting organizations process real-time data across hybrid estates. Global enterprise spending on iPaaS cloud integration surpassed USD 7.2 Billion in 2024, underscoring the momentum behind API integration platforms .

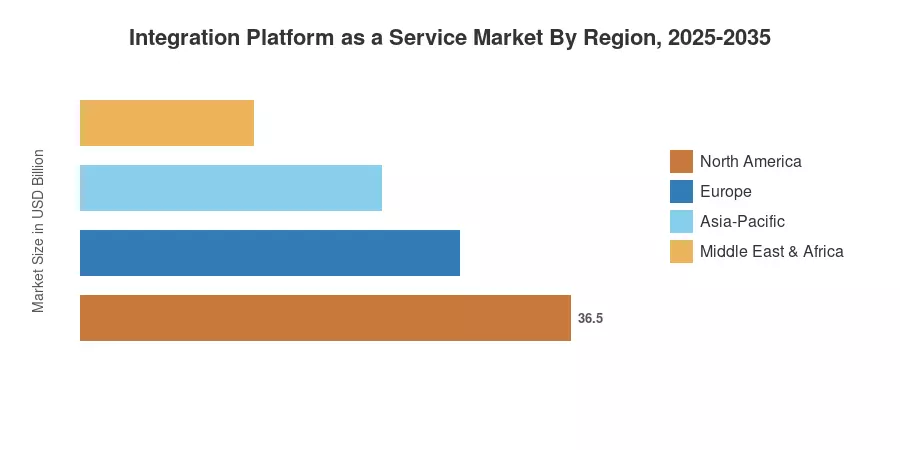
North America commanded roughly 48.70% of the Integration Platform as a Service Market in 2025, anchored by hyperscaler ecosystems and mature SaaS adoption. Asia-Pacific is the fastest-growing region at a projected 25.40% CAGR, driven by manufacturing modernization across China, India, and ASEAN economies Europe holds the second-largest share at approximately 24.10%, where sovereign-cloud mandates and GDPR-driven data residency requirements continue to fuel demand for compliant SaaS integration tools. The next decade will reward platform vendors that combine multi-cloud openness with vertical-specific compliance modules.


Key Report Takeaways

• By Deployment Model

  • Public Cloud dominated the Integration Platform as a Service Market with 75.20% revenue share in 2025, reflecting enterprise preference for consumption-based cloud middleware solutions
  • Hybrid Cloud deployment is forecast to compound at a 29.80% CAGR through 2035, as data residency regulations push enterprises toward split-workload architectures for enterprise cloud connectivity

• By End-User Vertical

  • BFSI accounted for 23.10% of the Integration Platform as a Service Market in 2025, driven by open-banking API mandates and real-time fraud detection pipelines
  • Healthcare and Life Sciences are advancing at a 32.50% CAGR, fueled by interoperability standards such as HL7 FHIR and cross-system EHR integration

• By Region

  • North America led the Integration Platform as a Service Market at USD 4.12 Billion in 2025, with the US alone representing over 78% of regional revenue
  • Asia-Pacific is projected to reach USD 14.35 Billion by 2035, as consumption-based pricing opens iPaaS cloud integration to SMEs across emerging economies


Market Size and Forecast (2021–2035)

MRFR's proprietary estimation framework triangulates vendor revenues, enterprise IT spending surveys, and API traffic proxy data to construct bottom-up market sizing. Historical figures (2021–2024) rely on audited annual reports and validated third-party datasets; forecast values (2026–2035) apply the calibrated 19.50% CAGR with adjustments for macroeconomic and regulatory variables.
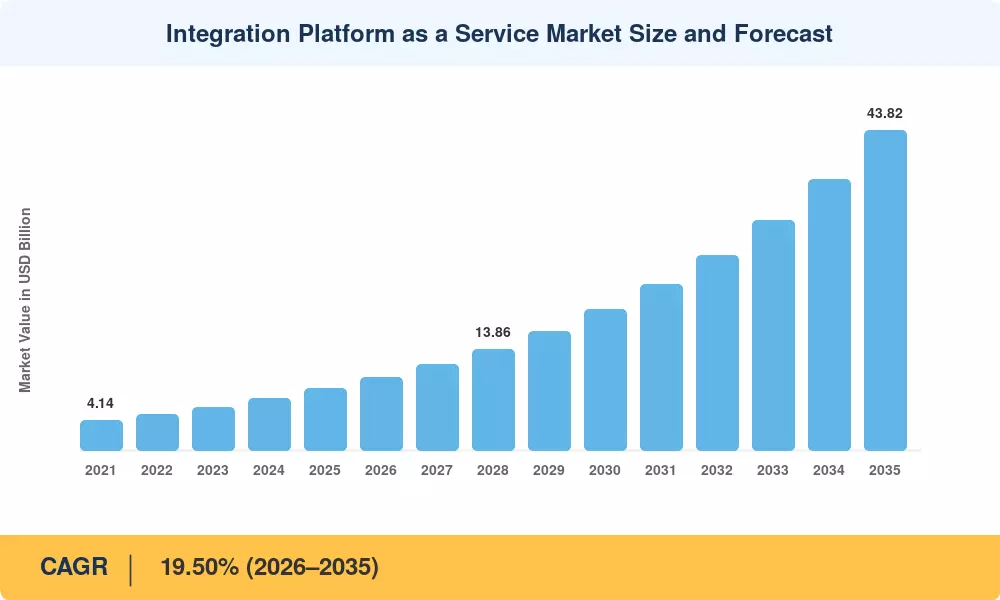
Integration Platform as a Service Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry


Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
SaaS proliferation & API-first mandates 22% Global Short-term (≤2 yr)
GenAI-powered integration design 18% North America, Europe Medium-term (2–4 yr)
Sovereign-cloud & data residency regulations 15% Europe, APAC Medium-term (2–4 yr)
Healthcare interoperability mandates 12% North America, Europe Short-term (≤2 yr)
IoT & edge computing convergence 14% APAC, North America Long-term (≥4 yr)
SME consumption-based pricing models 10% APAC, South America Medium-term (2–4 yr)
Open-banking & real-time payments 9% Global Short-term (≤2 yr)


SaaS Proliferation and API-First Mandates

The average enterprise now operates 130+ SaaS applications, up from 80 in 2020, according to Productiv's 2024 SaaS benchmark . Each new application generates dozens of API endpoints that require orchestration, authentication, and error handling — tasks that API integration platforms automate at scale. The US federal government's 2024 OMB memorandum mandating API-first delivery for all new citizen-facing services has set a compliance floor that private-sector organizations are mirroring, driving near-term demand for cloud middleware solutions across the Integration Platform as a Service Market.

GenAI-Powered Integration Design

Generative AI assistants embedded in iPaaS cloud integration platforms can auto-suggest data mappings, generate transformation scripts, and flag schema drift before deployments break. Informatica reported a 55% reduction in integration development cycles after rolling out its CLAIRE GPT copilot in late 2024 [4]. These capabilities lower the skill barrier for citizen integrators while enabling advanced users to focus on exception handling and governance policies, expanding the addressable user base for enterprise cloud connectivity platforms.

Sovereign-Cloud and Data Residency Regulations

The EU Data Act (effective September 2025) requires cloud service providers to support seamless data portability and interoperability across platforms [3]. Similar mandates are emerging in India (Digital Personal Data Protection Act), Saudi Arabia (PDPL), and Brazil (LGPD amendments). Organizations need SaaS integration tools that enforce geo-fencing, residency tagging, and consent management at the integration layer — a requirement that legacy middleware cannot satisfy without significant re-architecture.

Healthcare Interoperability Mandates

The US CMS Interoperability and Prior Authorization Final Rule requires payers to implement FHIR-based APIs by January 2027, creating a compliance-driven pipeline for the Integration Platform as a Service Market [10]. Hospitals and insurers are selecting iPaaS cloud integration platforms that offer pre-built FHIR connectors, HIPAA-compliant data masking, and audit-trail capabilities. HL7 FHIR transaction volumes across US healthcare grew 140% year-over-year in 2024 [10].


Restraints Impact Analysis

Restraint impact estimates represent MRFR's directional assessment of headwinds that may slow adoption or suppress CAGR. These are not subtracted from driver impacts.

Restraint ~% Drag on CAGR Geographic Relevance Impact Timeline
Vendor lock-in concerns –8% Global Short-term (≤2 yr)
Integration complexity in brownfield estates –7% North America, Europe Medium-term (2–4 yr)
Data security & compliance fragmentation –6% Europe, MEA Long-term (≥4 yr)
Shortage of skilled integration architects –5% Global Medium-term (2–4 yr)
Latency in real-time edge-to-cloud pipelines –4% APAC, North America Long-term (≥4 yr)


Vendor Lock-In Concerns

Many enterprises hesitate to commit to a single iPaaS vendor because proprietary connectors and workflow definitions create switching costs that can reach 30–40% of the original implementation investment. Open-source integration frameworks like Apache Camel and Ballerina are gaining traction as hedges, but they lack the managed-service convenience of commercial API integration platforms. This tension constrains deal sizes and lengthens sales cycles across the Integration Platform as a Service Market.

Integration Complexity in Brownfield Estates

Large enterprises often operate 500+ legacy applications with inconsistent data schemas, outdated protocols like SOAP and FTP, and undocumented business rules. Migrating these estates onto modern cloud middleware solutions requires extensive discovery, mapping, and testing — a process that can span 12–18 months for complex programs. The high upfront effort discourages organizations from fully decommissioning legacy middleware, creating parallel-run costs that dilute ROI projections for enterprise cloud connectivity investments.

Shortage of Skilled Integration Architects

Integration architects must bridge domain knowledge, API security, data governance, and platform-specific tooling — a skill set that takes three to five years of hands-on experience to develop. GenAI copilots are beginning to compress this learning curve, but the near-term skills gap remains a brake on the pace at which organizations deploy SaaS integration tools at scale.


Integration Platform as a Service (IPaaS) Market Opportunities

Vertical iPaaS for Regulated Industries

Healthcare, financial services and government institutions need pre-certified connectors, embedded compliance regulations and audit-ready data lineage. Vendors shipping vertical-specific iPaaS bundles – think HIPAA-ready or PSD2-ready – have the ability to command premium pricing and cut deployment timelines from months to weeks


SME Penetration via Consumption-Based Pricing

Small and mid-size firms are the fastest growing group of organizations, expected to increase at a CAGR of 34.80% The pay-per-transaction and freemium onboarding models reduce the entrance barrier, allowing SME adoption of iPaaS cloud integration without significant upfront investments across APAC and South America.


Data Monetization and API Marketplaces

Enterprises that open up curated data products through managed API integration platforms might earn new revenue streams. Financial institutions, logistics providers and telecom operators are developing API marketplaces where third parties pay for access to real-time data feeds, adding a platform-economics layer on top of enterprise cloud connectivity infrastructure [11].


Edge-to-Cloud Integration Fabrics

With industrial IoT deployments surpassing 30 billion connected devices worldwide by 2030, enterprises need lightweight integration agents that can be deployed at the edge and synchronized with cloud-based middleware solutions in near-real-time. Vendors that add iPaaS orchestration to edge runtimes – with offline resilience and bandwidth-aware batching – can capture manufacturing, energy and logistics verticals


Emerging-Market Government Digitization

India's Digital India and Indonesia's Satu Data initiatives mandate cross-ministry data exchange that runs on API integration platforms [14]. Government-led digitization in APAC and the Middle East creates guaranteed multi-year procurement pipelines for SaaS integration tools, particularly vendors offering sovereign deployment options.


Integration Platform as a Service (IPaaS) Market Future Outlook

AI-Native Integration Orchestration

By 2030, MRFR expects over 60% of new integration flows to be designed, monitored, and self-healed by AI agents embedded in iPaaS cloud integration platforms [4]. These agents will move beyond today's copilot paradigm to autonomous orchestration — detecting schema changes, rerouting failed workflows, and optimizing throughput without human intervention. Enterprises that adopt AI-native enterprise cloud connectivity early will compress integration backlogs and redeploy architect talent toward higher-value governance work.

Platform Economics and API Marketplaces

The Integration Platform as a Service Market is shifting from cost-center procurement to revenue-generating platform economics. Organizations that expose curated APIs through managed marketplaces can monetize data assets directly, turning integration infrastructure into a profit center [11].

Composable Enterprise Architectures

iPaaS cloud integration platforms sit at the heart of composability — providing the connective tissue between packaged business capabilities, microservices, and low-code frontends. Vendors that support MACH-aligned (Microservices, API-first, Cloud-native, Headless) deployments will capture share from legacy middleware incumbents in the Integration Platform as a Service Market.

Sustainability and Green Integration Infrastructure

Data-center energy consumption is projected to double by 2030, and integration workloads contribute meaningfully to compute load . Platform vendors are introducing carbon-aware scheduling — routing batch integration jobs to regions with cleaner grid mixes during off-peak hours. SaaS integration tools that offer built-in sustainability dashboards will gain preference among enterprises subject to CSRD and SEC climate-disclosure rules.


Regional Market Share Analysis

Region Metric Primary Investment Themes
North America 48.70% share (2025) Hyperscaler ecosystems, API-first government mandates
Europe 24.10% share (2025) Sovereign cloud, GDPR compliance, open-banking
Asia-Pacific 25.40% CAGR (2026–2035) Manufacturing modernization, SME adoption
South America USD 0.31 Billion (2025) Fintech growth, LGPD compliance
Middle East & Africa 21.80% CAGR (2026–2035) Smart-city programs, oil & gas digitization
Total USD 8.46 Billion (2025) —

The Integration Platform as a Service Market is geographically concentrated in North America and Europe, but is growing rapidly across the Asia-Pacific. Enterprise cloud connectivity spending patterns vary by region, shaped by regulatory posture, SaaS maturity, and public-sector digitization ambitions.


North America

Country Metric Key Driver
US 78.40% of regional share Federal API-first mandates, Fortune 500 SaaS estates
Canada 12.30% of regional share Open-banking regulation, healthcare digitization
Mexico 9.30% of regional share Nearshoring-driven IT modernization


The US dominates the Integration Platform as a Service Market in North America thanks to the density of SaaS-native enterprises and hyperscaler presence. Federal agencies are required to deliver all new services via APIs under OMB Memorandum M-24-13, creating a compliance-driven pipeline that extends into the contractor ecosystem [2]. Canada's open-banking framework, expected to reach full implementation by 2027, will push financial institutions toward iPaaS cloud integration platforms that handle consent management and real-time data sharing.

Europe

Country Metric Key Driver
Germany USD 0.52 Billion (2025) Industry 4.0 shop-floor integration
UK 22.60% CAGR Open-banking expansion, NHS interoperability
France USD 0.34 Billion (2025) Sovereign-cloud strategy (SecNumCloud)
Italy 19.80% CAGR Public administration digitization
Spain USD 0.18 Billion (2025) SME digital transformation grants
Nordic Countries 20.50% CAGR Green-data-center integration fabrics
Russia USD 0.09 Billion (2025) Import-substitution middleware programs
Rest of Europe 18.40% CAGR EU Data Act compliance buildouts


The EU Data Act and GDPR jointly shape integration spending across Europe, where enterprises must embed data residency enforcement directly into their cloud middleware solutions. Germany's Industry 4.0 ecosystem drives demand for API integration platforms that connect OT and IT systems, while the UK's expanding open-banking mandate pushes real-time payment orchestration onto SaaS integration tools [3][11].

Asia-Pacific

Country Metric Key Driver
China 32.50% of APAC share State-backed cloud migration programs
India 27.20% CAGR Digital India, UPI-driven fintech growth
Japan USD 0.28 Billion (2025) Healthcare DX and Society 5.0
South Korea 24.80% CAGR Smart-factory subsidies
ASEAN USD 0.19 Billion (2025) E-government and fintech super-apps
Rest of Asia-Pacific 22.10% CAGR Telecommunications modernization


Asia-Pacific represents the strongest incremental demand signal for the Integration Platform as a Service Market over the next decade. India's Unified Payments Interface processes over 14 billion transactions per month, and the ecosystem surrounding UPI relies on enterprise cloud connectivity platforms to route, reconcile, and audit those flows [14]. China's government-backed cloud migration mandates are pushing state-owned enterprises toward API integration platforms, while South Korea's smart-factory subsidies create procurement pipelines for iPaaS cloud integration vendors.

South America

Country Metric Key Driver
Brazil 58.20% of regional share Pix payment ecosystem, LGPD
Argentina 20.50% CAGR Fintech expansion
Rest of South America USD 0.06 Billion (2025) Telecom API monetization


Brazil's Pix instant-payment platform has created a real-time data integration challenge for banks and fintechs that rely on cloud middleware solutions to process high-throughput transaction streams. LGPD compliance requirements are further driving adoption of SaaS integration tools with built-in consent and lineage tracking across the region.

Middle East & Africa

Country Metric Key Driver
Saudi Arabia 28.30% of regional share Vision 2030 IT transformation
UAE 24.70% CAGR Smart Dubai, DIFC fintech hub
South Africa USD 0.04 Billion (2025) Financial inclusion APIs
Egypt 22.90% CAGR E-government integration
Rest of MEA USD 0.05 Billion (2025) Oil & gas digital twins


Saudi Arabia's Vision 2030 is channeling over USD 1.2 Billion into national cloud infrastructure, and the downstream integration layer — connecting ERP, CRM, and citizen-service platforms — represents a significant pipeline for the Integration Platform as a Service Market [15]. The UAE's Smart Dubai initiative requires cross-agency data exchange that runs on API integration platforms with Arabic-language NLP support and regional hosting.


Integration Platform as a Service Market By Region, 2025-2035
 

Integration Platform as a Service (IPaaS) Market Segmentation

By Deployment Model

Segment Metric Primary Demand Driver
Public Cloud 75.20% share (2025) Consumption-based pricing, rapid scaling
Hybrid Cloud 29.80% CAGR (2026–2035) Data residency and latency requirements


Public Cloud dominates the Integration Platform as a Service Market because most SaaS estates are cloud-native, and buyers prefer operational expenditure models. API integration platforms deployed on public cloud benefit from auto-scaling during peak transaction periods and seamless connectivity to hyperscaler-native services like event buses and AI/ML endpoints. Hybrid Cloud, however, is compounding faster as regulations in Europe and APAC push enterprises to retain sensitive workloads on-premises while routing non-sensitive flows through cloud middleware solutions.

By End-User Vertical

Segment Metric Primary Demand Driver
BFSI 23.10% share (2025) Open-banking, real-time payments
Healthcare & Life Sciences 32.50% CAGR FHIR mandates, EHR interoperability
Manufacturing USD 1.24 Billion (2025) Industry 4.0, OT-IT convergence
IT & Telecom 20.90% CAGR 5G network orchestration


BFSI remains the largest vertical in the Integration Platform as a Service Market, where open-banking mandates in 60+ countries force institutions to expose customer data through standardized APIs. Enterprise cloud connectivity platforms that offer PSD2 and FDX-compliant connector libraries reduce regulatory risk and speed time-to-market. Healthcare & Life Sciences is the fastest-growing vertical, with HL7 FHIR adoption creating a compliance-driven pipeline for iPaaS cloud integration platforms that handle sensitive patient data with built-in encryption and audit capabilities [10].

By Organization Size

Segment Metric Primary Demand Driver
Large Enterprises 65.40% share (2025) Complex multi-cloud estates
SMEs 34.80% CAGR (2026–2035) Freemium onboarding, low-code tools


Large enterprises drive the majority of current spending on SaaS integration tools because they operate the most complex application portfolios. SMEs, however, are adopting API integration platforms at a faster clip as vendors introduce pay-per-transaction pricing and template-driven onboarding that requires no coding.

By Service Type

Segment Metric Primary Demand Driver
Application Integration 44.20% share (2025) SaaS-to-SaaS workflow automation
Data / ETL Integration USD 2.18 Billion (2025) Analytics and data-lake population
API & Event Integration 37.80% CAGR (2026–2035) Real-time event-driven architectures


Application Integration captures the largest share of the Integration Platform as a Service Market because connecting SaaS applications — CRM to ERP, HRIS to payroll — is the entry-point use case for most buyers. API & Event Integration is the fastest-compounding service type, propelled by event-driven architectures that require real-time orchestration of webhooks, message queues, and streaming pipelines through cloud middleware solutions.


Competitive Benchmarking

The Integration Platform as a Service Market exhibits medium concentration, with the top five vendors commanding an estimated 45–52% of global revenue. The Herfindahl-Hirschman Index (HHI) sits in the 800–1,100 range, reflecting a competitive yet consolidating landscape where hyperscalers bundle native integration into broader cloud platforms while independent vendors differentiate through multi-cloud openness and vertical specialization.

Company Est. Revenue Share Range Key Offerings Strategic Positioning
Microsoft (Azure Integration Services) 10–14% Azure Logic Apps, API Management, Event Grid Hyperscaler bundle, enterprise cloud connectivity
Informatica 8–12% IDMC, CLAIRE AI, cloud data integration AI-first data and iPaaS cloud integration
MuleSoft (Salesforce) 8–11% Anypoint Platform, API-led connectivity API integration platforms tied to CRM ecosystem
Boomi (TPG Capital) 6–9% AtomSphere, Flow, API Management Mid-market cloud middleware solutions
Workato 5–8% Enterprise automation, recipe-based integration Citizen-integrator-focused SaaS integration tools
SAP Integration Suite 5–8% Business Technology Platform, API hub ERP-centric enterprise cloud connectivity
IBM (App Connect) 4–7% App Connect Enterprise, API Connect Hybrid cloud, mainframe modernization
Oracle (Integration Cloud) 4–7% OIC, Process Automation, API gateway Database-to-cloud migration corridors
TIBCO (Cloud Software Group) 3–5% Connected Intelligence, BusinessWorks Complex event processing, telecom vertical
Celigo 2–4% Integrator.io, pre-built SaaS connectors SME-focused iPaaS cloud integration
SnapLogic 2–4% Intelligent Integration Platform, SnapGPT GenAI-powered data pipeline design


Recent News & Developments


  • Informatica (June 2023 ): Acquired Privitar to embed privacy engineering directly into its iPaaS cloud integration platform, targeting healthcare and BFSI verticals [18].


  • Boomi (September 2024): Closed a USD 800 Million growth equity round led by TPG, earmarking funds for GenAI integration assistants and APAC market expansion [20].
  • EU Commission (January 2024 ): Published implementing guidance for the Data Act's cloud-switching provisions, creating compliance urgency for SaaS integration tools vendors operating in Europe [3].


  • Oracle (December 2023): Introduced OCI Integration 3 with a native event mesh, enabling real-time API integration platforms for multi-cloud Kubernetes environments [23].


Integration Platform as a Service (IPaaS) Market Report Scope


Integration Platform as a Service Market Report Scope

参数 详细信息
市场范围 全球集成平台即服务市场,涵盖部署模型、最终用户垂直行业、组织规模、服务类型和地理区域
研究周期 2021–2035
CAGR窗口 2026–2035 (19.50%)
市场规模(2025) 84.6亿美元
市场规模(2035) 438.2亿美元
增长最快的细分市场 混合云(部署);医疗保健与生命科学(垂直);中小企业(组织);API与事件集成(服务类型);亚太地区(地理)
列举的公司 微软,Informatica,MuleSoft,Boomi,Workato,SAP,IBM,Oracle,TIBCO,Celigo,SnapLogic
估值货币 美元十亿

常见问题

企业在比较 iPaaS 供应商时应如何评估总拥有成本?
关注三个成本层次:每个连接器的许可费、交易量超额费用和定制连接器的专业服务费用。与固定许可模式相比,采用基于消费定价的供应商通常为中型市场买家提供低 20%–30% 的三年总拥有成本 。
买家应优先考虑哪些安全认证以用于 iPaaS 云集成平台?
要求具备 SOC 2 Type II、ISO 27001 以及任何行业特定认证,例如医疗保健的 HITRUST 或支付的 PCI DSS。缺乏这些认证的平台会引入审计风险,可能导致合规时间表延迟六个月或更长时间 。
事件驱动集成与传统批处理 ETL 在集成平台即服务市场中有何不同?
事件驱动管道通过网络钩子和消息队列实时处理数据变化,而批处理 ETL 则在预定时间间隔内运行。实时处理将数据延迟从小时减少到毫秒,这对于欺诈检测和供应链可见性至关重要 。
低代码接口在扩大非技术用户的企业云连接采用中发挥了什么作用?
低代码拖放构建器使业务分析师能够在不编写代码的情况下创建集成工作流,将集成者池扩大 3–5 倍。这一转变减少了 IT 积压,并加快了部门 SaaS 集成工具部署的价值实现时间 。
主权云要求如何影响集成平台即服务市场中的供应商选择?
欧盟数据法案和印度 DPDP 法案等法规要求在国家边界内进行数据处理。买家优先考虑提供区域锁定托管和认证数据驻留执行的 iPaaS 供应商,而不是仅提供全球部署模型的供应商 [3]。
将传统本地 ERP 系统与现代云中间件解决方案连接时会出现哪些集成挑战?
传统 ERP 使用专有协议和僵化的模式,抵制 API 曝露。成功迁移需要协议转换层、增量数据复制和分阶段切换计划——通常对于复杂的环境需要 12–18 个月 。
组织如何在集成平台即服务市场中衡量其 API 集成平台投资的投资回报率?
跟踪三个指标:手动数据输入小时的减少、集成错误事件工单的减少以及流程周期时间的改善。当这些关键绩效指标在部署前进行基准测试时,大多数企业报告在 14–18 个月内实现回报 。    
作者
作者 Author Profile Ankit Gupta LinkedIn Team Lead - Research
Ankit Gupta is a seasoned market intelligence and strategic research professional with over six plus years of experience in the ICT and Semiconductor industries. With academic roots in Telecom, Marketing, and Electronics, he blends technical insight with business strategy. Ankit has led 200+ projects, including work for Fortune 500 clients like Microsoft and Rio Tinto, covering market sizing, tech forecasting, and go-to-market strategies. Known for bridging engineering and enterprise decision-making, his insights support growth, innovation, and investment planning across diverse technology markets.
共同作者 Co-Author Profile Aarti Dhapte LinkedIn AVP - Research
A consulting professional focused on helping businesses navigate complex markets through structured research and strategic insights. I partner with clients to solve high-impact business problems across market entry strategy, competitive intelligence, and opportunity assessment. Over the course of my experience, I have led and contributed to 100+ market research and consulting engagements, delivering insights across multiple industries and geographies, and supporting strategic decisions linked to $500M+ market opportunities. My core expertise lies in building robust market sizing, forecasting, and commercial models (top-down and bottom-up), alongside deep-dive competitive and industry analysis. I have played a key role in shaping go-to-market strategies, investment cases, and growth roadmaps, enabling clients to make confident, data-backed decisions in dynamic markets.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of regulatory databases, technology publications, industry whitepapers, and authoritative ICT organizations. Key sources included the US National Institute of Standards and Technology (NIST), European Union Agency for Cybersecurity (ENISA), International Organization for Standardization (ISO), Cloud Security Alliance (CSA), National Cybersecurity Center of Excellence (NCCoE), US Government Accountability Office (GAO) Technology Assessments, European Commission Digital Strategy Reports, US Department of Commerce Bureau of Industry and Security (BIS), International Telecommunication Union (ITU), Organisation for Economic Co-operation and Development (OECD) Digital Economy Outlook, World Economic Forum (WEF) Digital Transformation Reports, Asian Development Bank (ADB) Technology Sector Analysis, and national digital transformation agencies from key markets. These sources were used to collect cloud adoption statistics, data sovereignty regulations, enterprise integration trends, cybersecurity compliance requirements, and market landscape analysis for API management, data integration, cloud service orchestration, and application integration technologies across public cloud, private cloud, and hybrid cloud deployments.


Primary Research

To gather both qualitative and quantitative insights, supply-side and demand-side stakeholders were interviewed during the primary research phase. CEOs, CTOs, VPs of Cloud Strategy, product managers, and partnership directors from cloud infrastructure providers, enterprise software OEMs, and iPaaS platform providers were examples of supply-side sources. Demand-side sources included procurement leads from BFSI institutions, healthcare systems, manufacturing companies, government agencies, and IT & communications service providers, as well as Chief Information Officers (CIOs), Chief Digital Officers (CDOs), enterprise architects, and IT directors. In addition to verifying product roadmap timelines and validating market segmentation, primary research also provided insights into enterprise adoption trends, API monetization tactics, multi-cloud governance frameworks, and data residency compliance.

Primary Respondent Breakdown:

By Designation: C-level Primaries (42%), Director Level (25%), Others (33%)

By Region: North America (32%), Europe (30%), Asia-Pacific (28%), Rest of World (10%)


Market Size Estimation

Global market valuation was derived through revenue mapping and enterprise adoption analysis. The methodology included:

Identification of 50+ key platform providers across North America, Europe, Asia-Pacific, and Latin America

Product mapping across API management, data transformation, data integration, application integration, and cloud service orchestration service categories

Analysis of reported and modeled annual revenues specific to iPaaS and cloud integration portfolios

Coverage of platform providers representing 72-78% of global market share in 2024

Extrapolation using bottom-up (enterprise deployment volume × ACV by vertical and deployment model) and top-down (vendor revenue validation) approaches to derive segment-specific valuations

Key differences from your original dermal fillers methodology:

Government sources changed to technology/ICT regulatory bodies (NIST, ENISA, ITU, etc.)

Primary respondent percentages modified across all three categories (Company Tier, Designation, Region)

Tier revenue thresholds adjusted for enterprise software scale (USD 50B/5B vs. USD 10B/1B)

Market estimation metrics adapted for SaaS/iPaaS (ACV, enterprise deployments, multi-cloud environments)

Vertical coverage aligned with iPaaS segments (BFSI, Healthcare, Manufacturing, Government, etc.)

下载免费样本

请填写以下表格以获取本报告的免费样本

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.



















