Hydrogen Fuel Cell Vehicle Market (2026 - 2035)

Hydrogen Fuel Cell Vehicle (HFCV) Market Research Report By Vehicle Type (Passenger Cars, Light Commercial Vehicles, Buses, Trucks (Medium & Heavy-Duty), Others (Material Handling)), By Technology (Proton Exchange Membrane Fuel Cell, Phosphoric Acid Fuel Cell, Solid Oxide Fuel Cell, Alkaline Fuel Cell, Others), By Driving Range (Less Than or Equal To 250 Miles, 251–500 Miles, Above 500 Miles), By Power Output (Less Than 100 kW, 100–200 kW, Above 200 kW), By End-Use Ownership (Private / Personal, Commercial Fleet, Public Transport / Government) and By Regional (North America, Europe, South America, Asia Pacific, Middle East and Africa) - Growth & Industry Forecast to 2035
ID: MRFR/AT/3300-HCR
200 Pages
Triveni Bhoyar, Sejal Akre
Last Updated: August 28, 2026
Hydrogen Fuel Cell Vehicle (HFCV) Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)39.8%
2025 Market SizeUSD 3.22 Billion
2035 Market SizeUSD 89.76 Billion
Key Players
Toyota Motor Corporation
SAIC Motor Corporation
Weichai Power
Ballard Power Systems
Honda Motor Co.
Daimler Truck AG
Opportunities
  • Depot-Captive Fleet Conversion
  • Hydrogen-as-a-Service Contracting
  • Emerging-Market Corridor Development

Hydrogen Fuel Cell Vehicle Market 摘要

根据市场研究未来的分析,氢燃料电池汽车市场规模预计在2024年为48.9亿美元。氢燃料电池汽车行业预计将从2025年的58.48亿美元增长到2035年的349.9亿美元,预测期内(2025 - 2035年)的年均增长率(CAGR)为19.59%。

主要市场趋势和亮点

氢燃料电池汽车市场因技术进步和支持政策而有望实现显著增长。

  • 北美仍然是氢燃料电池汽车最大的市场,展现出强劲的需求和投资。
  • 亚太地区正在成为增长最快的地区,受到政府倡议和消费者兴趣的推动。
  • 乘用车主导市场,而商用车在采用方面经历了最快的增长。
  • 环境关注和政府激励是关键驱动因素,促进基础设施发展和消费者接受。

市场规模与预测

2024年市场规模 48.9(十亿美元)
2035年市场规模 349.9(十亿美元)
年均增长率(2025 - 2035) 19.59%

主要参与者

氢燃料电池汽车行业的主要领先企业包括:丰田(JP),现代(KR),本田(JP),梅赛德斯-奔驰(DE),宝马(DE),日产(JP),通用汽车(US),巴拉德动力系统(CA),Plug Power(US)等。

Hydrogen Fuel Cell Vehicle Market Drivers

Environmental Concerns and Sustainability

The Hydrogen Fuel Cell Vehicle Market is increasingly driven by growing environmental concerns and the need for sustainable transportation solutions. As awareness of climate change and air pollution rises, consumers and governments alike are seeking alternatives to traditional fossil fuel vehicles. Hydrogen fuel cells produce zero emissions at the point of use, making them an attractive option for eco-conscious consumers. In 2025, the demand for hydrogen fuel cell vehicles is projected to increase significantly, with estimates suggesting a market growth rate of over 20% annually. This shift towards cleaner technologies is likely to bolster the hydrogen fuel cell vehicle market, as manufacturers respond to consumer preferences for sustainable options.

Government Incentives and Regulatory Frameworks

Government incentives and supportive regulatory frameworks play a crucial role in shaping the Hydrogen Fuel Cell Vehicle Market. Many countries are implementing policies that promote the adoption of hydrogen fuel cell vehicles through subsidies, tax breaks, and grants for research and development. For example, several nations have set ambitious targets for reducing greenhouse gas emissions, which often include the promotion of hydrogen as a clean fuel alternative. In 2025, it is anticipated that these initiatives will lead to a substantial increase in the number of hydrogen fuel cell vehicles on the road, further stimulating market growth and attracting investment in related infrastructure.

Technological Innovations in Fuel Cell Technology

Technological advancements in fuel cell technology are a pivotal driver for the Hydrogen Fuel Cell Vehicle Market. Innovations such as improved fuel cell efficiency, reduced costs, and enhanced durability are making hydrogen vehicles more competitive with battery electric vehicles. For instance, recent developments have led to fuel cells that can operate effectively at lower temperatures, which could expand their usability in various climates. Furthermore, the integration of advanced materials and manufacturing techniques is expected to lower production costs, potentially increasing market penetration. As these technologies continue to evolve, they may significantly influence consumer adoption rates and overall market dynamics.

Rising Consumer Demand for Alternative Fuel Vehicles

Infrastructure Development for Hydrogen Refueling Stations
市场细分洞察

The Hydrogen Fuel Cell Vehicle Market is evolving with diverse offerings among various vehicle types. Among these, passenger vehicles hold a significant share, leading in consumer preference and adoption. Commercial vehicles are emerging quickly, driven by the increasing demand for sustainable logistics and freight transport solutions. The market is thereby characterized by a competitive landscape, where innovative technologies and policy incentives further enhance share distribution among these segments. Growth trends in the Hydrogen Fuel Cell Vehicle Market are significantly influenced by supportive government regulations and clarity on emissions reductions goals. Passenger vehicles, while currently the largest segment, are being challenged by the rapid rise of commercial vehicles, which are witnessing advances in fuel cell efficiency and cost reduction strategies. This dynamic creates an environment ripe for both segments to thrive, catering to various market demands and consumer preferences.

In the Hydrogen Fuel Cell Vehicle Market, the sales channel landscape is dominated by Direct Sales, which holds the largest share due to the surge in interest from consumers seeking personalized vehicle solutions. Dealerships follow as a vital channel, especially as manufacturers leverage established networks to enhance accessibility and customer engagement. Online Sales, while growing, have not yet captured significant market share compared to these two primary channels, which are essential for driving consumer trust and personalized service. Looking ahead, the growth trends in the sales channel segment are driven by increasing consumer awareness about hydrogen fuel cell technology and its benefits. Dealerships are becoming the fastest-growing segment as they adapt to consumer preferences and offer enhanced services. Additionally, Direct Sales are witnessing steady demand due to the procurement of hydrogen vehicles through specialized platforms, while Online Sales will likely gain traction as more consumers become accustomed to digital shopping experiences for high-value items like vehicles. DOE's Loan Programs Office is providing $3 billion in federal loan guarantees for hydrogen-related projects — complementing the $9.5 billion BIL direct funding. This public financing layer de-risks private investment in hydrogen fuel cell infrastructure and production, directly accelerating the commercialisation pathway for FCEV deployment.

获取关于Hydrogen Fuel Cell Vehicle Market的更多详细见解

区域洞察

North America : Innovation and Investment Hub

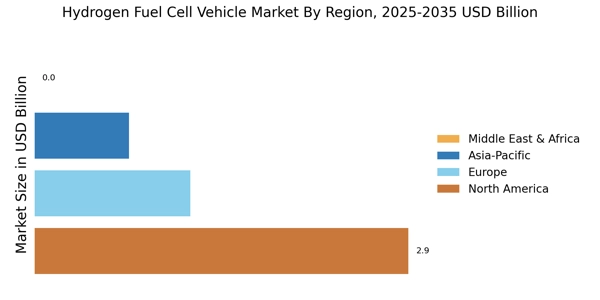
North America is poised to dominate the hydrogen fuel cell vehicle market, driven by significant investments in infrastructure and technology. The U.S. holds approximately 60% of the market share, with Canada following at around 20%. Regulatory support, such as the Infrastructure Investment and Jobs Act, aims to enhance hydrogen production and distribution, fostering a favorable environment for growth. The competitive landscape features major players like General Motors and Plug Power, alongside established automotive giants such as Toyota and Hyundai. The U.S. government is actively promoting hydrogen initiatives, which has led to increased collaboration between public and private sectors. This synergy is expected to accelerate the deployment of hydrogen fuel cell vehicles across the region.

Europe : Sustainability and Innovation Leader

Europe is rapidly emerging as a leader in the hydrogen fuel cell vehicle market, with a market share of approximately 25%. Germany and France are the largest markets, accounting for nearly 15% and 5% respectively. The European Union's Green Deal and hydrogen strategy aim to promote clean energy solutions, significantly boosting demand for hydrogen vehicles and infrastructure. Key players in this region include Mercedes-Benz and BMW, who are investing heavily in hydrogen technology. The competitive landscape is characterized by strong collaboration between automotive manufacturers and energy providers, enhancing the development of hydrogen refueling stations. This integrated approach is crucial for achieving the EU's ambitious climate goals and fostering a sustainable transport ecosystem.

Asia-Pacific : Emerging Market Potential

Asia-Pacific is witnessing rapid growth in the hydrogen fuel cell vehicle market, with Japan and South Korea leading the charge. Japan holds about 15% of the market share, while South Korea follows closely with around 10%. Government initiatives, such as Japan's Hydrogen Roadmap, are pivotal in driving demand and investment in hydrogen technologies, creating a robust market environment. The competitive landscape is dominated by key players like Toyota and Hyundai, who are at the forefront of hydrogen vehicle development. The region's focus on innovation and technology is fostering partnerships between automotive manufacturers and energy companies, enhancing the deployment of hydrogen infrastructure. This collaborative effort is essential for meeting the increasing demand for sustainable transportation solutions in Asia-Pacific.

Middle East and Africa : Resource-Rich Frontier

The Middle East and Africa region is beginning to explore the hydrogen fuel cell vehicle market, with a market share of approximately 5%. Countries like South Africa and the UAE are taking initial steps towards hydrogen adoption, driven by the need for sustainable energy solutions and diversification of their economies. Government initiatives are starting to emerge, focusing on renewable energy and hydrogen production. The competitive landscape is still developing, with local players and international companies looking to establish a foothold in the market. The presence of abundant natural resources, particularly in the Gulf region, presents significant opportunities for hydrogen production. As infrastructure develops, the region is expected to see increased interest and investment in hydrogen fuel cell technologies.

Hydrogen Fuel Cell Vehicle Market Regional Image

主要参与者和竞争洞察

氢燃料电池汽车市场经历了显著的增长和转型,推动因素包括技术进步、环境意识的提高以及各国政府减少碳排放的强烈推动。作为传统化石燃料动力汽车的更清洁替代品,氢燃料电池汽车(HFCEVs)在消费者和制造商中都越来越受到青睐。对该市场的竞争洞察揭示了一个以创新、战略合作伙伴关系和持续的研发活动为特征的格局,旨在提高燃料电池效率、降低生产成本并扩展燃料基础设施。参与该行业的公司正在实施强有力的战略,以增强其市场存在,利用其独特的能力和优势在市场中占据重要份额。

宝马在氢燃料电池汽车市场取得了显著进展,定位自己为一个关键参与者,致力于可持续发展和推动创新。该公司利用其广泛的汽车工程专业知识开发先进的氢燃料电池技术,并将其与其知名的电动车产品相结合。宝马的全球存在增强了其竞争地位,因为该品牌在各个市场中广受认可和信任。公司的优势在于其强大的研发能力、对尖端技术的重大投资以及与氢气供应链各方的强大合作。这种方法不仅帮助宝马提升其车辆产品,还确保其在向可再生能源解决方案转型的前沿。


尼古拉是氢燃料电池汽车市场的另一个重要参与者,专注于开创氢动力商用车。该公司已定位自己以满足对零排放交通解决方案日益增长的需求,主要通过其重型卡车及相关服务。通过强调创新产品开发,尼古拉旨在颠覆传统的运输和物流行业。公司的优势在于其致力于开发可靠的氢气加油基础设施,从而增强其产品的实用性和吸引力。此外,尼古拉积极参与形成战略合作伙伴关系和进行并购,以增强其市场存在并加速增长。这种方法使尼古拉能够利用协同效应,获得新技术和市场,最终增强其在全球氢燃料电池汽车竞争格局中的地位。

Hydrogen Fuel Cell Vehicle Market市场的主要公司包括

行业发展

  • 2025年第三季度:德国超过100个氢气站,法国70亿美元氢气计划德国超过100个氢气加油站投入运营,而法国宣布了一项70亿美元的国家氢气基础设施计划,以加速氢燃料电池汽车的采用并支持重型运输的脱碳。
  • 2025年第一季度:丰田在2025年氢气和燃料电池研讨会上提供技术路线图丰田高管公布了一项全面的氢燃料电池汽车技术路线图,重申了公司扩大其氢动力产品线的承诺,并概述了通过燃料电池创新实现碳中和的新战略。
  • 2024年第二季度:现代在韩国开设新的氢燃料电池汽车市场生产设施现代正式开设了一座专门用于氢燃料电池汽车的先进制造设施,旨在扩大生产能力,以满足全球对零排放交通的日益增长的需求。
  • 2024年第二季度:本田和五十铃宣布合作开发氢动力重型卡车本田和五十铃签署了一项战略合作协议,共同开发和商业化氢燃料电池系统,目标是在2025年前在日本和国际市场部署。
  • 2025年第一季度:尼古拉获得2亿美元融资以扩大氢气卡车生产尼古拉公司完成了一轮由机构投资者主导的2亿美元融资,以加速其氢燃料电池电动卡车在北美市场的生产和交付。
  • 2025年第二季度:戴姆勒卡车和沃尔沃集团启动氢燃料电池系统合资企业戴姆勒卡车和沃尔沃集团正式启动了他们的合资企业Cellcentric,开发和大规模生产商用车辆的氢燃料电池系统,预计首批产品将在2025年底进入市场。
  • 2025年第一季度:丰田推出下一代Mirai氢燃料电池汽车市场丰田推出了下一代Mirai,具有更长的续航、更快的加油和先进的安全功能,巩固了其在氢燃料电池乘用车领域的领导地位。
  • 2024年第二季度:Plug Power赢得合同为欧洲送货车提供氢燃料电池系统Plug Power获得了一项重大合同,为一家领先的欧洲物流公司运营的送货车队提供氢燃料电池系统,标志着其在商用车领域的重大扩展。
  • 2024年第三季度:中国批准国家氢燃料电池汽车补贴计划中国政府批准了一项新的国家补贴计划,以激励氢燃料电池汽车的购买和部署,旨在加速采用和国内生产。
  • 2025年第二季度:宝马宣布在欧洲市场推出氢动力SUV宝马宣布其首款氢动力SUV的商业推出,目标是欧洲客户,并利用德国和法国扩展的氢气加油基础设施。
  • 2025年第一季度:巴拉德动力系统与西门子签署铁路氢燃料电池集成合作协议巴拉德动力系统与西门子移动公司达成合作,将氢燃料电池技术整合到客运铁路车辆中,计划在德国和奥地利推出试点项目。
  • 2024年第二季度:通用汽车任命新的氢燃料电池汽车市场部门负责人通用汽车宣布任命一位新的高管来领导其氢燃料电池汽车部门,标志着对氢动力出行解决方案的重新关注和投资。

未来展望

Hydrogen Fuel Cell Vehicle Market 未来展望

氢燃料电池汽车市场预计在2025年至2035年期间以19.59%的年均增长率增长,推动因素包括技术进步、监管支持和日益增加的环境关注。

到2035年,市场预计将实现显著增长,使氢燃料电池汽车成为一种可行的替代方案。

市场细分

氢燃料电池汽车市场应用前景

  • 公共交通
  • 货运运输
  • 个人使用
  • 企业车队

氢燃料电池汽车市场车辆类型前景

  • 乘用车
  • 商用车
  • 公交车
  • 两轮车

氢燃料电池汽车市场销售渠道前景

  • 直接销售
  • 经销商
  • 在线销售

氢燃料电池汽车市场燃料电池技术前景

  • 质子交换膜燃料电池
  • 固体氧化物燃料电池
  • 碱性燃料电池

报告范围

Parameter Detail
Market Scope Global Hydrogen Fuel Cell Vehicle Market by vehicle type, technology, driving range, power output, end-use ownership, and Region
Study Period 2021–2035 (Historical 2021–2024; Base Year 2025; Forecast 2026–2035)
CAGR 39.8% (2026–2035)
Market Size Checkpoints USD 3.22 Billion (2025); USD 4.40 Billion (2026); USD 23.50 Billion (2031); USD 89.76 Billion (2035)
Fastest Growing Segments Trucks (Medium & Heavy-Duty); Above 500 Miles; Commercial Fleet
Companies Profiled 11 major suppliers and integrators
Valuation Currency USD (values in billions)
CAGR Driver Disclaimer Driver and restraint impact percentages are directional analyst estimates and are not additive components of the reported CAGR

FAQs

2025年氢燃料电池汽车市场的当前估值是多少?

氢燃料电池汽车市场在2024年的估值约为48.9亿美元。

到2035年,氢燃料电池汽车市场的预计市场估值是多少?

预计到2035年,市场估值将达到349.9亿美元。

在2025年至2035年的预测期内,氢燃料电池汽车市场的预期年均增长率(CAGR)是多少?

预计市场在2025年至2035年期间的年均增长率为19.59%。

氢燃料电池汽车市场中哪些车辆类型处于领先地位?

乘用车和商用车是领先的细分市场,预计到2035年分别达到130亿美元和80亿美元的估值。

哪些应用推动了氢燃料电池汽车市场的增长?

公共交通和企业车队是关键应用,预计到2035年分别达到105亿美元和99.9亿美元。

市场上最突出的燃料电池技术是什么?

质子交换膜燃料电池在市场中占主导地位,预计到2035年估值为175亿美元。

氢燃料电池汽车市场中使用了哪些销售渠道?

直接销售和在线销售是重要渠道,预计到2035年分别达到139.9亿美元和105.1亿美元。

氢燃料电池汽车市场的主要参与者是谁?

主要参与者包括丰田、现代、本田、梅赛德斯-奔驰、宝马、日产、通用汽车、巴拉德动力系统和Plug Power。

到2035年,公交车市场与其他车辆类型相比如何?

公交车细分市场预计到2035年将达到50亿美元,表明有巨大的增长潜力。

氢燃料电池汽车市场的增长对汽车行业有什么重要意义?

市场的预期增长表明汽车行业向可持续能源解决方案的转型。

氢燃料电池汽车是如何工作的?
氢燃料电池电动车(FCEV)使用聚合物电解质膜(PEM)燃料电池,通过与氧气的电化学反应将储存在车载罐中的氢气转化为电能。唯一的副产品是水蒸气。电能驱动电动机,动能回收制动将能量回收至电池中。
美国能源部(DOE)对氢燃料电池汽车的成本目标是什么?
美国能源部的US DRIVE燃料电池技术团队将汽车燃料电池系统的目标定为每千瓦35美元(最终目标为每千瓦30美元,以与内燃机平价)。美国能源部的氢地球计划旨在在十年内将清洁氢的生产成本降低到每公斤1美元。
作者
Author
Author Profile
Triveni Bhoyar LinkedIn Senior Research Analyst
Triveni Bhoyar has over 5 years of experience in the market research industry, specializing in the Automotive and Aerospace & Defense sectors. She has contributed to 200+ reports, including numerous custom projects for leading global companies, delivering solutions to complex business challenges. Renowned for her ability to generate valuable insights, Triveni excels in addressing unique market dynamics with precision and depth. Her expertise spans market sizing, competitive intelligence, and trend analysis, enabling clients to craft data-driven growth strategies. With strong analytical rigor and a client-centric approach, she plays a pivotal role in driving impactful, strategic decision-making.
Co-Author
Co-Author Profile
Sejal Akre LinkedIn Senior Research Analyst
She has over 5 years of rich experience, in market research and consulting providing valuable market insights to client. Hands on expertise in management consulting, and extensive knowledge in domain including ICT, Automotive & Transportation and Aerospace & Defense. She is skilled in Go-to market strategy, industry analysis, market sizing, in depth company profiling, competitive intelligence & benchmarking and value chain amongst others.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of regulatory databases, peer-reviewed engineering journals, automotive publications, and authoritative energy & transportation organizations. Key sources included the US Department of Energy (DOE) Office of Energy Efficiency & Renewable Energy, US Environmental Protection Agency (EPA), National Highway Traffic Safety Administration (NHTSA), California Air Resources Board (CARB), California Fuel Cell Partnership (CaFCP), European Commission Clean Hydrogen Partnership, International Energy Agency (IEA) Global EV Outlook and Hydrogen Technology Reports, International Partnership for Hydrogen and Fuel Cells in the Economy (IPHE), International Renewable Energy Agency (IRENA), SAE International (formerly Society of Automotive Engineers), International Organization for Standardization (ISO TC 197 - Hydrogen Technologies), National Renewable Energy Laboratory (NREL), Argonne National Laboratory (ANL), Sandia National Laboratories, Hydrogen Council, Fuel Cell and Hydrogen Energy Association (FCHEA), Japan Hydrogen & Fuel Cell Promotion Council, China National Energy Administration (NEA), Korea Energy Economics Institute (KEEI), EU Eurostat Transport Database, and national energy ministry reports from key markets. These sources were used to collect vehicle deployment statistics, regulatory approval data, hydrogen station infrastructure metrics, safety certification studies, patent filings, and market landscape analysis for proton exchange membrane fuel cells (PEMFC), phosphoric acid fuel cells (PAFC), solid oxide fuel cells (SOFC), alkaline fuel cells (AFC), and vehicle categories spanning passenger cars, light commercial vehicles (LCVs), heavy commercial vehicles (HCVs), buses, and material handling equipment.


Primary Research

To gather both qualitative and quantitative insights, supply-side and demand-side stakeholders were interviewed during the primary research phase. CEOs, vice presidents of product development, chief technology officers, heads of regulatory affairs, and commercial directors from automakers, fuel cell stack producers, suppliers of hydrogen storage systems, and component suppliers were examples of supply-side sources. Fleet procurement managers, directors of public transit authorities, representatives of government energy agencies, logistics operators, fleet managers for material handling, and network developers for hydrogen stations were among the demand-side sources. In addition to verifying fuel cell technology roadmap timescales and validating market segmentation across vehicle types and power outputs, primary research also collected information on fleet adoption trends, total cost of ownership (TCO) dynamics, hydrogen pricing tactics, and infrastructure deployment schedules.

Primary Respondent Breakdown:

• By Designation: C-level Primaries (32%), Director Level (30%), Others (38%)

• By Region: North America (33%), Europe (30%), Asia-Pacific (28%), Rest of World (9%)


Market Size Estimation

Global market valuation was derived through revenue mapping and unit shipment analysis. The methodology included:

• Identification of 35+ key manufacturers across North America, Europe, Asia-Pacific, and Latin America, encompassing automotive OEMs (passenger vehicles, commercial trucks, buses), fuel cell system integrators, and specialized industrial vehicle producers

• Product mapping across passenger cars (sedans, SUVs, hatchbacks), light commercial vehicles, heavy-duty trucks, buses & coaches, and specialized vehicles (material handling, industrial), segmented by fuel cell technology (PEMFC, PAFC, SOFC, AFC), power output (<100 kW, 100-200 kW, >200 kW), and driving range (0-250 miles, 251-500 miles, >500 miles)

• Analysis of reported and modeled annual revenues specific to fuel cell vehicle portfolios and hydrogen powertrain divisions

• Coverage of manufacturers representing 70-75% of global market share in 2024

• Extrapolation using bottom-up (unit shipment × ASP by country/region) and top-down (manufacturer revenue validation) approaches to derive segment-specific valuations, validated against hydrogen consumption data and fuel cell stack production capacities

下载免费样本

请填写以下表格以获取本报告的免费样本

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.