Helicobacter Pylori Test Market 摘要
根据MRFR的分析,2024年幽门螺旋杆菌检测市场规模预计为32.34亿美元。预计幽门螺旋杆菌检测行业将从2025年的34.18亿美元增长到2035年的59.52亿美元,在2025年至2035年的预测期内,年均增长率(CAGR)为5.7%。
主要市场趋势和亮点
幽门螺旋杆菌检测市场正在经历强劲增长,受到技术进步和健康意识提高的推动。
- 检测方法的技术进步正在提高幽门螺旋杆菌诊断的准确性和效率。
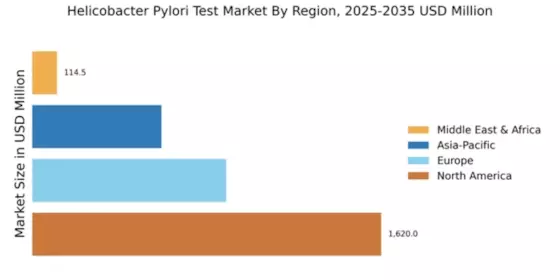
- 北美仍然是最大的市场,而亚太地区正迅速崛起为幽门螺旋杆菌检测增长最快的地区。
- 尿素呼气试验继续主导市场,而粪便抗原检测由于其非侵入性特征正在迅速增长。
- 幽门螺旋杆菌感染的发生率上升以及对胃肠健康的关注增加是推动市场扩张的关键因素。
市场规模与预测
| 2024市场规模 | 3234.48(百万美元) |
| 2035市场规模 | 5952.8(百万美元) |
| 年均增长率(2025 - 2035) | 5.7% |
主要参与者
雅培实验室(美国)、赛默飞世尔科技(美国)、罗氏诊断(瑞士)、西门子医疗(德国)、Bio-Rad实验室(美国)、霍洛吉克(美国)、梅里迪安生物科学(美国)、基因组公司(西班牙)、Eiken化学(日本)



 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA


