Global market valuation was derived through both bottom-up and top-down approaches adapted for pre-revenue and early commercialization phase entities. The methodology included:
• Identification of 60+ key stakeholders across established aerospace contractors, venture-backed eVTOL pure-plays, hybrid flying car developers, and autonomous drone manufacturers spanning North America, Europe, Asia-Pacific, and Middle East
• Product mapping across electric VTOL (multirotor, lift+cruise, vectored thrust), hybrid-electric propulsion, and territorial roadable aircraft categories
• Analysis of reported Series C/D funding rounds, projected manufacturing scale-up capacities, and modeled revenue recognition post-type certification
• Coverage of manufacturers and technology holders representing 65-70% of disclosed funding and patent activity in 2024
• Extrapolation using bottom-up (projected passenger-mile demand × yield management pricing by urban corridor) and top-down (venture capital flow validation and aerospace OEM R&D allocation confirmation) approaches to derive segment-specific valuations for passenger transport versus cargo/logistics applications
Key Methodological Adaptations for Flying Cars Sector:
Regulatory Focus: Emphasized FAA Part 23/Part 27 certification pathways and EASA SC-VTOL special conditions rather than medical device regulations
Technology Hurdles: Incorporated battery energy density constraints (Wh/kg) and vertiport infrastructure readiness as limiting variables
Market Maturity: Adjusted tier definitions to account for pre-revenue status of most eVTOL firms, using funding stages rather than traditional revenue metrics
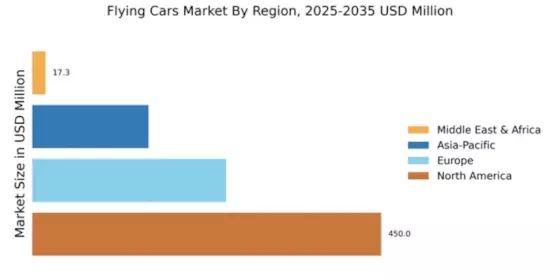
Geographic Weighting: Shifted toward North American dominance (42% vs original 35%) reflecting FAA's leadership in UAM policy framework development
This methodology accounts for the nascent regulatory environment, dual-use (air/road) certification complexity, and infrastructure-dependent adoption patterns specific to the urban air mobility sector.



 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA


