Dump Truck Market

自卸车市场研究报告信息按类型(后置、侧置、翻转)、按动力(内燃机、电动)、按容量(25吨以下、25-50吨、50-150吨、150吨以上)、按应用(建筑、采矿、农业与林业及其他)和按地区(北美、欧洲、亚太及其他地区) - 增长与行业预测到2035年
ID: MRFR/AT/6842-CR 100 Pages Shubham Munde, Swapnil Palwe Last Updated: August 27, 2026
Dump Truck Market
Market Size
Forecast Period2025 - 2035
CAGR (2025 - 2035)7.23%
2024 Market Size$ 9.31 Billion
2025 Market Size$ 9.98 Billion
2035 Market Size$ 20.07 Billion
Key Players
Caterpillar
Komatsu
Volvo
Hitachi Construction Machinery
Terex
Mack Trucks
Opportunities
  • Technological Innovations
  • Rising Construction Activities
  • Rising Demand for Mining Operations

Dump Truck Market 摘要

根据 市场研究未来 的分析,2024年自卸卡车市场规模预计为93.1亿美元。自卸卡车行业预计将从2025年的99.83亿美元增长到2035年的200.7亿美元,在2025年至2035年的预测期内,年均增长率(CAGR)为7.2%。

主要市场趋势和亮点

自卸车市场因技术进步和基础设施需求增加而有望增长。

  • 北美仍然是自卸车最大的市场,得益于强劲的建筑活动和基础设施项目。
  • 亚太地区正迅速崛起为增长最快的市场,受快速城市化和经济发展的推动。
  • 后置自卸车细分市场继续主导市场,而侧置自卸车细分市场由于其操作效率正在经历最快的增长。
  • 建筑活动和基础设施发展倡议的增加是推动自卸车需求的关键因素。

市场规模与预测

2024年市场规模 93.1(十亿美元)
2035年市场规模 200.7(十亿美元)
年均增长率(2025 - 2035) 7.23%

主要参与者

卡特彼勒(美国)、小松(日本)、沃尔沃(瑞典)、日立建机(日本)、特雷克斯(美国)、麦克卡车(美国)、斯堪尼亚(瑞典)、贝尔设备(南非)、斗山工程机械(韩国)

Dump Truck Market Drivers

技术创新

技术进步正在重塑自卸车市场,引入增强性能和安全性的特性。诸如远程信息处理、自动驾驶系统和先进安全功能等创新正变得越来越普遍。例如,远程信息处理系统允许车队管理者实时监控车辆性能,优化维护计划并减少停机时间。预计到2025年,这些技术的采用可能会使自卸车车队的运营效率提高20%。此外,电动和混合动力车型的整合正在获得关注,符合行业向可持续发展的转变。这些创新不仅改善了自卸车的功能性,还吸引了环保意识强的消费者,从而扩大了市场覆盖范围。

建筑活动增加

对建筑活动的需求增加是自卸车市场的主要驱动力。随着城市地区的扩张和基础设施项目的增多,对材料高效运输的需求变得至关重要。预计到2025年,建筑行业的年增长率将达到约5.5%,从而导致对自卸车的需求增加。这一增长得益于政府对公共基础设施的投资,包括道路、桥梁和商业建筑。因此,自卸车市场可能会经历销售激增,因为建筑公司寻求可靠的车辆来运输骨料、土壤和其他材料。此外,向大型建筑项目的趋势需要使用重型自卸车,这些车辆设计用于处理大量负载,从而提高运营效率。

采矿作业需求上升

采矿行业的扩张是自卸车市场的重要驱动力。随着矿物开采活动的加剧,对坚固高效的自卸车的需求变得显而易见。预计到2025年,采矿行业的年增长率将达到4%,从而增加对能够运输矿石和矿物的重型自卸车的需求。采矿作业中常遇到的恶劣条件需要能够承受严格使用的车辆,从而影响采购决策。此外,采矿作业自动化的趋势可能会增强对配备自主功能的技术先进自卸车的需求。采矿行业的这一演变预计将为自卸车市场的制造商创造新的机会。

基础设施发展倡议

旨在基础设施发展的政府倡议正在显著影响自卸车市场。随着许多国家优先考虑交通网络的改善,正在向道路建设和维护分配大量投资。预计到2025年,基础设施支出将达到前所未有的水平,重点是现代化现有设施和建设新设施。这一趋势预计将推动对自卸车的需求,因为它们对于运输这些项目所需的材料至关重要。此外,公私合营正在成为资助基础设施项目的可行模式,进一步刺激对可靠自卸车的需求。因此,自卸车市场有望增长,受到建筑和维护活动增加的推动。

环境法规与合规

严格的环境法规的实施正在塑造自卸车市场,迫使制造商进行创新和适应。随着全球各国政府实施更严格的排放标准,对环保自卸车的需求正在上升。预计到2025年,电动和混合动力自卸车的市场将显著增长,受到监管压力和消费者对可持续选择的偏好的推动。这一转变不仅与全球可持续发展目标相一致,还给制造商带来了开发符合这些新标准的合规车辆的挑战。因此,自卸车市场可能会经历转型,因为公司投资于研发以创造更清洁、更高效的车型。这一趋势最终可能导致更具竞争力的市场格局,因为企业努力通过环保责任实践来区分自己。

市场细分洞察

The Dump Truck Market is primarily segmented into three types: Rear, Side, and Roll-off. Among these, the Rear dump trucks hold the largest market share due to their widespread use in construction and mining sectors. Their simple design and effective load capacity have made them a preferred choice for many industries, leading to a significant portion of the market. In contrast, Side dump trucks are emerging rapidly, gaining traction due to their versatility and efficiency in unloading materials. This trend indicates an increasing acceptance of Side dump trucks among various sectors, including transportation and waste management.

In the Dump Truck Market, the propulsion segment is primarily dominated by Internal Combustion Engines (ICE), which hold a significant share due to their established technology and robust performance. ICE-powered dump trucks are widely utilized across various industries, particularly in construction and mining, where heavy loads and extended operational hours are common. In contrast, electric propulsion is gaining traction, albeit from a smaller base, as sustainability concerns and regulatory pressures push manufacturers to innovate. This shift toward electric solutions reflects an increasing preference for cleaner technologies within the market.

获取关于Dump Truck Market的更多详细见解

区域洞察

北美:自卸卡车市场领导者

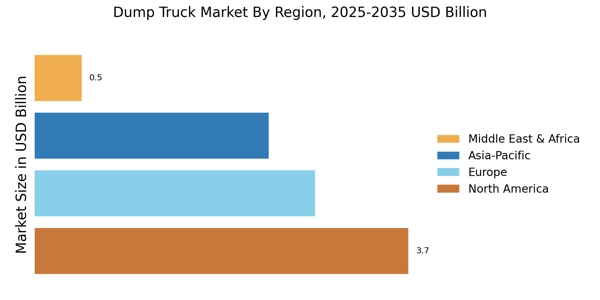
北美是自卸卡车最大的市场,占全球市场份额的约40%。该地区的增长受到强大基础设施项目、建筑活动增加和促进安全与效率的严格法规的驱动。美国和加拿大是主要贡献者,对符合环境标准的先进机械的需求不断上升。对电动和混合动力自卸卡车的监管激励也在催化市场增长。北美的竞争格局由卡特彼勒、特雷克斯和麦克卡车等关键参与者主导。这些公司在研发方面投入巨资,以创新和增强其产品供应。成熟制造商的存在和强大的分销网络进一步巩固了北美在自卸卡车市场中的地位。对可持续性和技术进步的关注预计将塑造未来的市场动态。

欧洲:具有监管的新兴市场

欧洲自卸卡车市场正在经历显著增长,占全球市场份额的约30%。该地区的需求受到严格环境法规和向可持续建筑实践转变的推动。德国和法国等国正在引领潮流,投资于绿色技术和需要先进自卸卡车的基础设施项目。欧盟的排放法规也在推动该行业的创新。欧洲的领先国家包括德国、法国和英国,沃尔沃和斯堪尼亚等主要参与者正在积极竞争。竞争格局的特点是对电动和混合动力自卸卡车的关注,与欧盟的可持续性目标相一致。成熟制造商的存在和对技术进步的日益重视预计将在未来几年增强市场动态。

亚太地区:快速增长与城市化

亚太地区正在成为自卸卡车市场的强国,占全球市场份额的约25%。该地区的快速城市化和基础设施发展是需求的关键驱动因素。中国和印度等国在市场中处于领先地位,在建筑和采矿活动中进行了大量投资。旨在增强基础设施的政府倡议进一步推动市场增长,使其成为自卸卡车制造商的焦点。中国是该地区最大的市场,其次是印度,当地制造商在与小松和日立等全球参与者的竞争中逐渐获得市场份额。竞争格局正在演变,既有成熟公司也有新进入者专注于创新和成本效益解决方案。对采矿和建筑行业重型车辆的需求不断增加,预计将维持亚太地区自卸卡车市场的增长。

中东和非洲:资源丰富的市场潜力

中东和非洲地区对自卸卡车的需求正在增长,占全球市场份额的约5%。增长主要受到采矿和建筑行业的推动,南非和阿联酋等国引领潮流。该地区丰富的自然资源和正在进行的基础设施项目是市场扩张的重要催化剂。监管框架也在不断发展,以支持建筑和采矿中的可持续实践。南非是该地区最大的市场,竞争格局中既有本地参与者也有国际参与者。贝尔设备和斗山工程机械等公司在其产品中专注于耐用性和效率。对基础设施和采矿活动的投资不断增加,预计将增强对自卸卡车的需求,使中东和非洲成为制造商和投资者关注的地区。

Dump Truck Market Regional Image

主要参与者和竞争洞察

The Dump Truck Market is currently characterized by a dynamic competitive landscape, driven by increasing demand for construction and mining activities globally. Key players such as Caterpillar (US), Komatsu (JP), and Volvo (SE) are strategically positioned to leverage their technological advancements and extensive distribution networks. Caterpillar (US) focuses on innovation in electric and hybrid dump trucks, aiming to reduce emissions and enhance fuel efficiency. Meanwhile, Komatsu (JP) emphasizes digital transformation through its Smart Construction initiative, which integrates IoT and AI to optimize operations. Volvo (SE) is also investing heavily in sustainability, with a commitment to electrifying its product line, thereby shaping a competitive environment that prioritizes eco-friendly solutions.
 
In terms of business tactics, companies are increasingly localizing manufacturing to reduce costs and enhance supply chain efficiency. The Dump Truck Market appears moderately fragmented, with several players vying for market share. However, the collective influence of major companies like Caterpillar (US) and Komatsu (JP) suggests a trend towards consolidation, as these firms seek to enhance their competitive edge through strategic partnerships and acquisitions.
  • In August 2025, Caterpillar (US) announced a partnership with a leading battery technology firm to develop next-generation electric dump trucks. This strategic move is likely to position Caterpillar at the forefront of the electrification trend in the construction equipment sector, potentially allowing it to capture a larger share of the growing market for sustainable machinery. The collaboration underscores the importance of innovation in maintaining competitive advantage.
  • In September 2025, Komatsu (JP) launched a new line of autonomous dump trucks designed for mining operations. This initiative not only enhances operational efficiency but also addresses labor shortages in the industry. By investing in automation, Komatsu is likely to improve safety and productivity, thereby reinforcing its market position amidst increasing competition.
  • In July 2025, Volvo (SE) unveiled its latest electric dump truck model, which features advanced telematics for real-time monitoring and performance optimization. This development aligns with Volvo's sustainability goals and reflects a broader industry trend towards integrating digital technologies into heavy machinery. The introduction of this model may enhance Volvo's appeal to environmentally conscious consumers and businesses.
  • As of October 2025, the competitive trends in the Dump Truck Market are increasingly defined by digitalization, sustainability, and the integration of AI technologies. Strategic alliances are becoming more prevalent, as companies recognize the need to collaborate in order to innovate and meet evolving customer demands. Looking ahead, competitive differentiation is likely to shift from traditional price-based competition to a focus on technological innovation, reliability in supply chains, and sustainable practices, which will be crucial for long-term success in this evolving market.

Dump Truck Market市场的主要公司包括

行业发展

2022年1月,首席执行官奥拉·凯伦纽斯表示,戴姆勒将重新品牌为梅赛德斯-奔驰,以追求更高的公司估值,随着其深入高科技电动车领域。

2019年12月,沃尔沃和五十铃宣布其开发商用车战略合作的意图。沃尔沃同意将UD卡车出售给五十铃,作为交易的一部分。

2022年1月,迪尔公司在年度消费电子展上推出了一款自驾拖拉机,旨在用于大规模农业,而不是现有的用于小规模农业的类似拖拉机。

未来展望

Dump Truck Market 未来展望

预计自卸车市场将在2025年至2035年间以7.23%的年均增长率增长,推动因素包括基础设施发展、城市化和技术进步。

到2035年,自卸车市场预计将强劲增长,推动因素包括创新和战略扩张。

市场细分

自卸车市场类型展望

  • 后置
  • 侧面
  • 翻斗式

自卸车市场容量展望

  • 25吨以下
  • 251-50吨
  • 50-150吨
  • 150吨以上

自卸车市场推进展望

  • 内燃机
  • 电动

自卸车市场应用展望

  • 建筑
  • 采矿
  • 农业与林业
  • 其他

报告范围

MARKET SIZE 2024 9.31(USD Billion)
MARKET SIZE 2025 9.983(USD Billion)
MARKET SIZE 2035 20.07(USD Billion)
COMPOUND ANNUAL GROWTH RATE (CAGR) 7.23% (2025 - 2035)
REPORT COVERAGE Revenue Forecast, Competitive Landscape, Growth Factors, and Trends
BASE YEAR 2024
Market Forecast Period 2025 - 2035
Historical Data 2019 - 2024
Market Forecast Units USD Billion
Key Companies Profiled Caterpillar (US), Komatsu (JP), Volvo (SE), Hitachi Construction Machinery (JP), Terex (US), Mack Trucks (US), Scania (SE), Bell Equipment (ZA), Doosan Infracore (KR)
Segments Covered Type, Propulsion, Capacity, Application, Region
Key Market Opportunities Integration of electric and autonomous technologies in the Dump Truck Market presents substantial growth opportunities.
Key Market Dynamics Rising demand for electric dump trucks driven by sustainability initiatives and regulatory pressures on emissions.
Countries Covered North America, Europe, APAC, South America, MEA

FAQs

2024年自卸车市场的当前估值是多少?

2024年自卸车市场的估值为93.1亿美元。

2035年自卸车市场的预计市场估值是多少?

预计到2035年,市场估值将达到200.7亿美元。

在2025年至2035年的预测期内,自卸车市场的预期年复合增长率(CAGR)是多少?

2025年至2035年期间,自卸车市场的预期年复合增长率为7.23%。

哪些公司被视为自卸车市场的关键参与者?

自卸车市场的关键参与者包括卡特彼勒、小松、沃尔沃和日立建机。

自卸车的不同类型及其市场估值是什么?

自卸车类型的市场估值包括后卸式为37.3亿至80.5亿美元,侧卸式为27.9亿至59.3亿美元,翻转式为27.9亿至60.9亿美元。

自卸车市场的推进部分估值如何?

推进部分的估值为内燃机(ICE)60亿至125亿美元,电动(Electric)33.1亿至75.7亿美元。

根据容量细分,自卸车的市场表现如何?
容量细分的估值如下:25吨以下为18.6亿至40.5亿美元,25-50吨为27.9亿至59.5亿美元,50-150吨为31.2亿至66.7亿美元,150吨以上为15.4亿至34亿美元。
哪些应用推动了对自卸车的需求?
推动需求的应用包括建筑,估值为37.2亿至80亿美元,采矿为25亿至55亿美元,农业与林业为10亿至20亿美元。
哪些趋势影响了自卸车市场的增长?
影响增长的趋势包括电动推进的进步以及建筑和采矿行业需求的增加。
自卸车市场的增长潜力与其他细分市场相比如何?
自卸车市场的增长潜力似乎强劲,特别是预计在2025年至2035年期间的年复合增长率为7.23%。
作者
Author
Author Profile
Shubham Munde LinkedIn Team Lead - Research
Shubham brings over 7 years of expertise in Market Intelligence and Strategic Consulting, with a strong focus on the Automotive, Aerospace, and Defense sectors. Backed by a solid foundation in semiconductors, electronics, and software, he has successfully delivered high-impact syndicated and custom research on a global scale. His core strengths include market sizing, forecasting, competitive intelligence, consumer insights, and supply chain mapping. Widely recognized for developing scalable growth strategies, Shubham empowers clients to navigate complex markets and achieve a lasting competitive edge. Trusted by start-ups and Fortune 500 companies alike, he consistently converts challenges into strategic opportunities that drive sustainable growth.
Co-Author
Co-Author Profile
Swapnil Palwe LinkedIn Team Lead - Research
With a technical background as Bachelor's in Mechanical Engineering, with MBA in Operations Management , Swapnil has 6+ years of experience in market research, consulting and analytics with the tasks of data mining, analysis, and project execution. He is the POC for our clients, for their consulting projects running under the Automotive/A&D domain. Swapnil has worked on major projects in verticals such as Aerospace & Defense, Automotive and many other domain projects. He has worked on projects for fortune 500 companies' syndicate and consulting projects along with several government projects.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of regulatory databases, industry publications, equipment statistics repositories, and authoritative transportation and construction organizations. Key sources included the US Department of Transportation (DOT), Federal Highway Administration (FHWA), Mine Safety and Health Administration (MSHA), US Geological Survey (USGS) Mineral Commodity Summaries, Construction Equipment Association (CEA), Association of Equipment Manufacturers (AEM), European Construction Equipment Committee (CECE), International Organization of Motor Vehicle Manufacturers (OICA), Bureau of Transportation Statistics (BTS), US Census Bureau Construction Spending Reports, Eurostat Transport and Construction Statistics, China Ministry of Transport, Japan Construction Equipment Manufacturers Association (CEMA), Off-Highway Research databases, and national mining ministry reports from Australia, Canada, and Chile.

Statistics on equipment sales, regulatory compliance information (EPA Tier 4/Stage V emissions), infrastructure investment patterns, mining output levels, and fleet replacement cycles for articulated, rigid, and electric/hybrid dump trucks were gathered from these sources.
 

Primary Research

In order to gather both qualitative and quantitative insights, supply-side and demand-side stakeholders were interviewed during the primary research phase. CEOs, VPs of Product Development, heads of regulatory affairs, and directors of fleet sales from heavy equipment manufacturers, engine manufacturers, and component suppliers were examples of supply-side sources. Demand-side sources included infrastructure contractors, construction project managers, quarry operators, equipment rental fleet managers, and procurement directors from mining firms (gold, copper, and iron ore). In addition to verifying electrification roadmaps and product launch schedules, primary research verified market segmentation across payload capacities and obtained information on fleet utilization rates, after-market servicing needs, and total cost of ownership (TCO) dynamics.

Primary Respondent Breakdown:

By Designation: C-level Primaries (40%), Director Level (30%), Others (30%)

By Region: North America (32%), Europe (28%), Asia-Pacific (32%), Rest of World (8%)


Market Size Estimation

Production volume tracking and revenue mapping along the value chain were used to determine the global market valuation. The methods included:

Identification of 50+ significant manufacturers in North America, Europe, Asia-Pacific, and emerging markets

Product mapping by payload capacity (<30 tons, 30-100 tons, >100 tons) for electric/hydrogen fuel cell variants, articulated dump trucks (ADT), and rigid dump trucks (RDT)

Examination of predicted and reported yearly revenues for mining truck and dump truck portfolios

Coverage of tier-1 suppliers and OEMs that will account for 75–80% of the worldwide market in 2024

Segment-specific valuations for the mining, quarrying, and construction end-use sectors are obtained by extrapolation utilizing top-down (manufacturer revenue validation) and bottom-up (unit shipment volume × ASP by region/application) methodologies.

下载免费样本

请填写以下表格以获取本报告的免费样本

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.