5G Fixed Wireless Access Market

5G 固定无线接入市场规模、份额和研究报告,按产品(硬件、服务)、地区(城市、半城市、农村)、应用(住宅、商业、工业、政府)和区域(北美、欧洲、南美、亚太、中东和非洲) - 行业预测至 2035 年
ID: MRFR/SEM/6092-HCR 200 Pages Ankit Gupta, Shubham Munde Last Updated: September 27, 2026
5G Fixed Wireless Access Market
Market Size
Forecast Period2025 - 2035
CAGR (2025 - 2035)32.54%
2024 Market Size$ 19.15 Billion
2025 Market Size$ 25.38 Billion
2035 Market Size$ 424.68 Billion
Key Players
Verizon
AT&T
T-Mobile
Huawei
Nokia
Ericsson
Opportunities
  • Increased Adoption of IoT Devices
  • Government Initiatives and Funding
  • Expansion of Smart City Initiatives

5G Fixed Wireless Access Market 摘要

主要市场趋势和亮点

市场规模与预测

CAGR (2025 - 2035) 32.54%

主要参与者

Verizon (US), AT&T (US), T-Mobile (US), Huawei (CN), Nokia (FI), Ericsson (SE), Samsung (KR), ZTE (CN), Comcast (US), Cox Communications (US) — leading telecom FWA providers and global FWA vendors driving innovation in fixed wireless 5G deployments.

5G Fixed Wireless Access Market Drivers

物联网设备的普及

物联网(IoT)设备的激增正在显著影响5G固定无线接入市场。随着越来越多的设备互联互通,对高速和低延迟互联网连接的需求愈加迫切。5G固定无线接入市场技术非常适合支持大量物联网设备,实现无缝通信和数据传输。这一趋势在各个行业中物联网应用的数量不断增长中得到了体现,包括医疗、农业和制造业。预计随着企业和消费者越来越依赖物联网解决方案以提高效率和创新,市场将见证显著增长。因此,支持不断扩展的物联网生态系统及其相关数据需求的5G固定无线接入市场的需求可能会增加。

政府倡议和资金

政府倡议和资金在塑造5G固定无线接入市场中发挥着至关重要的作用。许多政府认识到先进电信基础设施对经济增长和竞争力的重要性。因此,他们正在投资5G技术,以增强在服务不足地区的连接性。这些倡议通常包括补贴、赠款和公私合营伙伴关系,旨在加速5G固定无线接入市场网络的部署。这种支持可能会通过鼓励服务提供商扩展其产品和覆盖更多客户来刺激市场增长。此外,促进数字包容性和技术进步的政府政策预计将为5G固定无线接入市场创造有利环境,推动该领域进一步的投资和创新。

智能城市倡议的扩展

5G固定无线接入市场有望受益于智能城市倡议的扩展。随着城市地区越来越多地整合技术以改善基础设施和服务,对高速互联网连接的需求变得至关重要。5G固定无线接入市场提供必要的带宽,以支持各种智能城市应用,包括交通管理、公共安全和环境监测。这些技术的实施需要一个强大的通信网络,而5G能够有效提供。此外,城市正在投资5G基础设施,以提高居民的生活质量,这表明5G固定无线接入市场有强大的增长潜力。这一趋势表明,随着越来越多的城市采用智能技术,对5G连接的需求可能会增加,从而进一步推动市场扩展。

竞争格局与创新

5G固定无线接入市场的竞争格局以快速创新和技术进步为特征。随着越来越多的参与者进入市场,公司被迫通过增强的服务和功能来区分其产品。这种竞争压力可能会导致开发新的解决方案,以满足多样化的客户需求,包括提高可靠性、速度和覆盖范围。此外,技术提供商、电信公司和基础设施开发商之间的合作与联盟变得越来越普遍。这些联盟旨在利用互补优势,加速5G固定无线接入市场解决方案的部署。市场内持续的创新表明了一个动态环境,在这里公司不断努力提升其服务产品,最终使消费者和企业都受益。

对远程工作解决方案的需求上升

5G固定无线接入市场正在经历对远程工作解决方案的显著需求激增。随着组织越来越多地采用灵活的工作安排,对可靠和高速互联网连接的需求变得至关重要。这一趋势通过远程工作者数量的显著增加得到了证明,这导致了对提供强大互联网服务的高度关注。5G固定无线接入市场技术提供了一种可行的解决方案,使企业能够在没有传统有线基础设施限制的情况下保持生产力和连接性。此外,随着越来越多的公司认识到5G技术在增强员工协作和沟通方面的好处,预计市场将继续增长。这一向远程工作的转变可能会推动对5G固定无线接入市场的投资,从而扩大其市场存在。

市场细分洞察

按产品:硬件(最大)与服务(增长最快)

在5G固定无线接入市场中,硬件部分占据了大多数,拥有较大的市场份额。该部分包括路由器、天线和客户前提设备等关键组件,这些组件对于固定无线5G部署至关重要。服务部分虽然市场份额较小,但被认为是增长最快的,受到安装、网络优化和生命周期管理服务需求上升的推动。这些服务包括5G网络的安装、维护和支持,随着越来越多的用户迁移到5G解决方案,对持续技术支持和系统优化的需求不断增加。

硬件(主导)与服务(新兴)

硬件部分在5G固定无线接入市场中仍然是主导力量,受到先进技术创新和基础设施不断推出的推动。该部分提供广泛的设备,确保无缝连接,包括高性能路由器和设计用于在5G网络中高效运行的先进天线。另一方面,服务部分正在迅速崛起,满足硬件组件的现场安装、维护和管理。随着组织向这一技术过渡,对保证性能可靠性的综合服务套餐的需求持续增长。硬件和服务的结合对于确保强大而高效的5G FWA生态系统至关重要。

按地区:城市(最大)与农村(增长最快)

在5G固定无线接入市场中,按地区划分显示出市场份额的明显模式。城市地区主导着5G固定无线接入市场,得益于密集的基础设施和高消费需求。然而,农村地区正在迅速崛起,因为政府和电信FWA提供商努力通过可扩展和具有成本效益的无线宽带解决方案来弥合连接差距。

城市(主导)与农村(新兴)

5G固定无线接入市场中的城市部分以其广泛的基础设施和高客户集中度为特征,包括住宅和商业用户。该部分依赖于先进技术的可用性和对快速、可靠互联网的需求,以支持从智能城市倡议到远程办公的众多应用。相反,农村部分正在迅速崛起,服务提供商部署旨在改善偏远地区连接的解决方案。促进数字包容的政府倡议和对可靠互联网服务需求的上升是这一新兴地区增长的关键推动因素。总体而言,尽管城市地区仍然占主导地位,但随着针对其特定需求的解决方案的开发,农村市场有望显著增长。

按应用:住宅(最大)与商业(增长最快)

在5G固定无线接入市场中,应用部分由住宅部门主导,占据了市场的大部分份额。这一主导地位归因于家庭对高速互联网连接需求的增加,受到智能设备和数字服务数量上升的推动。商业部门虽然稍显滞后,但展现出显著的增长潜力,因为企业寻求利用更优越的连接来提高运营效率。趋势分析表明,住宅应用将继续发挥关键作用,但商业部门正在迅速崛起,成为关键参与者。远程工作的转变和数字技术的采用等因素正在推动这一增长。此外,5G基础设施的进步使服务提供商能够为各种商业用途提供可靠的连接,推动该部门超越其他部门。

住宅(主导)与工业(新兴)

在5G固定无线接入市场中,住宅应用作为主导部分脱颖而出,受到消费者对不间断在线访问的强烈需求的推动。许多家庭正在过渡到5G,以支持流媒体和游戏等高带宽活动。相比之下,工业应用虽然目前处于新兴阶段,但随着行业认识到5G技术在自动化流程和增强数据传输能力方面的好处,正在获得动力。该部门越来越多地采用5G解决方案以支持物联网应用,提高效率并减少停机时间。随着行业的数字化,强大的固定无线接入解决方案的需求可能会扩大,使工业应用成为一个有前景的增长领域,与住宅部门的稳定性并行发展。

获取关于5G Fixed Wireless Access Market的更多详细见解

区域洞察

北美:引领创新与采用

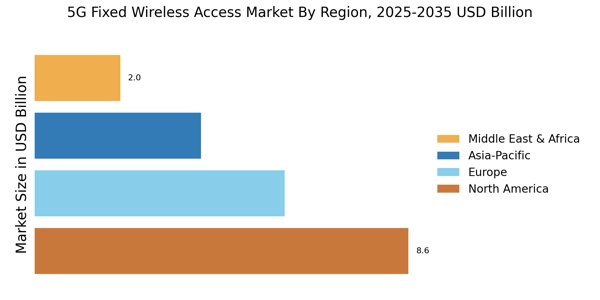
北美是5G固定无线接入市场最大的区域贡献者,得益于美国和加拿大5G固定无线接入市场的强大投资和全国宽带战略。美国政府在分配5G频谱方面积极主动,这催化了投资和基础设施的发展。竞争格局强劲,Verizon、AT&T和T-Mobile等主要参与者引领潮流。这些公司正在大力投资于扩展其5G网络、增强服务产品和改善客户体验。成熟电信巨头和创新初创公司的存在进一步推动了市场增长,使北美成为5G进步的焦点。

欧洲:新兴的监管框架

欧洲在全球5G固定无线接入市场中占据重要份额,欧洲5G固定无线接入市场,包括德国、法国、意大利和西班牙的5G固定无线接入市场,因监管支持和数字包容倡议而获得强劲动力。欧洲委员会设定了雄心勃勃的5G部署目标,刺激了成员国的投资和创新。德国、法国和英国等领先国家在这一转型中处于前沿,诺基亚和爱立信等主要电信运营商发挥了关键作用。竞争格局以电信公司与技术提供商之间的合作为特征,促进了5G服务的动态环境。对可持续性和数字包容的关注进一步增强了该地区的市场潜力。

亚太地区:快速扩张与采用

亚太地区在中国和印度的5G固定无线接入市场中见证了快速采用,得益于大规模城市化、政府支持的5G推广和不断扩大的企业需求。中国和韩国等国正在引领潮流,在5G基础设施和技术方面进行重大投资。中国凭借华为和中兴等公司在市场中占据主导地位,而韩国因其先进的5G网络而受到认可。竞争格局以电信运营商和技术公司之间的积极扩张策略和合作为特征。这种协作方式预计将推动该地区进一步的创新和服务提升。

中东和非洲:未开发的潜力与增长

中东在GCC 5G固定无线接入市场中显示出日益增长的潜力,各国正在投资下一代连接,以支持智慧城市发展和数字经济。增长受到对高速互联网和移动连接需求增加的推动,特别是在城市地区。各国政府开始认识到数字基础设施的重要性,推动了旨在促进5G部署的监管举措。南非和阿联酋等国在5G采用方面处于领先地位,当地电信运营商正在投资基础设施建设。竞争格局仍在发展,既有成熟参与者也有新进入者。随着该地区继续投资于技术和连接,5G市场的增长潜力显著。

5G Fixed Wireless Access Market Regional Image

主要参与者和竞争洞察

5G固定无线接入市场正在经历显著增长,电信公司和服务提供商越来越多地利用先进技术来增强连接解决方案。该市场的特点是由创新、基础设施投资和对高速互联网服务日益增长的需求驱动的激烈竞争。竞争格局显示出多种参与者努力利用5G技术的优势,公司专注于开发强大的网络能力并有效满足客户需求。该市场中的战略合作伙伴关系、并购是日益增长的整合努力的指标,以最大化覆盖范围并增强服务产品,确保在新兴市场挑战面前的竞争地位。中国移动在5G固定无线接入市场中占据领先地位,凭借其庞大的用户基础和广泛的网络基础设施展现出强大的存在。该公司的优势在于能够提供可靠和高速的连接解决方案,满足城市和农村地区的需求,从而缩小数字鸿沟。通过对5G技术的重大投资和扩展服务范围的承诺,中国移动不断增强其产品供应。该公司对以客户为中心的解决方案和创新服务模式的重视使其在竞争格局中有效定位,使其能够利用现有的电信基础设施快速部署固定无线接入解决方案,从而获得竞争优势。Cradlepoint是5G固定无线接入市场中的另一个显著参与者,专注于为企业应用提供无线边缘解决方案。该公司的主要产品包括一系列云管理的故障转移解决方案和无线广域网路由器,旨在为商业用户提供无缝连接和灵活性。Cradlepoint的市场存在得益于与电信提供商的强大合作关系以及其致力于提供适合多种环境的可扩展和可靠的无线解决方案。该公司的优势包括其技术创新和适应快速变化的数字环境需求的能力。作为其增长战略的一部分,Cradlepoint参与了多项并购,扩展了其在5G解决方案方面的能力,使其能够增强服务产品组合并巩固其在全球市场中的地位,从而促进该地区固定无线接入的整体扩展。

5G Fixed Wireless Access Market市场的主要公司包括

Recent Industry Developments

  • Q3 2026: Verizon (US): Verizon reported 193,000 fixed wireless access net additions in Q2 2026, bringing total fixed-wireless and fiber broadband connections to approximately 17.1 million, demonstrating continued expansion of its 5G-based broadband subscriber base.

  • Q3 2026: Huawei (CN): Huawei and MTN Group signed a 2026 strategic MoU covering coordinated FTTH and 5G FWA development, including affordable CPE solutions and joint go-to-market approaches intended to accelerate home-broadband growth in Africa.

  • Q3 2026: Samsung (KR): Samsung and Qualcomm validated 5G Power Class 1 capability for FWA through Samsung’s virtualized RAN and Qualcomm’s FWA Gen 4 platform, targeting improved uplink performance, signal quality and coverage in challenging locations.

  • Q2 2024: Verizon expands 5G Home Internet to more cities, bringing fixed wireless access to millions Verizon announced the expansion of its 5G Home Internet service, a fixed wireless access offering, to additional U.S. cities in Q2 2024, increasing its coverage to millions of new households and small businesses.
  • Q2 2024: T-Mobile launches 5G Home Internet in new markets, accelerating fixed wireless access rollout T-Mobile expanded its 5G Home Internet fixed wireless access service to several new markets in Q2 2024, aiming to reach more rural and suburban customers with high-speed broadband.
  • Q2 2024: AT&T launches 5G fixed wireless access for business customers in select U.S. cities AT&T introduced a new 5G fixed wireless access solution for business customers in select U.S. cities, targeting enterprises seeking high-speed, reliable connectivity without fiber.
  • Q2 2024: Nokia launches new 5G FWA platform to accelerate broadband deployments Nokia unveiled a new 5G fixed wireless access platform in Q2 2024, designed to help operators rapidly deploy broadband services in underserved and rural areas.
  • Q2 2024: Samsung introduces next-generation 5G FWA CPE for global markets Samsung launched its latest 5G fixed wireless access customer premises equipment (CPE) in Q2 2024, targeting global operators seeking to expand high-speed broadband offerings.
  • Q2 2024: Ericsson and Telstra partner to deliver 5G fixed wireless access in Australia Ericsson announced a partnership with Telstra in Q2 2024 to deploy 5G fixed wireless access solutions, aiming to enhance broadband connectivity in urban and regional Australia.
  • Q2 2024: Vodafone launches 5G fixed wireless access service in Germany Vodafone introduced a new 5G fixed wireless access broadband service in Germany in Q2 2024, targeting both residential and business customers.
  • Q3 2024: Orange launches 5G FWA pilot in rural France Orange began a pilot program for 5G fixed wireless access in rural France in Q3 2024, aiming to bridge the digital divide in underserved communities.
  • Q3 2024: Deutsche Telekom expands 5G fixed wireless access to new regions in Germany Deutsche Telekom expanded its 5G fixed wireless access service to additional regions in Germany in Q3 2024, focusing on areas with limited fiber infrastructure.
  • Q3 2024: Rakuten Mobile launches 5G fixed wireless access service in Japan Rakuten Mobile launched a new 5G fixed wireless access service in Japan in Q3 2024, targeting both urban and rural customers seeking high-speed internet.
  • Q3 2024: BT unveils 5G fixed wireless access solution for UK businesses BT introduced a 5G fixed wireless access solution for business customers in the UK in Q3 2024, offering an alternative to traditional broadband.
  • Q3 2024: China Mobile launches nationwide 5G fixed wireless access service China Mobile rolled out a nationwide 5G fixed wireless access service in Q3 2024, aiming to provide high-speed broadband to millions of households across China.

未来展望

5G Fixed Wireless Access Market 未来展望

5G 固定无线接入市场预计将在 2025 年至 2035 年期间以 32.54% 的年复合增长率增长,推动因素是对高速互联网的需求增加和电信基础设施的进步。

到 2035 年,市场预计将实现显著增长,巩固其在全球电信中的角色。

市场细分

5G 固定无线接入市场产品展望

  • 硬件
  • 服务

5G 固定无线接入市场区域展望

  • 城市
  • 半城市
  • 农村

5G 固定无线接入市场应用展望

  • 住宅
  • 商业
  • 工业
  • 政府

报告范围

2024年市场规模 191.5(亿美元)
2025年市场规模 253.8(亿美元)
2035年市场规模 4246.8(亿美元)
年均复合增长率(CAGR) 32.54%(2025 - 2035)
报告覆盖范围 收入预测、竞争格局、增长因素和趋势
基准年 2024
市场预测期 2025 - 2035
历史数据 2019 - 2024
市场预测单位 亿美元
关键公司简介 Verizon(美国),AT&T(美国),T-Mobile(美国),华为(中国),诺基亚(芬兰),爱立信(瑞典),三星(韩国),中兴(中国),康卡斯特(美国),考克斯通讯(美国)
覆盖的细分市场 产品、地区、应用、区域
关键市场机会 通过增强的5G固定无线接入基础设施扩展农村宽带接入。
关键市场动态 对高速互联网的需求上升推动了5G固定无线接入市场的竞争和创新。
覆盖的国家 北美、欧洲、亚太、南美、中东和非洲

Frequently Asked Questions

5G固定无线接入市场目前的估值是多少?

截至2024年,市场估值为191.5亿美元。

到2035年,5G固定无线接入市场的预计市场规模是多少?

预计到2035年,市场将达到4246.8亿美元。

在预测期内,5G固定无线接入市场的预期年均增长率是多少?

预计2025年至2035年间,市场的年均增长率为32.54%。

哪些公司被视为5G固定无线接入市场的关键参与者?
关键参与者包括Verizon、AT&T、T-Mobile、华为、诺基亚、爱立信、三星、中兴、康卡斯特和考克斯通信。
5G固定无线接入市场的产品如何细分?

市场分为硬件,估值为171.17亿美元,以及服务,估值为253.51亿美元。

5G固定无线接入市场的地域细分是什么?

地域细分包括城市,估值为175.0亿美元,半城市为150.0亿美元,农村为99.68亿美元。

哪些应用推动了5G固定无线接入市场的发展?

应用包括住宅,估值为175.0亿美元,商业为100.0亿美元,工业为75.0亿美元,政府为74.68亿美元。

城市地区的市场表现与农村地区相比如何?

城市地区的估值为175.0亿美元,高于农村地区的99.68亿美元。

主要电信公司在市场中扮演什么角色?
像Verizon和AT&T这样的主要电信公司在推动创新和市场增长方面至关重要。
未来几年预计会有哪些趋势影响5G固定无线接入市场?

趋势表明服务产品将迅速扩展,并在城市和半城市地区的采用率将增加。

作者
Author Author Profile Ankit Gupta LinkedIn Team Lead - Research
Ankit Gupta is a seasoned market intelligence and strategic research professional with over six plus years of experience in the ICT and Semiconductor industries. With academic roots in Telecom, Marketing, and Electronics, he blends technical insight with business strategy. Ankit has led 200+ projects, including work for Fortune 500 clients like Microsoft and Rio Tinto, covering market sizing, tech forecasting, and go-to-market strategies. Known for bridging engineering and enterprise decision-making, his insights support growth, innovation, and investment planning across diverse technology markets.
Co-Author Co-Author Profile Shubham Munde LinkedIn Team Lead - Research
Shubham brings over 7 years of expertise in Market Intelligence and Strategic Consulting, with a strong focus on the Automotive, Aerospace, and Defense sectors. Backed by a solid foundation in semiconductors, electronics, and software, he has successfully delivered high-impact syndicated and custom research on a global scale. His core strengths include market sizing, forecasting, competitive intelligence, consumer insights, and supply chain mapping. Widely recognized for developing scalable growth strategies, Shubham empowers clients to navigate complex markets and achieve a lasting competitive edge. Trusted by start-ups and Fortune 500 companies alike, he consistently converts challenges into strategic opportunities that drive sustainable growth.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of regulatory filings, technical standards databases, peer-reviewed telecommunications journals, spectrum auction records, and authoritative telecommunications industry bodies. Key sources included the International Telecommunication Union (ITU-R and ITU-D), Global mobile Suppliers Association (GSA), 3rd Generation Partnership Project (3GPP) Technical Specification Groups, GSMA Intelligence, Organisation for Economic Co-operation and Development (OECD) Digital Economy Outlook and Broadband Statistics, U.S. Federal Communications Commission (FCC) Wireless Telecommunications Bureau, European Telecommunications Network Operators' Association (ETNO), European Electronic Communications Code (EECC), Federal Network Agency Germany (Bundesnetzagentur), Ofcom UK, Australian Communications and Media Authority (ACMA), National Telecommunications and Information Administration (NTIA), International Spectrum Management Alliance (ISMA), Ookla Speedtest Intelligence, World Bank Digital Development indicators, International Monetary Fund (IMF) World Economic Outlook, and national regulatory authority reports from key 5G markets including China Ministry of Industry and Information Technology (MIIT), Japan Ministry of Internal Affairs and Communications (MIC), South Korea Ministry of Science and ICT, and India Department of Telecommunications. These sources were used to collect 5G spectrum allocation data, FWA deployment statistics, regulatory approval timelines, network performance benchmarks, subscriber adoption metrics, equipment certification records, and competitive landscape analysis across mmWave, sub-6 GHz, and C-band deployments.


Primary Research

Qualitative and quantitative insights were obtained by interviewing supply-side and demand-side stakeholders during the primary research process. Supply-side sources consist of Chief Technology Officers, VPs of Network Infrastructure, Chief Strategy Officers, regulatory policy managers, and commercial directors from telecommunications operators, 5G infrastructure manufacturers, CPE (Customer Premises Equipment) vendors, and chipset providers. Demand-side sources included Chief Information Officers, enterprise connectivity managers, procurement leads from manufacturing facilities, logistics companies, smart city coordinators, and digital transformation heads from retail, healthcare, education, and government sectors that were deploying 5G FWA solutions. The market segmentation was validated across hardware (5G CPE units, indoor/outdoor routers, receivers) and services (consultation, installation, maintenance) through primary research. The 5G-Advanced and RedCap product pipeline timelines were confirmed, and insights on spectrum monetization strategies, network slicing configurations, and enterprise SLA dynamics were gathered.

Primary Respondent Breakdown:

By Designation: C-level Primaries (28%), Director Level (42%), Others (30%)

By Region: North America (32%), Europe (30%), Asia-Pacific (31%), Rest of World (7%)


Market Size Estimation

Global market valuation was derived through revenue mapping, CPE shipment analysis, and subscriber volume projections. The methodology included:

Identification of 50+ key ecosystem participants across network infrastructure vendors, telecommunications operators, CPE manufacturers, and chipset providers spanning North America, Europe, Asia-Pacific, and Latin America

Product mapping across hardware categories (indoor CPE, outdoor CPE, enterprise gateways, mmWave antennas) and service categories (network planning, system integration, managed services, technical support)

Analysis of reported and modeled annual revenues specific to 5G FWA product portfolios and service lines

Coverage of manufacturers and operators representing 75-80% of global market share in 2024

Extrapolation using bottom-up (subscriber volume × ARPU by country/territory) and top-down (vendor revenue validation and operator CapEx allocation) approaches to derive segment-specific valuations across residential, commercial, industrial, and government applications in urban, semi-urban, and rural deployments

Cross-validation with spectrum auction expenditure data and network deployment announcements to estimate infrastructure investment allocation toward FWA use cases versus mobile broadband

下载免费样本

请填写以下表格以获取本报告的免费样本

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.