3D Reconstruction Technology Market

3D重建技术市场规模、份额和趋势分析报告,按施工方法(主动和被动)、按类型(3D重建软件,以及基于图像和视频)、按应用(计算机辅助几何设计(CAGD)、计算机图形学和数字媒体)以及按地区(北美、欧洲、亚太和其他地区)–市场预测至2035年
ID: MRFR/ICT/3669-CR 100 Pages Aarti Dhapte Last Updated: September 19, 2026
3D Reconstruction Technology Market
Market Size
Forecast Period2025 - 2035
CAGR (2025 - 2035)12.2%
2024 Market Size$ 1.38 Billion
2025 Market Size$ 1.55 Billion
2035 Market Size$ 4.9 Billion
Key Players
Autodesk
Pix4D
3D Systems
RealityCapture
Bentley Systems
Trimble
Opportunities
  • Growing Applications in Healthcare
  • Advancements in Imaging Technologies
  • Increased Investment in Smart Cities

3D Reconstruction Technology Market 摘要

根据市场研究未来的分析,3D重建技术市场在2024年的估计为13.8亿美元。预计3D重建技术行业将从2025年的15.48亿美元增长到2035年的48.96亿美元,预测期内(2025 - 2035)的年均增长率(CAGR)为12.2%。

主要市场趋势和亮点

3D重建技术市场因技术进步和各个行业应用的增加而有望实现显著增长。

  • 人工智能和机器学习的整合正在改变3D重建技术的能力。
  • 北美仍然是最大的市场,而亚太地区正在成为该行业增长最快的地区。
  • 主动3D重建方法主导市场,而被动方法正在快速增长。
  • 对3D可视化的需求增加和成像技术的进步是推动市场扩张的关键因素。

市场规模与预测

2024市场规模 13.8(十亿美元)
2035市场规模 48.96(十亿美元)
年均增长率(2025 - 2035) 12.2%

主要参与者

Autodesk(美国),Pix4D(瑞士),3D Systems(美国),RealityCapture(斯洛伐克),Bentley Systems(美国),Trimble(美国),Zebra Technologies(美国),Matterport(美国)

3D Reconstruction Technology Market Drivers

Growing Applications in Healthcare

Advancements in Imaging Technologies

Increased Investment in Smart Cities

Increased Demand for 3D Visualization

Surge in Demand for Gaming and Entertainment

The gaming and entertainment industries are witnessing a surge in demand for immersive experiences, which is driving the 3D Reconstruction Technology Market. The rise of virtual reality (VR) and augmented reality (AR) applications necessitates the use of advanced 3D reconstruction techniques to create engaging environments. Market analysis indicates that the gaming sector alone is expected to grow at a rate of 12% annually, fueled by the increasing popularity of VR and AR games. This trend suggests that developers are investing heavily in 3D reconstruction technologies to enhance gameplay and user interaction. As the entertainment landscape evolves, the need for sophisticated 3D models and environments will likely propel the market forward.

市场细分洞察

通过建设方法:主动(最大)与被动(最快增长)

在3D重建技术市场中,主动建设方法占据了最大的市场份额,主要由于其在建筑和遗产保护等各种应用中的广泛实施。主动方法利用结构光和激光扫描技术,提供高水平的精度和细节。相反,被动方法正在获得关注,尤其是在游戏和虚拟现实等领域的快速增长,这得益于计算机视觉技术的进步和对成本效益解决方案的日益需求。

建设方法:主动(主导)与被动(新兴)

主动建设方法的特点是依赖外部光源和高度复杂的硬件来捕捉细致的细节,在市场中建立了主导地位。这些方法因其准确性和稳健性而受到青睐,使其成为需要精确测量和数据的应用的理想选择。另一方面,被动方法利用环境光和更简单的成像技术,因其成本效益和降低复杂性而迅速崛起。它们在游戏和虚拟模拟等行业的日益采用证明了它们的潜力,促使对研发的投资增加。

通过类型:3D重建软件(最大)与基于图像和视频(最快增长)

在3D重建技术市场中,细分显示3D重建软件的显著主导地位。该细分市场占据了最大的份额,受益于在娱乐、游戏、建筑和虚拟现实等行业的广泛应用。相比之下,虽然“基于图像和视频”细分市场较小,但由于移动成像技术的进步和对沉浸式体验的日益需求,展现出快速的采用。这一增长表明了一个更广泛的趋势,即改善3D内容创作的质量和可及性。

3D重建软件(主导)与基于图像和视频(新兴)

3D重建软件细分市场的特点是其已建立的存在和在从各种数据输入创建详细和准确的3D模型中的重要角色。这款软件对依赖精确可视化的行业至关重要,例如医学成像和产品设计。另一方面,“基于图像和视频”细分市场在市场中迅速崛起,受到用户生成内容和社交媒体的兴起的推动,在这些平台上,捕捉和分享体验变得越来越流行。该细分市场正在增强3D技术的可及性,使更多用户能够参与和利用3D重建,从而扩大整体市场。

通过应用:计算机辅助几何设计(CAGD)(最大)与数字媒体(最快增长)

在3D重建技术市场中,计算机辅助几何设计(CAGD)因其在汽车、航空航天和建筑等行业的广泛应用而领先于市场份额。该细分市场的良好存在使其在市场中占据主导地位,代表了整体市场收入的显著部分。相反,数字媒体细分市场虽然目前较小,但由于虚拟现实和增强现实应用的兴起,正在迅速获得关注,显著推动其增长。3D重建技术市场的增长得益于计算能力和图形渲染的进步,这增强了数字媒体等细分市场的能力。新兴技术,包括机器学习和人工智能,正在推动数字媒体中对强大应用的需求,使其成为增长最快的细分市场。CAGD正在经历稳定的增长,但数字媒体技术的快速演变表明,沉浸式体验正在重塑消费者的期望。

计算机辅助几何设计(主导)与数字媒体(新兴)

计算机辅助几何设计(CAGD)被广泛认为是3D重建技术市场中的主导应用,归因于其在制造和建筑等各个领域高精度建模和设计中的关键作用。其稳健性和可靠性使其对需要准确几何表示的专业人士不可或缺。相反,数字媒体作为一个充满活力的细分市场正在崛起,受到对互动内容和沉浸式体验日益增长的需求的推动。该细分市场涵盖3D动画、视频游戏和电影制作等应用,在这些应用中,创新的叙事和视觉效果至关重要。随着技术的进步,数字媒体与先进可视化工具的整合可能会吸引更多投资,进一步增强其增长潜力。

获取关于3D Reconstruction Technology Market的更多详细见解

区域洞察

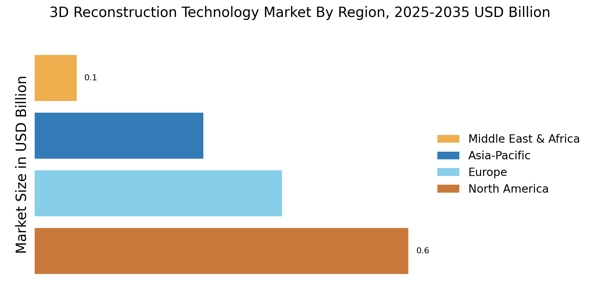
根据地区,该研究提供了北美、欧洲、亚太地区和其他地区的3D重建技术市场洞察。北美的减肥市场将主导3D重建技术市场,这得益于北美发达的基础设施,鼓励采用最新技术,如3D重建技术。在北美,3D打印活组织植入物的实验似乎是首次使用3D重建技术主要用于医疗目的。例如,在2022年6月,美国一名女性通过3D打印的活组织植入物修复了外耳。

在3D重建技术市场报告中研究的主要国家包括美国、加拿大、德国、法国、英国、意大利、西班牙、中国、日本、印度、澳大利亚、韩国和巴西。

图3:2022年按地区划分的3D重建技术市场份额(%)

亚太地区的3D重建技术市场占据第二大市场份额,因该地区对移动测绘系统的需求不断增长以及娱乐行业的快速发展都促进了市场的增长。它在建筑行业中用于弥补信息差距、协调时间表并避免设计与施工之间的潜在冲突。此外,中国的3D重建技术市场占据了最大的市场份额,而印度的3D重建技术市场是亚太地区增长最快的市场。

欧洲的3D重建技术市场预计将在2023年至2030年期间以最快的CAGR增长。市场参与者如Agisoft和Pix4D助力该地区3D重建技术的快速扩展。3D重建工具在执法和私人安全机构中可能会在大型人群聚集在会议中心、体育场和游行路线等公共场所时发挥重要作用。此外,德国的3D重建技术市场占据了最大的市场份额,而英国的3D重建技术市场是欧洲地区增长最快的市场。

例如,在2022年5月荷兰临床化学与实验室医学学会年会上,荷兰医疗机器人初创公司Vitestro展示了世界上最先进的自主抽血设备。

3D Reconstruction Technology Market Regional Image

主要参与者和竞争洞察

领先的市场参与者正在大力投资于研发,以扩展其产品线,这将进一步推动3D重建技术市场的增长。市场参与者还在进行各种战略活动,以扩大其全球足迹,重要的市场发展包括新产品发布、合同协议、并购、增加投资以及与其他组织的合作。为了在竞争日益激烈和不断上升的市场环境中扩展和生存,3D重建技术行业必须提供具有成本效益的产品。为了降低运营成本,制造商在全球3D重建技术行业中采用的关键商业策略之一是本地制造,以便为客户提供利益并扩大市场份额。近年来,3D重建技术行业为建筑行业提供了最显著的优势。3D重建技术市场的主要参与者包括Pix4D(瑞士)、Agisoft PhotoScan(荷兰)、Autodesk(美国)、Acute3D/Context Capture(现为Bentley Systems的一部分)(美国)、PhotoModeler/Eos Systems Inc.(加拿大)、Photometrix、Elcovision/PMS AG(澳大利亚)、Matterport(美国)、4Dage Technology(中国)、深圳智能(中国)和时贤科技(中国)。Matterport Inc.是一家开发软件的公司。为了数字化捕捉现实世界环境,该公司为用户提供3D相机和一个互动查看平台,使他们能够上传、扫描并在线分享扫描结果。全球客户使用Matterport的服务。例如,该公司处理Matterport, Inc.的整个开发和供应链,从硬件开发到内容创建、处理、分发和货币化。随着时间的推移,该公司通过其市场主导策略获得了更强的市场地位并实现了市场主导地位。Portfolio Management Solutions(PMS)LLC成立于2005年,专注于投资组合管理。该公司的服务线的一个关键方面是提供合同或收费的商业咨询服务。例如,PMS AG在其产品开发战略中广泛关注扩展其产品供应。大量投资于开发增强和独特的产品组合使其能够为消费者提供更好的体验。同时,它还增强软件解决方案,以提供云应用和新的创新水平给消费者。

3D Reconstruction Technology Market市场的主要公司包括

Recent Industry Developments

  • Q3 2026: Autodesk (US): No qualifying official news found within the specified 8-month period.
  • Q3 2026: 3D Systems (US): No qualifying official news found within the specified 8-month period.
  • Q3 2026: Matterport (US): Matterport introduced a workflow for importing Leica E57 point clouds and automatically generating navigable 3D digital twins, expanding the conversion of survey-grade spatial data into browser-accessible reconstructed environments.
  • Q2 2024: Matterport Announces Strategic Partnership with Autodesk to Integrate 3D Digital Twins into Construction Workflows Matterport, a leader in 3D spatial data, announced a partnership with Autodesk to integrate Matterport’s 3D digital twin technology into Autodesk Construction Cloud, enabling seamless 3D reconstruction and visualization for construction and architecture professionals.
  • Q2 2024: Pix4D Launches Pix4Dcatch RTK, Bringing Survey-Grade 3D Reconstruction to Mobile Devices Pix4D, a Swiss photogrammetry company, launched Pix4Dcatch RTK, a mobile app and hardware solution that enables survey-grade 3D reconstruction using smartphones and RTK GNSS receivers, targeting construction, surveying, and geospatial professionals.
  • Q2 2024: Bentley Systems Acquires Eagle.io to Enhance 3D Infrastructure Digital Twins Bentley Systems, a global infrastructure engineering software company, acquired Eagle.io, a cloud-based environmental data management platform, to strengthen its 3D reconstruction and digital twin capabilities for infrastructure monitoring and management.
  • Q3 2024: NVIDIA Unveils Omniverse Cloud APIs for Real-Time 3D Reconstruction in Industrial Applications NVIDIA announced new Omniverse Cloud APIs that enable real-time 3D reconstruction and simulation for industrial and manufacturing clients, expanding the use of AI-driven 3D modeling in digital twin and automation projects.
  • Q3 2024: Luma AI Raises $43M Series B to Expand Generative 3D Reconstruction Platform Luma AI, a startup specializing in generative AI for 3D reconstruction, closed a $43 million Series B funding round to accelerate development of its platform for creating photorealistic 3D models from images and video.
  • Q2 2024: Hexagon Launches BLK2GO Pulse, a Handheld LiDAR Scanner for Instant 3D Reconstruction Hexagon AB introduced the BLK2GO Pulse, a new handheld LiDAR scanner designed for rapid, on-the-go 3D reconstruction of indoor and outdoor environments, targeting architecture, engineering, and construction markets.
  • Q1 2025: Siemens and Leica Geosystems Announce Partnership to Advance 3D Reconstruction in Industrial Automation Siemens and Leica Geosystems announced a strategic partnership to integrate Leica’s 3D scanning and reconstruction technology with Siemens’ industrial automation solutions, aiming to improve digital twin accuracy in manufacturing.
  • Q2 2025: Matterport Appoints New CTO to Drive Next-Gen 3D Reconstruction Technology Market Matterport appointed Dr. Priya Raman as Chief Technology Officer to lead the company’s innovation in AI-powered 3D reconstruction and digital twin solutions for real estate, construction, and facilities management.
  • Q1 2025: Epic Games Acquires Capturing Reality to Bolster 3D Reconstruction Capabilities in Unreal Engine Epic Games acquired Capturing Reality, a leading photogrammetry software provider, to enhance 3D reconstruction features within Unreal Engine, supporting industries such as gaming, film, and architecture.
  • Q3 2024: Apple Files Patent for Real-Time 3D Reconstruction Using iPhone LiDAR Apple filed a patent for a new method enabling real-time 3D reconstruction of environments using the iPhone’s LiDAR sensor, signaling potential new features for AR and mapping applications.
  • Q2 2024: Trimble Launches X12 3D Laser Scanning System for Construction and Surveying Trimble introduced the X12, a new 3D laser scanning system designed for high-precision 3D reconstruction in construction, surveying, and civil engineering projects.
  • Q1 2025: Autodesk Acquires 3D Reconstruction Startup PointFuse to Enhance BIM Workflows Autodesk acquired PointFuse, a UK-based 3D reconstruction software company, to integrate advanced point cloud processing and mesh generation into its Building Information Modeling (BIM) solutions.

未来展望

3D Reconstruction Technology Market 未来展望

3D重建技术市场预计在2025年至2035年期间以12.2%的年均增长率增长,推动因素包括人工智能的进步、虚拟现实需求的增加以及成像技术的提升。

到2035年,市场预计将强劲增长,受创新应用和技术进步的推动。

市场细分

3D重建技术市场类型展望

  • 3D重建软件
  • 基于图像和视频

3D重建技术市场应用展望

  • 计算机辅助几何设计 (CAGD)
  • 计算机图形学
  • 数字媒体

3D重建技术市场施工方法展望

  • 主动
  • 被动

报告范围

市场规模 2024 13.8(亿美元)
市场规模 2025 15.48(亿美元)
市场规模 2035 48.96(亿美元)
年均增长率(CAGR) 12.2%(2025 - 2035)
报告覆盖范围 收入预测、竞争格局、增长因素和趋势
基准年 2024
市场预测期 2025 - 2035
历史数据 2019 - 2024
市场预测单位 亿美元
关键公司概况 Autodesk(美国),Pix4D(瑞士),3D Systems(美国),RealityCapture(斯洛伐克),Bentley Systems(美国),Trimble(美国),Zebra Technologies(美国),Matterport(美国)
覆盖的细分市场 建筑方法、类型、应用、地区
关键市场机会 人工智能的整合提高了3D重建技术市场的准确性和效率。
关键市场动态 对沉浸式体验的需求上升推动了3D重建技术市场的创新和竞争。
覆盖的国家 北美、欧洲、亚太、南美、中东和非洲

Frequently Asked Questions

2035年3D重建技术市场的预计市场估值是多少?

2035年3D重建技术市场的预计市场估值为48.96亿美元。

2024年3D重建技术市场的市场估值是多少?

2024年3D重建技术市场的市场估值为13.8亿美元。

2025年至2035年期间3D重建技术市场的预期年复合增长率是多少?

2025年至2035年期间3D重建技术市场的预期年复合增长率为12.2%。

哪些公司被认为是3D重建技术市场的关键参与者?

3D重建技术市场的关键参与者包括Autodesk、Pix4D、3D Systems、RealityCapture、Bentley Systems、Trimble、Zebra Technologies和Matterport。

3D重建技术市场的主要细分领域是什么?

3D重建技术市场的主要细分领域包括施工方法、类型和应用。

2024年施工方法类别中主动和被动细分的估值是多少?

在2024年,主动细分的估值为8.28亿美元,而被动细分的估值为5.52亿美元。

2024年3D重建软件的估值与基于图像和视频的估值相比如何?

在2024年,3D重建软件的估值为4.14亿美元,而基于图像和视频的估值为9.66亿美元。

到2035年,计算机辅助几何设计(CAGD)和计算机图形应用的预计估值是多少?

到2035年,计算机辅助几何设计(CAGD)的预计估值将达到14.88亿美元,而计算机图形的估值可能达到19.92亿美元。

3D重建技术市场中数字媒体应用细分的预期增长趋势是什么?

数字媒体应用细分预计将从2024年的4.14亿美元增长到2035年的约14.16亿美元。

3D重建技术市场在各个细分领域的增长潜力如何?

增长潜力似乎各不相同,基于图像和视频的细分预计将经历最高的估值增长,预计到2035年将达到34.08亿美元。

作者
Author Author Profile Aarti Dhapte LinkedIn AVP - Research
A consulting professional focused on helping businesses navigate complex markets through structured research and strategic insights. I partner with clients to solve high-impact business problems across market entry strategy, competitive intelligence, and opportunity assessment. Over the course of my experience, I have led and contributed to 100+ market research and consulting engagements, delivering insights across multiple industries and geographies, and supporting strategic decisions linked to $500M+ market opportunities. My core expertise lies in building robust market sizing, forecasting, and commercial models (top-down and bottom-up), alongside deep-dive competitive and industry analysis. I have played a key role in shaping go-to-market strategies, investment cases, and growth roadmaps, enabling clients to make confident, data-backed decisions in dynamic markets.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of technology standards databases, peer-reviewed computer vision journals, industry whitepapers, and authoritative governmental & standards organizations. Key sources included the National Institute of Standards and Technology (NIST), US Geological Survey (USGS), European Union Agency for the Space Programme (EUSPA/Copernicus), IEEE Standards Association, International Society for Photogrammetry and Remote Sensing (ISPRS), American Society for Photogrammetry and Remote Sensing (ASPRS), ACM SIGGRAPH, International Organization for Standardization (ISO) Technical Committee 211 (Geographic information/Geomatics), British Standards Institution (BSI) for BIM standards, National Institutes of Standard and Technology (NIST) Digital Twin consortium, and national digital infrastructure reports from key markets. These sources were used to collect technology adoption statistics, spatial data infrastructure (SDI) development metrics, clinical validation studies, patent filings, and competitive landscape analysis for active reconstruction systems (LiDAR/structured light), passive reconstruction (photogrammetry), software platforms, and image/video-based reconstruction technologies.


Primary Research

To gather both qualitative and quantitative information, the primary research process involved interviewing players from both the supply and demand sides. Members of the supply side who contributed to the discussion included CTOs, VPs of software engineering, reality capture solution product development heads, and commercial directors from companies that make 3D reconstruction software, LiDAR hardware, photogrammetry equipment, and GPUs and semiconductors. On the demand side, we had CIOs of AEC companies, BIM managers, medical imaging department heads, surgical planning experts, technical directors of game and VR companies, officers charged with protecting cultural heritage, and procurement heads of smart city development agencies. The primary research provided evidence of software pipeline timelines, verified market segmentation based on construction methods (active vs. passive), and uncovered insights regarding enterprise adoption patterns, licensing dynamics (SaaS vs. perpetual), and integration challenges with BIM and CAD ecosystems.

Primary Respondent Breakdown:

By Designation: C-level Primaries (28%), Director Level (35%), Others (37%)

By Region: North America (33%), Europe (28%), Asia-Pacific (32%), Rest of World (7%)


Market Size Estimation

Global market valuation was derived through revenue mapping, installation base analysis, and license/subscription volume tracking. The methodology included:

Identification of 35+ key manufacturers across North America, Europe, Asia-Pacific, and Latin America, encompassing pure-play reconstruction software vendors, LiDAR hardware manufacturers, photogrammetry service providers, and integrated geospatial solution companies

Product mapping across active reconstruction technologies (laser scanning, structured light), passive reconstruction (multi-view photogrammetry, shape-from-shading/monocular depth), cloud-based reconstruction platforms, and on-premise software suites

Analysis of reported and modeled annual revenues specific to 3D reconstruction portfolios, including SaaS recurring revenue and perpetual license maintenance streams

Coverage of manufacturers representing 65-70% of global market share in 2024

Extrapolation using bottom-up (license volume × ASP by segment/region for software; unit shipments × hardware pricing by sensor category) and top-down (enterprise software spend validation, geospatial industry revenue triangulation) approaches to derive segment-specific valuations for CAGD, computer graphics, digital media, and emerging healthcare applications
下载免费样本

请填写以下表格以获取本报告的免费样本

Global Diameter Signaling Market
案例研究
Information and Communications Technology
Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.