Transcatheter Aortic Valve Replacement Market (2026 - 2035)

Transcatheter Aortic Valve Replacement Market Research Report: Size, Share, Trend Analysis By Procedure Type (Self-Expanding Valve, Balloon-Expandable Valve, Transcatheter Aortic Valve), By Reference Type (Direct Access, Transfemoral, Transapical), By Material Type (Metal, Bioprosthetic, Hybrid), By End-user (Hospitals, Cardiac Centers, Ambulatory Surgical Centers), and By Regional (North America, Europe, South America, Asia Pacific, Middle East and Africa) - Growth Outlook & Industry Forecast 2025 To 2035
ID: MRFR/HC/20244-HCR 200 Pages Nidhi Mandole, Rahul Gotadki Last Updated: September 10, 2026
Transcatheter Aortic Valve Replacement Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)9.6%
2025 Market SizeUSD 7.02 Billion
2035 Market SizeUSD 17.55 Billion
Key Players
Edwards Lifesciences
Medtronic
Abbott Laboratories
Boston Scientific
Venus Medtech
Meril Life Sciences
Opportunities
  • Ambulatory and Same-Day Discharge Pathways
  • Valve-in-Valve and Lifetime Management
  • Emerging Market Localisation

Transcatheter Aortic Valve Replacement Market Summary

The Transcatheter Aortic Valve Replacement Market closed 2025 at USD 7.02 billion and enters the forecast window at USD 7.69 billion in 2026, expanding to USD 17.55 billion by 2035 at a 9.6% CAGR. Two catalysts anchor that trajectory. The first is the 2019–2021 wave of low-risk indication approvals from the U.S. Food and Drug Administration, which pulled a procedure once reserved for inoperable octogenarians into mainstream cardiology [1]. The second is reimbursement: the Centers for Medicare & Medicaid Services national coverage determination now funds roughly 78% of U.S. procedure volume through Medicare, converting clinical eligibility into paid throughput [2].

Surgical aortic valve replacement is losing ground. Open sternotomy with cardiopulmonary bypass — a five-to-seven day inpatient stay — is being displaced by conscious-sedation transfemoral implantation with median discharge within 48 hours. Edwards Lifesciences and Medtronic together committed more than USD 1.9 billion to structural heart research and development in 2024 alone, most of it directed at leaflet durability and lower-profile delivery systems [4]. This capital intensity is what separates the Transcatheter Aortic Valve Replacement Market from adjacent device categories.

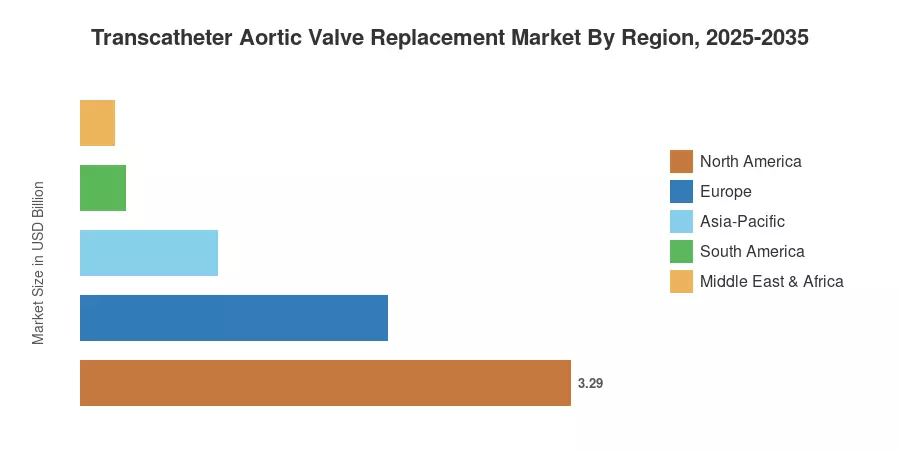
Regionally, North America holds 46.8% of 2025 revenue on the back of registry infrastructure and dense heart-team coverage. Asia-Pacific compounds fastest at 13.1% through 2035. Europe, at 29.4%, remains the volume anchor for the Transcatheter Aortic Valve Replacement Market outside the United States, supported by DRG-funded access in Germany and France. Expect the regional centre of gravity to shift measurably eastward before 2032.


Key Report Takeaways

• By Type of Device

  • Balloon-expandable valves hold 52.6% of 2025 global revenue, sustained by SAPIEN platform installed base and operator familiarity
  • Self-expanding valves post the strongest device-level growth in the Transcatheter Aortic Valve Replacement Market at an 11.2% CAGR, driven by supra-annular hemodynamics in small annuli

• By End User

  • Hospitals accounted for USD 5.50 billion in 2025 procedure-linked device revenue
  • Ambulatory surgical centres grow at 14.6% CAGR as same-day discharge protocols mature in the United States

• By Region

  • North America commands 46.8% share of the Transcatheter Aortic Valve Replacement Market in 2025
  • Asia-Pacific registers a 13.1% CAGR, the fastest of any region through 2035
  • Middle East & Africa contributed USD 0.23 billion in 2025, concentrated in Gulf tertiary centres


Market Size and Forecast (2021–2035)

Figures below blend procedure-volume triangulation from national cardiac registries, device average selling price reconciliation against manufacturer segment disclosures, and payer-side claims data. Historical years reflect audited revenue attribution; forecast years apply cohort-based eligibility modelling to the Transcatheter Aortic Valve Replacement Market.
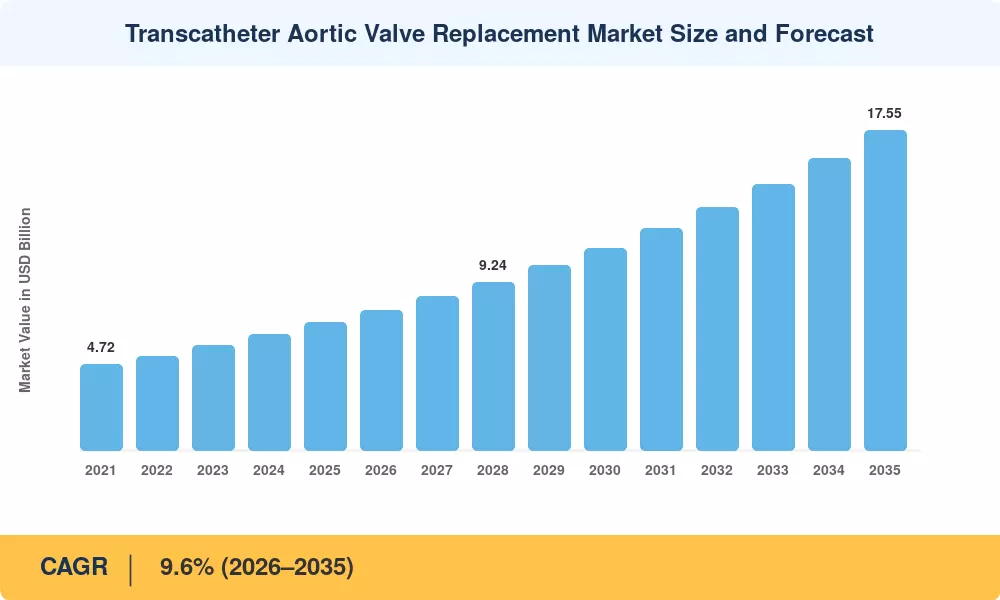
Transcatheter Aortic Valve Replacement Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Expansion into low-risk and asymptomatic severe aortic stenosis +2.1 pp Global Medium-term (2–4 yr)
Aging demographics and rising stenosis prevalence +1.8 pp Global Long-term (≥4 yr)
Reimbursement expansion across CMS, EU DRG, Japan Chuikyo +1.5 pp NA, Europe, Japan Short-term (≤2 yr)
Next-generation leaflet durability and low-profile delivery +1.2 pp Global Long-term (≥4 yr)
Heart-valve centre build-out across Asia-Pacific +1.1 pp Asia-Pacific Medium-term (2–4 yr)
Same-day discharge and ambulatory migration +0.9 pp North America Short-term (≤2 yr)
Domestic device manufacturing in China and India +0.8 pp Asia-Pacific Medium-term (2–4 yr)


Indication Expansion Into Low-Risk Patients

Clinical evidence altered the addressable population. The PARTNER 3 trial showed a composite of mortality, stroke, or rehospitalization at 8.5% for transcatheter patients versus 15.1% for surgical patients at one year, a 6.6-point absolute difference that regulators deemed definitive [6]. U.S. low-risk procedure volume more than tripled from 2020 to 2024 after FDA certification in August 2019. Each incremental risk-tier approval adds an estimated 40,000-55,000 patients yearly to the eligible cohort in the United States alone. The cohort mathematics continues to be the single largest structural input to the Transcatheter Aortic Valve Replacement Market projection.


Reimbursement Architecture

Payers determine whether throughput is eligibility. CMS reimburses transcatheter aortic valve treatments under MS-DRG 266/267 with an average base payment of nearly USD 47,800 and coverage based on facility volume and outcome standards [2]. Germany's G-DRG system reimburses around 24,000 procedures annually, the highest per capita rate in Europe [8]. In April 2024, Japan’s biennial Chuikyo repricing cycle reduced rates on devices by 4.2% and relaxed institutional certification conditions to increase the number of eligible hospitals. Most markets are constrained by access, not clinical appetite.


Device Engineering and Durability

Concerns about durability limited usage to those less than 75 years of age. Current fourth-generation platforms combine bovine pericardial leaflets with anti-calcification tissue therapy, and five-year registry follow-up indicates structural valve deterioration rates below 4% in modern devices [12]. They have driven transfemoral appropriateness above 92% of screened individuals, while concurrently reducing delivery sheath sizes to 14F and considerably reducing vascular complication rates.


Asia-Pacific Capacity Expansion

East of Europe infrastructure is the bottleneck. By the end of 2024, the number of hospitals certified for structural heart surgeries by China’s National Health Commission increased to over 340 from less than 90 in 2019 . In 2023, India’s Ayushman Bharat policy covered catheter-based valve surgeries under select state packages, but coverage caps are insufficient against imported equipment costs. At present certification rates, regional volume doubles approximately every four years.


Restraints Impact Analysis

Restraint weightings reflect drag on achievable growth rather than deductions applied against the headline CAGR. Scoring is directional and reviewed against payer policy and adverse-event registry data.

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
Long-term durability uncertainty in patients under 65 −1.4 pp Global Long-term (≥4 yr)
Permanent pacemaker implantation after implant −1.0 pp Global Medium-term (2–4 yr)
Device price erosion and hospital margin compression −0.9 pp Europe, Japan Short-term (≤2 yr)
Heart-team and cath-lab capacity shortages −0.8 pp APAC, MEA, South America Medium-term (2–4 yr)
High average selling price in lower-income markets −0.7 pp South America, MEA Long-term (≥4 yr)


Durability in Younger Patients

Management of patients in their 50s and 60s is still unsolved for the lifetime. A bioprosthetic valve implanted at age 62 will likely require reintervention, and valve-in-valve feasibility depends on coronary access preserved by the index implant. European guidelines still advocate surgery as first-line treatment below the age of 70 in the absence of prohibitive risk . About one-fifth of the physically eligible population is outside normal transcatheter channels until we have 15-year durability data.


Conduction System Complications

Pacemaker rates blunt the minimally invasive value proposition. Contemporary registry analysis places thirty-day permanent pacemaker implantation between 9% and 17% depending on valve platform and implant depth . Each pacemaker adds roughly USD 14,000 in downstream cost and introduces lifelong device management. Self-expanding platforms carry the higher end of that range, which shapes device selection in younger cohorts.

Pricing Pressure and Hospital Economics

Procurement is tightening. Average device selling prices in Western Europe declined an estimated 11% between 2021 and 2025 under tender consolidation, while hospital contribution margins on the procedure narrowed to low single digits in several Länder [8]. Volume growth is therefore outpacing revenue growth in mature markets — a divergence that pushes manufacturer strategy toward emerging geographies and service-attached models.


Transcatheter Aortic Valve Replacement Market Opportunities

Ambulatory and Same-Day Discharge Pathways

Site-of-care migration is the clearest near-term margin opportunity in the Transcatheter Aortic Valve Replacement Market. Streamlined protocols have cut median length of stay to under 24 hours at high-volume U.S. centres, and CMS added the procedure to the ambulatory-eligible review pathway in 2024 [10]. Manufacturers that bundle imaging planning, conscious-sedation workflow, and discharge protocol support capture a disproportionate share as this shift accelerates.

Valve-in-Valve and Lifetime Management

Reintervention is becoming its own demand pool. More than 320,000 transcatheter valves implanted before 2020 will approach the end of their expected service life during the forecast window, creating a redo cohort that did not previously exist [12]. Devices engineered for commissural alignment and preserved coronary access will command premium positioning.

Emerging Market Localisation

Price is the barrier in India, Brazil, and Southeast Asia. Locally manufactured platforms from Meril Life Sciences and Venus Medtech list at 35–50% below imported equivalents, and India's Production Linked Incentive scheme for medical devices allocated INR 34.2 billion toward domestic capacity through 2028 . Regional white space here is larger than in any mature market.

Registry Data and Outcome-Linked Contracting

Data is becoming a commercial asset. The STS/ACC TVT Registry now holds longitudinal records on over 500,000 procedures, and payers in Germany and the Netherlands have piloted outcome-linked device contracts using comparable national datasets [16]. Manufacturers holding the richest post-market evidence can defend price in tendered environments — a new business model layered onto the Transcatheter Aortic Valve Replacement Market rather than replacing device sales.

Artificial Intelligence in Procedural Planning

Automated CT annulus sizing and predictive conduction-risk modelling reduce planning time from hours to minutes. Early deployments report sizing concordance above 94% against expert core-lab reads, which shortens the learning curve for newly certified centres [17].


Transcatheter Aortic Valve Replacement Market Future Outlook

Algorithmic Procedural Planning

Software will absorb much of the pre-procedural workload currently handled by imaging specialists. Automated annular measurement, calcium distribution scoring, and coronary obstruction risk prediction are converging into single planning suites, and vendor-neutral platforms are already integrated at more than 200 European centres [17]. This lowers the barrier for medium-volume hospitals to enter the Transcatheter Aortic Valve Replacement Market, expanding the site count rather than deepening existing accounts.

Lifetime Management as Product Strategy

Sequencing beats single-implant thinking. Manufacturers are redesigning frames around what happens ten years later — commissural alignment, coronary re-access, and explantability now feature in design dossiers alongside hemodynamic performance. Devices that fail the lifetime-management test will lose younger patients to surgery regardless of acute outcomes.

Price Tiering and Portfolio Bifurcation

Two product tiers are emerging. Premium platforms retain Western hospital share on evidence depth, while cost-engineered valves priced 35–50% lower target volume geographies where the alternative is no treatment at all . Global players will either build tiered portfolios or cede Asia-Pacific and South American volume to regional manufacturers.

Evidence Infrastructure and Payer Accountability

Longitudinal outcome reporting moves from voluntary to mandatory across more jurisdictions. The OECD estimates that health systems in member countries face aging-driven cardiovascular cost growth of 2.7% annually through 2035, and payers are responding by tying device funding to measurable outcomes [19]. Sustained expansion of the Transcatheter Aortic Valve Replacement Market therefore depends as much on registry participation and real-world evidence generation as on the next iteration of valve hardware.


Regional Market Share Analysis

Region Metric (2025) Primary Investment Themes
North America 46.8% share ASC migration, low-risk expansion, registry-linked contracting
Europe 29.4% share DRG optimisation, tender consolidation, valve-in-valve pathways
Asia-Pacific 13.1% CAGR (2026–2035) Centre certification, domestic manufacturing, price-tier products
South America USD 0.30 Billion Private-payer growth, Brazilian regulatory harmonisation
Middle East & Africa USD 0.23 Billion Gulf tertiary infrastructure, medical tourism corridors
Total USD 7.02 Billion —

Regional distribution within the Transcatheter Aortic Valve Replacement Market tracks reimbursement maturity far more closely than it tracks disease prevalence.


North America

Country Market Size 2025 (USD B) Key Driver
US 2.91 CMS national coverage determination and dense heart-team network
Canada 0.26 Provincial funding expansion in Ontario and Quebec
Mexico 0.12 Private hospital investment in Mexico City and Monterrey


Volume leadership in the Transcatheter Aortic Valve Replacement Market rests on institutional density: more than 780 certified U.S. sites perform the procedure, and the mandatory TVT Registry submission requirement has produced the deepest outcome dataset in structural cardiology [16]. Canada moves slower, constrained by provincial budget cycles that cap annual case allocation despite waiting lists exceeding six months in several regions.

Europe

Country Share of Region (2025) Key Driver
Germany 23.4% Highest per-capita procedure rate under G-DRG funding
UK 15.1% NHS structural heart service expansion post-backlog
France 14.6% Forfait innovation pathway and centre accreditation
Italy 12.8% Regional health authority tender programmes
Spain 9.7% Public–private capacity partnerships
Nordic Countries 8.4% Early adoption and high procedural volumes per centre
Russia 4.2% Import substitution and domestic device programmes
Rest of Europe 11.8% Central European reimbursement catch-up


Germany anchors the region with roughly 24,000 annual procedures, exceeding the combined volume of the next two largest European markets [8]. Tender consolidation has compressed pricing across the bloc, yet the EU Medical Device Regulation has simultaneously raised the evidentiary bar for new entrants — a dynamic that protects incumbent share while slowing overall device diversity.

Asia-Pacific

Country CAGR (2026–2035) Key Driver
China 15.4% NHC centre certification and domestic valve approvals
India 16.8% Ayushman Bharat package inclusion and local manufacturing
Japan 10.2% Mature reimbursement with the region's oldest population
South Korea 12.6% National Health Insurance Service coverage broadening
ASEAN 13.9% Thailand and Singapore tertiary centre build-out
Rest of Asia-Pacific 11.3% Australian private-payer volume growth


China represents the largest single growth pool within the Transcatheter Aortic Valve Replacement Market. Bicuspid aortic valve morphology occurs in an estimated 40% of Chinese patients undergoing the procedure versus roughly 10% in Western cohorts, which has pushed domestic manufacturers toward purpose-designed anchoring geometries . Japan grows more slowly in percentage terms but from a substantially larger base, with over 29% of its population above 65.

South America

Country Market Size 2025 (USD B) Key Driver
Brazil 0.175 ANVISA approvals and supplementary health plan coverage
Argentina 0.058 Private insurance procedure funding
Rest of South America 0.067 Chilean and Colombian tertiary centre growth


Brazil dominates regional demand, though access splits sharply along payer lines — the supplementary private system funds the overwhelming majority of procedures while SUS coverage remains limited to selected reference hospitals [14]. Braile Biomédica's domestically produced platform has begun narrowing the price gap that historically kept public-sector volume near zero.

Middle East & Africa

Country Share of Region (2025) Key Driver
Saudi Arabia 28.6% Vision 2030 Health Sector Transformation Programme
UAE 21.3% Medical tourism and private tertiary capacity
South Africa 18.4% Private hospital group cardiac programmes
Egypt 12.9% Universal Health Insurance rollout in pilot governorates
Rest of MEA 18.8% Qatar and Kuwait specialist centre investment


Gulf states drive regional economics. Saudi Arabia's health transformation programme earmarked more than USD 26 billion for hospital modernisation, including catheterisation laboratory expansion at fourteen tertiary sites [18]. Sub-Saharan penetration stays negligible outside South Africa, constrained by imaging capacity and the absence of trained heart teams rather than by device availability.


Transcatheter Aortic Valve Replacement Market By Region, 2025-2035

Transcatheter Aortic Valve Replacement Market Segmentation

Segmentation within the Transcatheter Aortic Valve Replacement Market follows device architecture, access route, frame material, and care setting.

By Type of Device

Segment Metric (2025) Primary Demand Driver
Balloon-Expandable Valves 52.6% share Installed base, predictable deployment, low pacemaker rates
Self-Expanding Valves 11.2% CAGR (2026–2035) Supra-annular hemodynamics in small annuli
Mechanically Expandable and Other Valves USD 0.43 Billion Repositionability in complex anatomy


Balloon-expandable platforms retain majority share of the Transcatheter Aortic Valve Replacement Market largely because operator familiarity compounds — centres that trained on SAPIEN generations rarely switch wholesale. Self-expanding designs are gaining faster, however, as evidence accumulates on superior effective orifice area in patients with annular diameters under 23 mm, a group that skews female and represents roughly 30% of screened candidates.

By Procedure

Segment Metric (2025) Primary Demand Driver
Transfemoral 84.2% share Conscious sedation, sub-24-hour discharge feasibility
Transapical 9.6% share Fallback for prohibitive iliofemoral disease
Transaortic 6.2% share Alternative access in porcelain aorta cases


Transfemoral access is now the default, and sheath miniaturisation to 14F has pushed its suitability rate above 92% of screened patients. Alternative access routes are shrinking in relative terms but retain clinical necessity — transapical procedures still carry roughly triple the thirty-day mortality of transfemoral cases, which explains why centres exhaust femoral options first.

By Material

Segment Metric (2025) Primary Demand Driver
Nitinol 47.8% share Self-expanding frame shape memory and conformability
Cobalt Chromium USD 2.70 Billion Radial strength in balloon-expandable frames
Stainless Steel and Other Alloys 6.4% CAGR (2026–2035) Legacy platforms and specialty frame designs


Material choice in the Transcatheter Aortic Valve Replacement Market maps almost directly onto expansion mechanism, so nitinol and cobalt chromium shares move in step with the device-type split. Cobalt chromium's thin-strut radial strength permits frame heights low enough to preserve coronary access, which matters increasingly as lifetime management becomes a purchasing criterion.

By End User

Segment Metric (2025) Primary Demand Driver
Hospitals USD 5.50 Billion Heart-team requirements and on-site surgical backup
Ambulatory Surgical Centres 14.6% CAGR (2026–2035) Same-day discharge protocols and cost differential
Cardiac Specialty Centres and Others 7.7% share Focused-factory volume efficiency


Hospitals will retain the overwhelming majority of volume throughout the forecast because coverage rules mandate on-site cardiac surgery capability in most jurisdictions. Ambulatory settings nonetheless grow fastest from a small base, with U.S. cost differentials of roughly 28% per case creating strong payer incentive to relax site-of-service restrictions once safety data matures [10].


Competitive Benchmarking

Concentration is high but softening. The top two suppliers control an estimated 68–72% of global revenue, top-five share sits near 84%, and the implied Herfindahl-Hirschman Index falls in the 2,400–2,700 band — moderately concentrated by antitrust convention. Regional entrants in China and India are the primary source of erosion in the Transcatheter Aortic Valve Replacement Market, capturing domestic share faster than incumbents can price-match.

Company Est. Revenue Share Range Key Offerings for Transcatheter Aortic Valve Replacement Market Strategic Positioning
Edwards Lifesciences ~38–43% SAPIEN 3 / SAPIEN 3 Ultra RESILIA balloon-expandable platforms Category leader; deepest low-risk evidence base
Medtronic ~26–31% Evolut PRO+ / Evolut FX self-expanding supra-annular valves Small-annulus hemodynamic leadership
Abbott Laboratories ~6–9% Navitor and Portico NG self-expanding systems with active sealing Structural heart portfolio breadth
Boston Scientific ~4–7% ACURATE neo2 self-expanding valve Low-pacemaker-rate positioning in Europe
Venus Medtech ~2–4% VenusA-Plus, VenusA-Pro retrievable systems China domestic volume leader
Meril Life Sciences ~2–4% MyVal THV series with tri-tier sizing India-anchored value pricing, EU expansion
JenaValve Technology ~1–2% Trilogy heart valve system for aortic regurgitation Niche leadership in native regurgitation
MicroPort Scientific ~1–2% VitaFlow Liberty motorised delivery valve Integrated China cardiovascular portfolio
Peijia Medical ~1–2% TaurusOne and TaurusElite retrievable valves Second-tier China challenger
Braile Biomédica <1% Inovare transcatheter valve Brazil domestic manufacturing base
Anteris Technologies <1% DurAVR biomimetic single-piece valve Early-stage durability differentiation


Recent News & Developments

Developments below shaped competitive positioning across the Transcatheter Aortic Valve Replacement Market between 2023 and 2025.


  • Medtronic (April 2024): Launched Evolut FX+ with enlarged frame windows designed to improve coronary access after implant, directly addressing lifetime-management objections [4]
  • Abbott (June 2024): Secured expanded indication for Navitor in intermediate-risk patients across selected European markets, broadening its addressable cohort [20]


  • CMS (July 2024): Opened review of ambulatory site-of-service eligibility for selected structural heart procedures, a precondition for outpatient migration [10]
  • Venus Medtech (March 2025): Obtained NMPA approval for a next-generation retrievable valve engineered for bicuspid anatomy, addressing a morphology common in Chinese patients
  • JenaValve (October 2024): Received FDA Breakthrough Device designation progress for Trilogy in symptomatic aortic regurgitation, an indication with no approved transcatheter alternative [22]


Transcatheter Aortic Valve Replacement Market Report Scope

Parameter Detail
Market Scope Global Transcatheter Aortic Valve Replacement Market by device type, procedure, material, end user, and region
Study Period 2021–2035 (Historical 2021–2024; Base Year 2025; Forecast 2026–2035)
CAGR 9.6% (2026–2035)
Market Size Checkpoints USD 7.02 Billion (2025); USD 7.69 Billion (2026); USD 11.10 Billion (2030); USD 17.55 Billion (2035)
Fastest Growing Segments Self-expanding valves (device); ambulatory surgical centres (end user); Asia-Pacific (region)
Companies Profiled Edwards Lifesciences, Medtronic, Abbott, Boston Scientific, Venus Medtech, Meril Life Sciences, JenaValve, MicroPort, Peijia Medical, Braile Biomédica, Anteris Technologies
Valuation Currency USD, manufacturer revenue basis at device level

FAQs

What procurement criteria should hospitals weigh when standardising on a single supplier in the Transcatheter Aortic Valve Replacement Market?
Prioritise sizing-matrix coverage for your patient anatomy mix over headline unit price. Single-supplier contracts that lack small-annulus or bicuspid options force off-contract purchases that erode the discount entirely [12].
How do capital equipment requirements affect entry for a new centre?
A hybrid operating room with fixed fluoroscopy runs USD 2.5–4 million before staffing. Centres performing under 50 cases annually rarely reach breakeven, which is why regulators attach volume thresholds to certification [2].
Which unmet clinical indication represents the largest untapped pool in the Transcatheter Aortic Valve Replacement Market?
While native aortic regurgitation historically lacked dedicated options, the FDA granted Premarket Approval to JenaValve's Trilogy System in March 2026, making it the first transcatheter device indicated for symptomatic severe AR in the U.S.
How should investors read the widening gap between procedure volume growth and revenue growth?
Volume is outpacing revenue in Europe and Japan because tender pricing compresses faster than cases expand. Judge manufacturers on emerging-market share gains, not on unit shipments in mature geographies [8].
What integration challenges slow adoption of new valve platforms in the Transcatheter Aortic Valve Replacement Market?
Imaging workflow, not the device. Each platform uses proprietary sizing software and deployment landmarks, so switching costs sit in retraining imaging teams and revalidating CT protocols [17].
Does regulatory divergence between the FDA and EU Medical Device Regulation favour either region for launches?
Europe has lost its historical first-launch advantage. MDR clinical evidence requirements now approach FDA thresholds, and several manufacturers now file in the United States first [23].
How do bicuspid aortic valve patients change device selection?
Elliptical annuli and asymmetric calcification make standard sizing unreliable, raising paravalvular leak risk. Platforms with repositionability or purpose-built anchoring geometry are preferred, particularly across East Asian populations .      
Author
Author Author Profile Nidhi Mandole LinkedIn Senior Research Analyst
She is an extremely curious individual currently working in Healthcare and Medical Devices Domain. Nidhi is comfortably versed in data centric research backed by healthcare educational background. She leverages extensive data mining and analytics tools such as Primary and Secondary Research, Statistical Analysis, Machine Learning, Data Modelling. Her key role also involves Technical Sales Support, Client Interaction and Project management within the Healthcare team. Lastly, she showcases extensive affinity towards learning new skills and remain fascinated in implementing them.
Co-Author Co-Author Profile Rahul Gotadki LinkedIn Research Manager
He holds an experience of about 9+ years in Market Research and Business Consulting, working under the spectrum of Life Sciences and Healthcare domains. Rahul conceptualizes and implements a scalable business strategy and provides strategic leadership to the clients. His expertise lies in market estimation, competitive intelligence, pipeline analysis, customer assessment, etc.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of regulatory databases, peer-reviewed cardiovascular journals, clinical publications, and authoritative health organizations. Key sources included the US Food & Drug Administration (FDA) Center for Devices and Radiological Health (CDRH), European Medicines Agency (EMA) Medical Device Coordination Group, Centers for Medicare & Medicaid Services (CMS), Society for Cardiovascular Angiography and Interventions (SCAI), American College of Cardiology (ACC), American Heart Association (AHA), European Society of Cardiology (ESC), National Institutes of Health (NIH) National Heart, Lung, and Blood Institute (NHLBI), National Center for Biotechnology Information (NCBI/PubMed), Centers for Disease Control and Prevention (CDC) National Center for Health Statistics, World Health Organization (WHO) Cardiovascular Disease Database, Organisation for Economic Co-operation and Development (OECD) Health Statistics, Eurostat Healthcare Database, National Cardiovascular Data Registry (NCDR) STS/ACC TVT Registry, and national health ministry reports from key markets. These sources were used to collect procedure statistics, regulatory approval data, clinical safety studies, demographic trends, and market landscape analysis for balloon-expandable valves, self-expanding valves, transfemoral approaches, transapical approaches, and other TAVR technologies.


Primary Research

Qualitative and quantitative insights were obtained by interviewing supply-side and demand-side stakeholders during the primary research process. The supply-side sources consisted of CEOs, VPs of Product Development, regulatory affairs chiefs, and commercial directors from TAVR device manufacturers and OEMs. Interventional cardiologists, cardiac surgeons, structural heart program directors, and procurement leads from hospitals, cardiac centers, and ambulatory surgical centers constituted demand-side sources. Market segmentation was validated, product pipeline timelines were confirmed, and insights regarding reimbursement dynamics, pricing strategies, and clinical adoption patterns were obtained through primary research.

Primary Respondent Breakdown:

By Designation: C-level Primaries (32%), Director Level (31%), Others (37%)

By Region: North America (38%), Europe (30%), Asia-Pacific (25%), Rest of World (7%)


Market Size Estimation

Global market valuation was derived through revenue mapping and procedure volume analysis. The methodology included:

Identification of 35+ key manufacturers across North America, Europe, Asia-Pacific, and Latin America

Product mapping across balloon-expandable valves, self-expanding valves, transfemoral delivery systems, transapical delivery systems, and other TAVR categories

Analysis of reported and modeled annual revenues specific to TAVR device portfolios

Coverage of manufacturers representing 75-80% of global market share in 2024

Extrapolation using bottom-up (procedure volume × ASP by country) and top-down (manufacturer revenue validation) approaches to derive segment-specific valuations

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.


















