Thermoplastic Pipe Market Summary
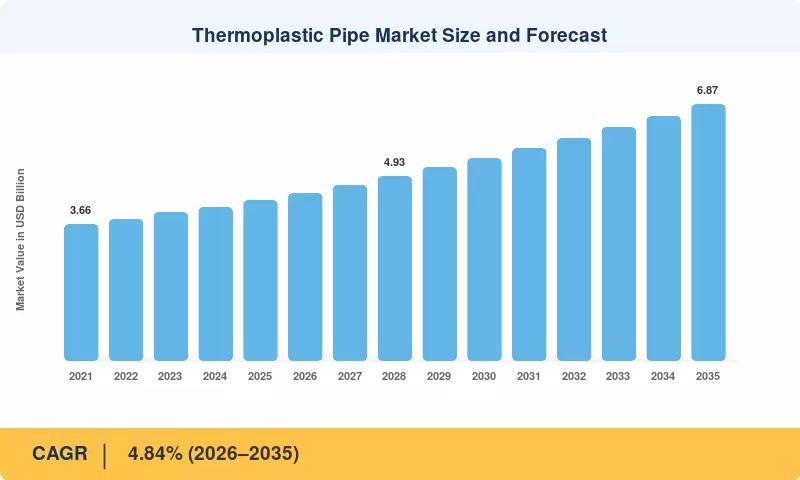
The Thermoplastic Pipe Market was valued at USD 4.29 Billion in 2025, opens the forecast window at USD 4.48 Billion in 2026, and is projected to reach USD 6.87 Billion by 2035, expanding at a 4.84% CAGR between 2026 and 2035. Two catalysts anchor that trajectory. The U.S. Department of Transportation's PHMSA methane-leak rule penalises fugitive emissions from ageing gathering lines, and the European Union's Regulation 2024/1787 imposes measurement, reporting and verification duties on energy-sector operators from 2025 onward [1][2]. Both reward joint integrity, which is precisely where spoolable polymer systems outperform welded carbon steel.
Operators are retiring corrosion-prone steel gathering lines, water-injection headers and chemical transfer loops in favour of reinforced and composite polymer systems that arrive on reels rather than in 12-metre joints. Deepwater teams report offshore installation windows compressing by up to 60% when composite flowlines replace rigid steel, a decisive economic argument when day rates for a construction vessel exceed USD 250,000 [3]. Global upstream capital spending of roughly USD 570 Billion in 2025 keeps that substitution funded [4].
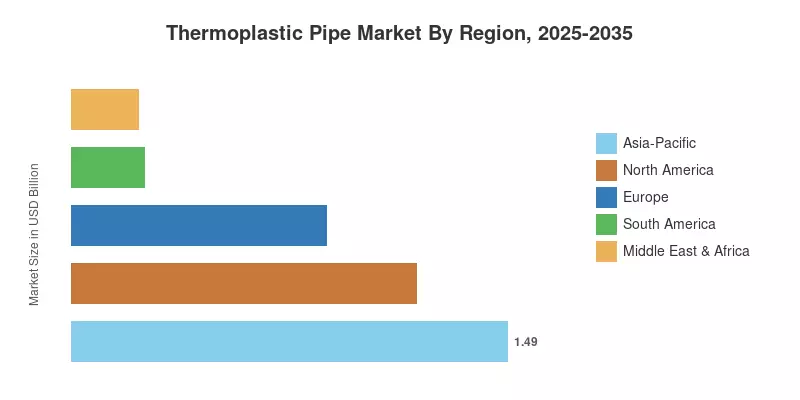
Asia-Pacific dominates with 34.8% of 2025 revenue and simultaneously grows fastest at 5.92%, propelled by municipal water and wastewater programmes across China, India and ASEAN. North America follows as the second-largest region, where shale gathering networks and produced-water disposal lines account for the bulk of demand. Through 2035, the Thermoplastic Pipe Market will increasingly be shaped by hydrogen and CO₂ service qualification rather than by conventional hydrocarbons alone.
Key Report Takeaways
• By Technology (Pipe Type)
- Reinforced thermoplastic pipe held 53.4% of Thermoplastic Pipe Market revenue in 2025, underpinned by onshore gathering and water-injection duty.
- Thermoplastic composite pipe is the fastest-expanding construction at a 6.58% CAGR through 2035, driven by subsea jumper and riser qualification.
- Flexible composite pipe retains a defensible niche in low-pressure produced-water and chemical dosing lines.
• By Sector
- Oil and gas contributed 57.0% of revenue in 2025, spanning gathering, injection and downhole tubing applications.
- Chemical and process industries are advancing at a 6.85% CAGR as fluoropolymer linings displace lined steel.
- Water and wastewater utilities represented roughly USD 0.60 Billion of 2025 spending.
• By Region
- Asia-Pacific led the Thermoplastic Pipe Market with a 34.8% share in 2025
- North America generated USD 1.18 Billion, concentrated in the Permian and Montney basins
- Middle East & Africa is compounding at a 5.31% CAGR on the back of Gulf water-injection expansions
Market Size and Forecast (2021–2035)
Estimates combine resin-consumption tracking, spool-metre shipment data from converters, disclosed contract awards, and bottom-up modelling of onshore and offshore project pipelines. Historical values were reconciled against customs data for polyethylene and polyamide pipe grades, then triangulated with vendor revenue disclosures. Forecast values for the Thermoplastic Pipe Market apply basin-level capital expenditure forecasts weighted by observed polymer penetration rates.



 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA



