Sports Medicine Market (2026 - 2035)

Sports Medicine Market Research Report By Application (Injury Prevention, Athletic Performance Enhancement, Rehabilitation, Pain Management, Health Monitoring), By Product Type (Braces Supports, Therapeutic Devices, Surgery Equipment, Pain Management, Rehabilitation Equipment), By End Use (Hospitals, Sports Clinics, Home Healthcare, Fitness Centers, Rehabilitation Centers), By Distribution Channel (Direct Sales, Online Sales, Retail Sales, Wholesale, Distributors) and By Regional (North America, Europe, South America, Asia Pacific, Middle East and Africa) - Growth & Industry Forecast Till 2035
ID: MRFR/HC/2407-CR 200 Pages Satyendra Maurya, Rahul Gotadki Last Updated: September 11, 2026
Sports Medicine Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)7.29%
2025 Market SizeUSD 7.72 Billion
2035 Market SizeUSD 15.60 Billion
Key Players
Arthrex, Inc.
Smith & Nephew plc
Stryker Corporation
DePuy Synthes
CONMED Corporation
Zimmer Biomet Holdings
Opportunities
  • Outpatient-Native Product Architecture
  • Emerging-Market Access Models
  • Recovery Data as a Recurring-Revenue Product

Sports Medicine Market Summary

The Sports Medicine Market closed 2025 at USD 7.72 billion and enters its forecast window at USD 8.28 billion in 2026, climbing to USD 15.60 billion by 2035 at a 7.29% CAGR. Growth is not accidental. Two catalysts anchor it: the U.S. Centers for Medicare & Medicaid Services expanded its Ambulatory Surgical Center Covered Procedures List to include total knee and partial hip arthroplasty, pushing high-margin orthopedic volume out of hospitals [1]; and the European Union's Medical Device Regulation recertification cycle, which forced manufacturers to reinvest an estimated EUR 1.9 billion in clinical evidence generation between 2021 and 2025 [2].

Surgical technique is where the real transformation sits. Open reconstruction with metallic hardware is giving way to arthroscopic and all-suture fixation, bioabsorbable anchors, and biologic augmentation using platelet-rich plasma and collagen scaffolds. Arthrex alone has committed more than USD 500 million to manufacturing and medical education infrastructure since 2022 [3], while the U.S. Food and Drug Administration's 2023 guidance on regenerative products tightened the pathway for cell-based adjuncts [4].

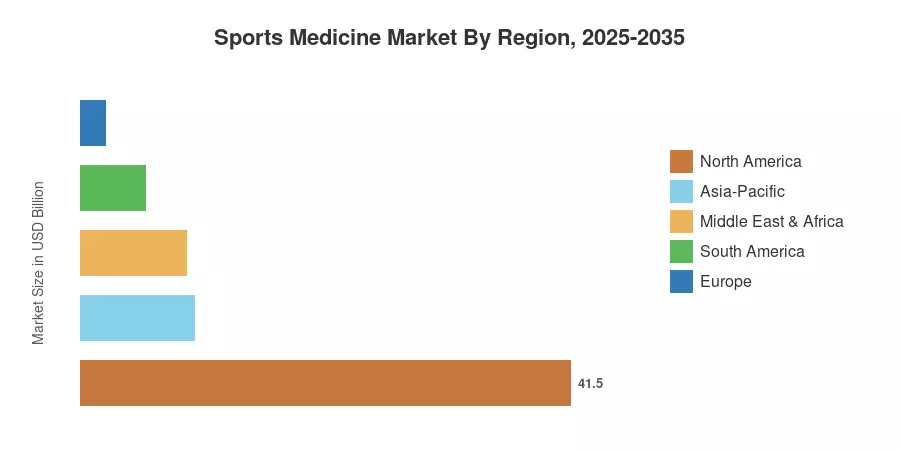
Regionally, North America holds 41.5% of 2025 revenue, supported by the deepest ASC network anywhere. Asia-Pacific compounds fastest at 9.62%, and Europe sits second at 27.0% on the back of universal-coverage reimbursement for ligament reconstruction. The Sports Medicine Market of 2035 will be defined less by implant metallurgy than by who owns the recovery data.


Key Report Takeaways

• By Product Type

  • Orthopedic implants — including anchors, plates, and screws — command roughly 38.4% of 2025 Sports Medicine Market revenue
  • Arthroscopy devices post the fastest product-level growth at an 8.71% CAGR through 2035
  • Braces and support products generated close to USD 1.34 billion in 2025

• By Application

  • Knee injuries represent the single largest application at 32.7% share
  • Shoulder procedures are expanding at 8.15% annually as rotator cuff repair volumes rise
  • Spine-related sports indications contributed approximately USD 0.51 billion in 2025

• By End User

  • Hospitals still account for 44.9% of Sports Medicine Market demand, though the share erodes yearly
  • Ambulatory surgical centers grow fastest at 9.84% CAGR
  • Home care settings delivered roughly USD 0.93 billion in 2025 revenue

• By Region

  • North America leads with 41.5% of global revenue
  • Asia-Pacific advances at 9.62% CAGR, the fastest of any region
  • Europe generated approximately USD 2.08 billion in 2025


Market Size and Forecast (2021–2035)

Estimates blend bottom-up procedure counts from national arthroplasty and arthroscopy registries with top-down triangulation against filed segment revenues from listed orthopedic manufacturers. Historical values are reconciled against hospital discharge datasets; forecast years apply payer-mix migration and elective-procedure recovery curves.
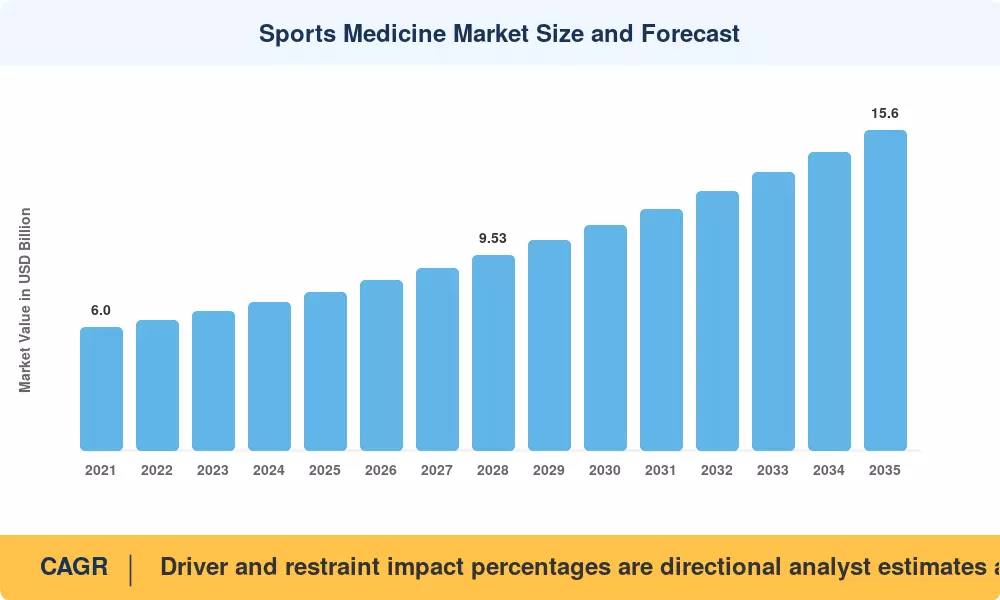
Sports Medicine Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
ASC migration of orthopedic procedures +1.6% North America, Western Europe Short-term (≤2 yr)
Rising youth and amateur sports participation +1.4% Global Long-term (≥4 yr)
Minimally invasive arthroscopic technique adoption +1.3% Global Medium-term (2–4 yr)
Ageing but physically active populations +1.1% Europe, Japan, North America Long-term (≥4 yr)
Biologics and regenerative adjunct uptake +0.9% North America, Asia-Pacific Medium-term (2–4 yr)
Public investment in national sports infrastructure +0.8% Asia-Pacific, Middle East Medium-term (2–4 yr)
Wearable-enabled remote recovery monitoring +0.6% North America, Europe Long-term (≥4 yr)


Ambulatory Migration Rewrites the Procedure Economics

Technology by itself was unable to accomplish what reimbursement policy did. Following the addition of total knee arthroplasty to the ASC Covered Procedures List, U.S. outpatient orthopedic volumes increased at a rate of about 11% per year until 2024. The transition was financially irreversible for surgeon-owners due to CMS payment differences of 35–45% compared to hospital outpatient departments [1]. In response, device manufacturers offered single-tray, disposable, hefty kits intended for environments lacking central sterile processing.


Participation Growth Feeds the Injury Funnel

In 2024, 39.8% of children aged 6–17 participated in youth sports in the United States, a five-year high, according to the Aspen Institute's Project Play tracking [7]. Exposure leads to injury. Approximately 250,000 ACL injuries occur each year in the United States alone [8], and anterior cruciate ligament replacement in patients under 20 has increased more quickly than in any other age group, maintaining structural demand throughout the sports medicine market.


Technique Shift Toward All-Suture and Bioabsorbable Fixation

Surgeons are trading metal for polymer. All-suture anchors now account for an estimated 30% of shoulder fixation volume in high-income markets, driven by revision-friendliness and imaging compatibility [3]. Bioabsorbable interference screws carry price premiums of 20–30% over titanium equivalents, lifting average selling prices even where procedure counts plateau.

Sovereign Sports Investment in Emerging Economies

Saudi Arabia's Quality of Life Program has channelled more than USD 3 billion into sports facilities and clubs since 2019, with a stated target of 40% weekly physical activity participation [10]. India's Khelo India scheme funds sports science centres attached to state universities. Both create clinical infrastructure where almost none existed a decade ago.


Restraints Impact Analysis

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
Hospital and payer price compression −1.5% North America, Europe Short-term (≤2 yr)
EU MDR recertification cost and portfolio pruning −1.2% Europe Medium-term (2–4 yr)
Orthopedic surgeon and physiotherapist shortages −0.9% Global Long-term (≥4 yr)
Weak evidence base for biologic adjuncts −0.7% Global Medium-term (2–4 yr)
Out-of-pocket burden in low-coverage markets −0.6% Asia-Pacific, Africa Long-term (≥4 yr)


Price Compression From Consolidated Purchasing

Implant pricing is now negotiated on multi-year, category-wide terms by hospital systems and group purchasing organizations. In major U.S. IDNs, reported average selling price erosion for sports medicine implants ranged from 2% to 4% per year in 2024 [12]. Instead of using list price to protect margin, vendors use bundled service contracts, which gives enterprises with deeper instrumentation and education a competitive edge.


Regulatory Cost Pushes Small Portfolios Out

At mid-cap companies, MDR recertification used a disproportionate amount of resources. Instead of funding clinical evidence cleanup, 26% of respondents to a MedTech Europe survey withdrew at least one outdated device line [2]. European choice was reduced, with niche brace and orthotic providers suffering the most.


Clinical Workforce Constraints Cap Throughput

The World Health Organization projects a global shortfall of roughly 10 million health workers by 2030, with rehabilitation professions among the least resourced [13]. Operating room capacity, not implant supply, is the binding constraint in several European systems, where median waits for elective ligament reconstruction exceed 20 weeks.


Sports Medicine Market Opportunities

Outpatient-Native Product Architecture

Instead of retrofitting hospital kits, device manufacturers who specifically design for the ASC—pre-sterilized single-use instrument sets, fewer trays, and easier reprocessing—capture the fastest-growing end-user channel. Tray reduction reduces the rotation time each case by 12 to 18 minutes, according to facilities [1].


Emerging-Market Access Models

India, ASEAN, and Brazil, whose per-capita orthopedic operation rates are still less than one-fifth of OECD levels, can be accessed through tiered pricing combined with local production [14]. The entrance cost of localization is reduced by 5% incentives on incremental domestic sales under India's Production Linked Incentive plan for medical equipment [15].


Recovery Data as a Recurring-Revenue Product

Sensor-instrumented braces and post-operative rehabilitation apps generate longitudinal outcome data that payers increasingly demand for value-based contracting. Subscription rehabilitation platforms already carry gross margins above 70%, well ahead of implant hardware, and convert one-time surgical revenue into multi-year relationships [11].

Biologic Augmentation With Defensible Evidence

Firms willing to fund randomised trials on collagen-based ACL repair scaffolds and PRP protocols can convert a contested category into a reimbursed one. The FDA's regenerative medicine framework offers a clearer route for products with genuine clinical data behind them [4].

Women's Sport as an Underserved Clinical Segment

Female athletes sustain ACL injuries at two to eight times the rate of male counterparts in comparable sports [8]. Sex-specific implant geometry, bracing, and prevention programming remain commercially underdeveloped relative to the demand signal.


Sports Medicine Market Future Outlook

Computer-Assisted and Robotic Arthroscopy

Robotics has already reshaped arthroplasty; arthroscopy is next. Navigation systems for tunnel placement in ligament reconstruction are entering pivotal trials, and installed robotic orthopedic platforms are projected to more than double by 2030 [26]. Capital placement, not disposables, will decide which vendors win these accounts.

Outcome-Linked Commercial Models

Payers want risk sharing. Bundled payment pilots covering 90-day episodes for knee procedures already cover a meaningful share of U.S. commercial lives, and warranty-style implant contracts tied to revision rates are spreading in Northern Europe [12] [20]. Vendors without outcome data will find themselves excluded from these tenders.

Prevention Moves Upstream

Screening protocols using force-plate and motion-capture assessment are migrating from professional clubs to school and collegiate programmes. Neuromuscular training programmes have demonstrated ACL injury reductions of 50% or more in controlled studies [8], creating a paradoxical dynamic: better prevention suppresses surgical volume while expanding diagnostic and bracing revenue.

Supply Chain Localisation and Sustainability

Single-use instrumentation cut sterilisation burden but raised waste volumes, and European procurement is beginning to score carbon intensity in tenders [2]. Localised production in India, China, and Mexico simultaneously addresses tariff exposure and shortens lead times, reshaping where the Sports Medicine Market's manufacturing base sits by 2035.


Regional Market Share Analysis

Region Metric (2025) Primary Investment Themes
North America 41.5% share ASC buildout, biologics, robotics-assisted arthroscopy
Europe USD 2.08 Billion MDR compliance, day-case pathways, public rehab capacity
Asia-Pacific 9.62% CAGR Local manufacturing, sports science centres, private hospitals
South America 5.5% share Private insurance expansion, football medicine
Middle East & Africa 8.94% CAGR Sovereign sports programmes, medical tourism hubs
Total 100.0% / USD 7.72 Billion

Regional concentration in the Sports Medicine Market tracks surgical infrastructure and insurance depth more than population.


North America

Country Metric Key Driver
US 86.2% of region ASC payment reform and dense surgeon-owner network [1]
Canada USD 0.31 Billion Provincial wait-time reduction funding [16]
Mexico 8.11% CAGR Private hospital expansion and cross-border care [17]


The United States remains the pricing anchor for the global Sports Medicine Market. Roughly 6,300 Medicare-certified ASCs now operate nationwide, and orthopedics has become their fastest-growing specialty line [1]. Canada's federal-provincial funding agreements earmarked CAD 1.2 billion toward surgical backlog reduction, disproportionately benefiting knee and shoulder procedures [16].

Europe

Country Metric Key Driver
Germany 23.4% of region DRG day-case catalogue expansion [18]
UK USD 0.36 Billion NHS elective recovery targets [19]
France 15.1% of region Ambulatory surgery national objective [18]
Italy 6.02% CAGR Regional procurement modernisation [18]
Spain USD 0.16 Billion Private insurance penetration growth [18]
Nordic Countries 7.9% of region Registry-driven outcome procurement [20]
Russia 5.11% CAGR Domestic substitution policy [21]
Rest of Europe 8.2% of region CEE capacity investment [18]


Germany anchors European demand through the highest orthopedic procedure density on the continent, while its DRG catalogue steadily reclassifies arthroscopic work as day-case [18]. The UK's elective recovery programme committed GBP 8 billion to clearing backlogs, and Scandinavian arthroplasty and ligament registries increasingly drive tender decisions on revision-rate evidence rather than price [19] [20].

Asia-Pacific

Country Metric Key Driver
China 34.8% of region Volume-based procurement plus private sports clinics [22]
India 11.94% CAGR Khelo India and PLI-backed localisation [15]
Japan USD 0.32 Billion Ageing active population and reimbursement stability [9]
South Korea 9.6% of region High recreational sport participation [23]
ASEAN 10.82% CAGR Medical tourism and private hospital chains [23]
Rest of Asia-Pacific 7.4% of region Australian and NZ registry-led adoption [23]


Asia-Pacific supplies the fastest expansion anywhere in the Sports Medicine Market. China's centralised volume-based procurement has compressed implant pricing sharply, but unit volumes have more than absorbed the hit [22]. India's combination of the Khelo India sports science network and PLI manufacturing incentives is producing a genuine domestic supplier base for the first time [15].

South America

Country Metric Key Driver
Brazil 61.3% of region Football-driven injury volume and private plans [24]
Argentina USD 0.07 Billion Rugby and football club medical programmes [24]
Rest of South America 7.63% CAGR Chilean and Colombian insurance growth [24]


Brazil dominates regional demand, with roughly 50 million supplementary health plan members underwriting elective orthopedic access [24]. Club-affiliated sports medicine departments at top-flight football organisations have become early adopters of biologic adjuncts, though currency volatility keeps imported implant pricing unpredictable.

Middle East & Africa

Country Metric Key Driver
Saudi Arabia 31.7% of region Quality of Life Program sports investment [10]
UAE USD 0.09 Billion Medical tourism and specialist orthopedic hospitals [25]
South Africa 18.2% of region Private hospital group capacity [25]
Egypt 9.41% CAGR Universal health insurance rollout [25]
Rest of MEA 12.6% of region Gulf and North African facility buildout [25]


Gulf states are effectively purchasing a sports medicine ecosystem. Saudi Arabia's programme spending exceeded USD 3 billion on facilities and participation since 2019, with imported clinical talent staffing new orthopedic centres [10]. Egypt's phased universal health insurance rollout will extend elective orthopedic access to populations previously priced out entirely [25].


Sports Medicine Market By Region, 2025-2035

Sports Medicine Market Segmentation

By Product Type

Product mix within the Sports Medicine Market is shifting toward disposables and soft-goods rather than structural metal.

Segment Metric (2025) Primary Demand Driver
Orthopedic Implants 38.4% share Ligament and rotator cuff fixation volume
Arthroscopy Devices 8.71% CAGR Minimally invasive technique adoption
Braces & Supports USD 1.34 Billion Conservative management and post-op protocols
Prosthetics & Orthotics 6.42% CAGR Amputee sport and adaptive athletics
Body Monitoring & Evaluation 10.15% CAGR Wearable-enabled recovery tracking
Body Compression & Recovery USD 0.61 Billion Recreational athlete self-care spending
Accessories & Other Products 6.9% share Bundled procedure kit content


Orthopedic implants remain the revenue backbone, though their share drifts down roughly 40 basis points annually as suture-based and biologic alternatives displace hardware. Arthroscopy devices tell the more interesting story: single-use shaver blades, radiofrequency wands, and cannula sets convert a capital-led category into a recurring consumable stream, which is precisely why the fastest-growing product line is also the most defensible commercially.

By Application

Anatomical demand in the Sports Medicine Market clusters heavily around load-bearing joints.

Segment Metric (2025) Primary Demand Driver
Knee 32.7% share ACL and meniscal procedure volume
Shoulder 8.15% CAGR Rotator cuff and labral repair growth
Foot & Ankle USD 0.71 Billion Running and court-sport injury incidence
Hip & Groin 7.88% CAGR Femoroacetabular impingement recognition
Elbow 5.9% share Overhead throwing athlete procedures
Hand & Wrist USD 0.44 Billion Contact sport fracture management
Spine USD 0.51 Billion Axial load injuries in collision sports
Other Injuries 6.98% CAGR Soft tissue and muscle repair


Knee procedures dominate because ACL reconstruction combines high incidence, near-universal surgical indication in active patients, and premium implant content. Shoulder is the segment to watch. Improved MRI access has lifted diagnosed rotator cuff pathology substantially in patients over 50, and repair rather than conservative management is now the default in most high-income systems.

By End User

Care-setting migration is the clearest structural trend in the Sports Medicine Market.

Segment Metric (2025) Primary Demand Driver
Hospitals 44.9% share Complex, multi-ligament and revision cases
Ambulatory Surgical Centres 9.84% CAGR Reimbursement parity and surgeon ownership
Home Care USD 0.93 Billion Post-operative bracing and tele-rehab
Other End Users 6.2% share Team facilities and university sports clinics


Hospitals retain the majority of revenue but are losing the profitable middle of the case mix. What remains is complexity: revisions, polytrauma, and comorbid patients. ASCs, meanwhile, are compounding at nearly 10% and increasingly dictate product specifications — vendors that cannot supply compact, low-inventory, rep-light kits are simply not competitive in that channel.


Competitive Benchmarking

Concentration is moderate. The estimated HHI sits near 1,150, with the top five suppliers holding an aggregate 52–58% of global revenue. Below that tier the field fragments quickly into bracing specialists, regional distributors, and biologics entrants. Competitive advantage in the Sports Medicine Market increasingly rests on surgeon education infrastructure and instrument ecosystems rather than implant differentiation alone.

Company Est. Revenue Share Range Key Offerings for Sports Medicine Market Strategic Positioning
Arthrex, Inc. ~19–23% Suture anchors, arthroscopy towers, biologics Category leader; unmatched surgeon education network
Smith & Nephew plc ~12–15% REGENETEN, arthroscopic enabling technologies Biologic-led differentiation, strong EMEA base
Stryker Corporation ~9–12% Sports medicine implants, visualisation systems Capital-plus-consumable bundling strength
DePuy Synthes (Johnson & Johnson) ~7–9% MITEK sports medicine portfolio Broad orthopedic cross-sell leverage
CONMED Corporation ~5–7% Arthroscopy devices, fixation systems Focused pure-play with ASC-aligned pricing
Zimmer Biomet Holdings ~4–6% Soft tissue repair, joint preservation Data and robotics adjacency
Enovis (DJO Global) ~4–6% Bracing, recovery science, orthopedic devices Leading conservative-care franchise
Össur hf. ~2–4% Braces, supports, prosthetic solutions Design-led premium bracing brand
Breg, Inc. ~2–3% Post-operative bracing, cold therapy Strong U.S. ASC and clinic distribution
Bauerfeind AG ~1–3% Medical compression, orthoses German engineering heritage, retail reach
Performance Health ~1–3% Rehabilitation and recovery products Clinic and home-care channel depth


Recent News & Developments

  • Smith & Nephew (October 2023): Reported expanded clinical results for its bioinductive rotator cuff implant, strengthening the evidence base for biologic augmentation in tendon repair [3].
  • CMS (November 2023): Finalised further additions to the ASC Covered Procedures List for calendar year 2024, extending outpatient eligibility for additional orthopedic codes [1].


  • Enovis (January 2024): Completed integration of its Lima Corporate acquisition, broadening reconstructive capability alongside its bracing franchise [12].


Sports Medicine Market Report Scope

Parameter Detail
Market Scope Global Sports Medicine Market by product type, application, end user, and geography
Study Period 2021–2035 (Historical 2021–2024; Base Year 2025; Forecast 2026–2035)
CAGR 7.29% (2026–2035)
Market Size Checkpoints USD 7.72 Billion (2025); USD 8.28 Billion (2026); USD 15.60 Billion (2035)
Fastest Growing Segments Ambulatory Surgical Centres (end user); Body Monitoring & Evaluation (product); Asia-Pacific (region)
Companies Profiled Arthrex, Smith & Nephew, Stryker, DePuy Synthes, CONMED, Zimmer Biomet, Enovis, Össur, Breg, Bauerfeind, Performance Health
Valuation Currency USD, constant 2025 prices
CAGR Driver Disclaimer Driver and restraint impact percentages are directional analyst estimates and are not additive to the headline CAGR

FAQs

How should procurement teams evaluate vendors in the Sports Medicine Market beyond unit price?
Weight instrument ecosystem lock-in, tray footprint, and revision-rate evidence over list price. Registry-backed revision data predicts total episode cost far better than implant invoice value [20].
What acquisition activity should investors watch in the Sports Medicine Market?
Bracing and recovery-product assets are the most likely targets, since they offer recurring revenue without capital intensity. Biologics platforms with completed randomised trials also command premium multiples [12].
Are single-use arthroscopy instruments actually cheaper than reusable sets?
For centres under roughly 400 annual cases, yes — sterilisation labour and reprocessing overhead dominate. High-volume hospitals with existing central sterile capacity usually still favour reusables [1].
What integration challenges arise when adopting wearable recovery monitoring?
Electronic health record interoperability is the main obstacle, since most rehabilitation platforms lack native FHIR integration. Clinician workflow time, not device cost, determines whether adoption survives past pilot [11].
How does the Sports Medicine Market differ from general orthopedics in buyer behaviour?
Surgeon preference carries far more weight here because technique and instrumentation are tightly coupled. Committee-led standardisation succeeds less often than in arthroplasty [3].
Which regulatory nuance most affects new market entrants in Europe?
Notified body capacity, not the regulation itself. Queue times for MDR conformity assessment have exceeded twelve months for some device classes, delaying launch economics materially [2].
What emerging use case deserves attention over the next five years?
Pre-participation biomechanical screening in school and collegiate programmes. It shifts spending toward assessment and bracing while reducing downstream surgical volume [8].      
Author
Author Author Profile Satyendra Maurya LinkedIn Research Analyst
An accomplished research analyst with high proficiency in market forecasting, data visualization, competitive benchmarking, and others. He holds a pronounced track record in research and consulting projects for sectors such as life sciences, medical devices, and healthcare IT. His capabilities in qualitative and quantitative analysis have resulted in positive client outcomes. Working on niche market trends, opportunities, sales, and forecasted value is part of his skill set.
Co-Author Co-Author Profile Rahul Gotadki LinkedIn Research Manager
He holds an experience of about 9+ years in Market Research and Business Consulting, working under the spectrum of Life Sciences and Healthcare domains. Rahul conceptualizes and implements a scalable business strategy and provides strategic leadership to the clients. His expertise lies in market estimation, competitive intelligence, pipeline analysis, customer assessment, etc.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of regulatory medical device databases, peer-reviewed orthopedic and sports science journals, clinical outcome registries, and authoritative musculoskeletal health organizations. Key sources included the US Food & Drug Administration (FDA) Center for Devices and Radiological Health (CDRH), European Medicines Agency (EMA), Health Canada, Therapeutic Goods Administration (TGA), National Medical Products Administration (NMPA), American Academy of Orthopaedic Surgeons (AAOS), American Orthopaedic Society for Sports Medicine (AOSSM), American Medical Society for Sports Medicine (AMSSM), Arthroscopy Association of North America (AANA), National Athletic Trainers' Association (NATA), American College of Sports Medicine (ACSM), International Federation of Sports Medicine (FIMS), International Olympic Committee (IOC) Medical & Scientific Commission, FIFA Medical Committee, National Institutes of Health (NIH)/National Institute of Arthritis and Musculoskeletal and Skin Diseases (NIAMS), National Center for Biotechnology Information (NCBI/PubMed), Cochrane Library (sports injury interventions), Centers for Disease Control and Prevention (CDC) National Health Statistics Reports (sports injury surveillance), World Health Organization (WHO) Global Burden of Disease Study (musculoskeletal injuries), AAOS National Clinical Registries (American Joint Replacement Registry - AJRR), NCAA Injury Surveillance Program, National Center for Catastrophic Sport Injury Research (NCCSIR), and national sports medicine registries from key markets.

These sources were employed to gather procedural statistics (ACL reconstructions, arthroscopy volumes, fracture repairs), regulatory approval data for implants and arthroscopy devices, clinical safety and efficacy studies for orthobiologics, injury epidemiology trends, and competitive landscape analysis for the body reconstruction & repair, body support & recovery, and body monitoring & evaluation segments.


Primary Research

Qualitative and quantitative insights were obtained by interviewing supply-side and demand-side stakeholders during the primary research process. CEOs, VPs of Product Development, leaders of Regulatory Affairs, and Commercial Directors from sports medicine device manufacturers, arthroscopy system developers, orthopedic implant OEMs, and orthobiologics suppliers comprised the supply-side sources. Demand-side sources included board-certified orthopedic surgeons (sports medicine specialists), fellowship-trained arthroscopists, head team physicians from professional and collegiate sports organizations, certified athletic trainers, physical therapists, medical directors of ambulatory surgery centers, and procurement leads from orthopedic clinics, hospital sports medicine departments, and physiotherapy centers. Primary research has confirmed the product pipeline timelines for next-generation suture anchors and biologic grafts, validated market segmentation across reconstruction implants, arthroscopy devices, fracture repair systems, prosthetics, orthobiologics, and rehabilitation equipment, and gathered insights on surgical adoption patterns (shift toward outpatient/ASC settings), value-based pricing strategies, reimbursement dynamics for minimally invasive procedures, and return-to-play protocol standardization.

Primary Respondent Breakdown:

By Designation: C-level Primaries (40%), Director Level (25%), Others (35%)

By Region: North America (40%), Europe (25%), Asia-Pacific (22%), Rest of World (13%)


Market Size Estimation

Revenue mapping and procedural volume analysis were employed to determine the global market valuation of orthopedic surgical devices, arthroscopy systems, and rehabilitation technologies. The methodology comprised the following:

The identification of over 50 main manufacturers in North America, Europe, Asia-Pacific, Latin America, and the Middle East and Africa who specialize in physiotherapy equipment, arthroscopy devices, and implants

Product mapping encompasses body reconstruction and repair (arthroscopy devices, implants, fracture/ligament repair, orthobiologics, prosthetics), body support and recovery (braces and supports, compression wear, rehabilitation equipment), body monitoring and evaluation (cardiac/hemodynamic monitors, musculoskeletal sensors), and accessories.

Examination of annual revenues that are specific to sports medicine portfolios, such as arthroscopy visualization systems, suture anchors, interference fasteners, and biologic grafts, as reported and modeled

Coverage of manufacturers that account for 75-80% of the global market share in 2024, including comprehensive data from Arthrex, Inc., Stryker Corporation, Smith & Nephew plc, Zimmer Biomet Holdings, Johnson & Johnson (DePuy Synthes), CONMED Corporation, and Karl Storz SE & Co. KG. Extrapolation using bottom-up (procedure volume × ASP by country for knee arthroscopy, shoulder reconstruction, ACL repair, and ankle stabilization) and top-down (manufacturer revenue validation across implant and instrument portfolios) approaches to derive segment-specific valuations for minimally invasive surgical devices and regenerative biologics.

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.
















