Spark Plasma Sintering Market Summary
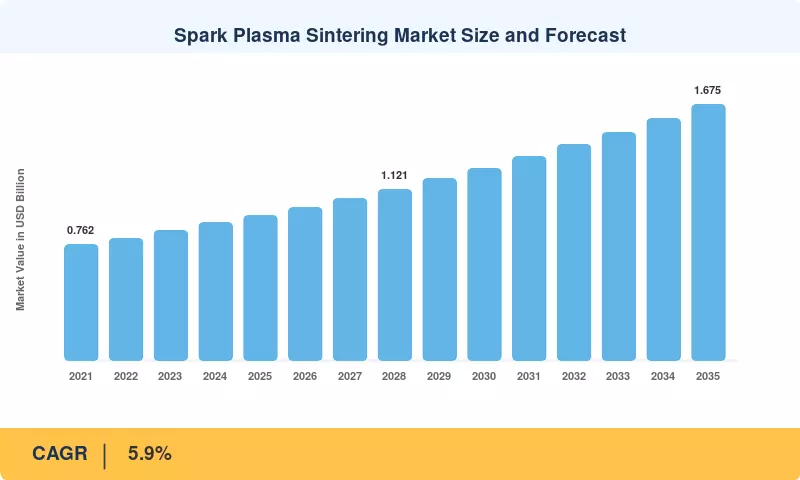
The Spark Plasma Sintering Market was valued at USD 0.95 Billion in 2025 and is projected to reach USD 1.00 Billion in 2026, expanding at a CAGR of 5.9% to USD 1.68 Billion by 2035. Two catalysts anchor this trajectory. Defense agencies are funding ultra-high-temperature ceramics for hypersonic airframes, with the U.S. Department of Defense requesting roughly USD 6.9 billion for hypersonic programs in FY2025 [2]. Semiconductor reshoring under the USD 52.7 billion CHIPS and Science Act is also lifting demand for dense sputtering targets and thermal-management substrates [3].
Underneath the headline figures, a quiet process shift is underway. Conventional hot pressing and pressureless furnace sintering, which need hours of soak time, are giving way to pulsed direct-current consolidation that densifies powders in minutes while suppressing grain growth [11]. This advanced powder metallurgy technology lets engineers retain nanostructures that older routes destroy. Public research budgets reinforce the transition: Horizon Europe carries a EUR 95.5 billion envelope, and a meaningful share of its materials calls fund field-assisted sintering work [10].
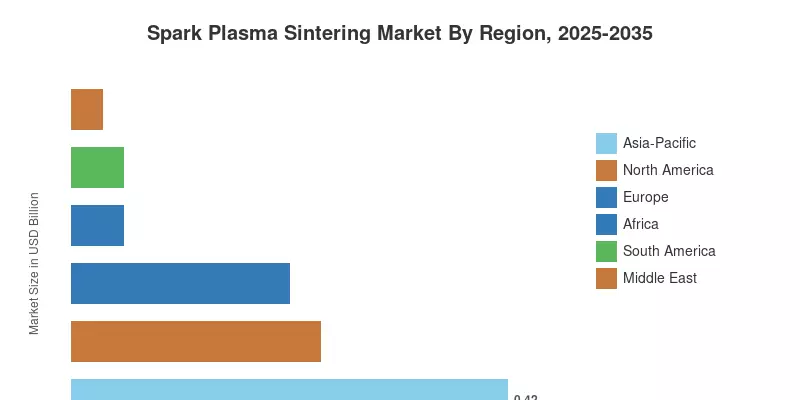
Asia-Pacific dominates with a 44.5% share in 2025 and is also the fastest-growing region at a 6.6% CAGR, supported by Japanese equipment heritage and Chinese battery-materials investment. North America ranks second, propelled by defense and national-laboratory programs. Over the next decade, the Spark Plasma Sintering Market will move from laboratory-scale presses toward production-grade systems serving electrified mobility and aerospace.
Key Report Takeaways
• By Component
- Equipment accounted for 56.5% of Spark Plasma Sintering Market revenue in 2025, reflecting continued press purchases by universities and pilot lines
- Consumables (Graphite Dies, Punches, Foils) generated USD 0.25 Billion in 2025 as recurring tooling replacement
- Services (Installation, Maintenance, Retrofits) is the fastest-growing component at a 7.2% CAGR
• By Press Capacity
- The 100–500 Ton class held a 58.2% share, balancing part size, cycle time and floor space
- Presses rated >500 Ton are expanding at a 7.3% CAGR on battery and aerospace scale-up
- The <100 Ton class was worth USD 0.21 Billion, concentrated in academic labs
• By Material Processed
- Ceramics represented 46.8% of throughput, led by alumina tools and zirconia implants
- Functionally-Graded Materials posted the fastest growth at a 6.9% CAGR
- Metals and Alloys contributed USD 0.24 Billion, anchored by tungsten and titanium aluminide parts
• By End-Use Industry
- Aerospace and Defense captured 31.8% of Spark Plasma Sintering Market sales in 2025
- Automotive is the fastest-growing end use at a 6.3% CAGR, driven by EV power electronics and ceramic brakes
- Electronics and Semiconductor held a 19.6% share in thermoelectric and target production
• By Region
- Asia-Pacific led with a 44.5% share in 2025 and remains the growth engine
- North America generated USD 0.24 Billion, backed by defense and national-laboratory demand
- Europe held a 22.0% share on Horizon Europe-funded research infrastructure
Market Size and Forecast (2021–2035)
Historical values for the Spark Plasma Sintering Market were reconstructed from equipment shipment records, consumables procurement data, company disclosures and interviews with press manufacturers, service bureaus and laboratory managers. Forecast values apply a calibrated growth path from the 2026 base, cross-checked against installed-base replacement cycles and end-use capital-expenditure plans.




 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA



