Solar Pv Backsheet Market Summary
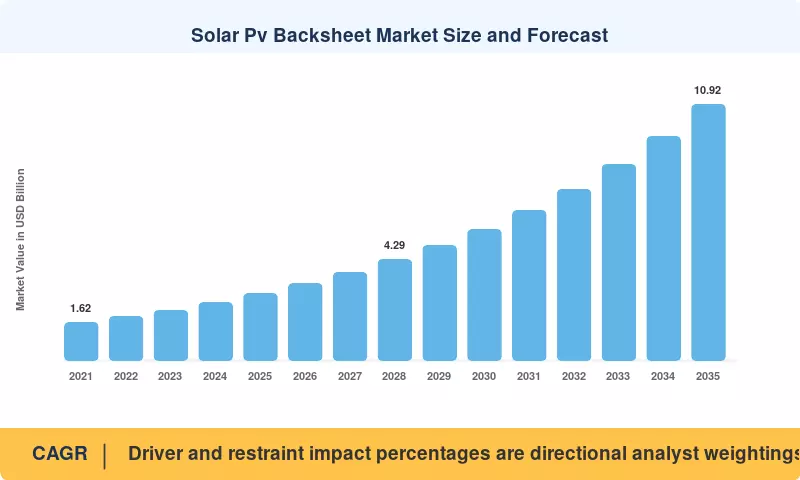
The Solar PV Backsheet Market reached USD 2.87 billion in 2025 and opens the forecast window at USD 3.28 billion in 2026, advancing to USD 10.92 billion by 2035 at a 14.3% CAGR. Two catalysts anchor that trajectory. Global annual photovoltaic module output crossed 650 GW of nameplate capacity in 2024. China's 14th Five-Year Plan renewable targets plus the U.S. Inflation Reduction Act's 45X advanced manufacturing credit — worth roughly USD 0.07 per watt for module assembly — have pulled encapsulation and backsheet converting capacity closer to module fabs [1][2][4].
Material replacement is changing the bill of materials under that volume. Legacy PET-core laminates with polyamide outer layers that have had verified field cracking across installations commissioned between 2011 and 2016 are being displaced by fluoropolymer-faced and coextruded polyolefin constructions. Buyers stipulate in supplier contracts that a PVDF fluoropolymer solar backsheet has to withstand 3,000-hour damp-heat and UV exposure cycles, and this captures most of the value pool today. Manufacturers pledged more than USD 1.4 billion for backsheet and encapsulant capacity from 2023 to 2025 .
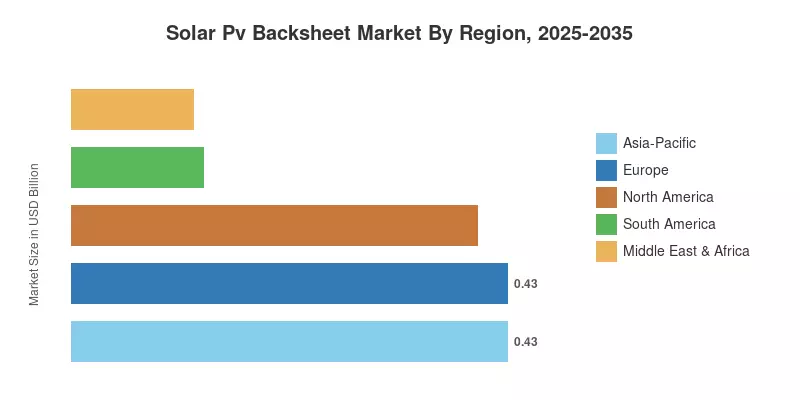
Asia-Pacific owns 62.4% of the Solar PV Backsheet Market regionally, indicating the concentration of cell and module assembly in China, Vietnam, Malaysia and India. India is the fastest-growing single country with a CAGR of 17.4% driven by the Approved List of Models and Manufacturers regulation and Production Linked Incentive plan. Europe, which accounts for 15.1% of worldwide revenue, is in second place and has continued support through repowering activity and more stringent durability qualification. With scaling of bifacial structures [5][7], the value split will shift further toward transparent and lightweight constructions.
Key Report Takeaways
• By Material Type
- Fluoropolymer constructions command 66.8% of Solar PV Backsheet Market revenue in 2025, reflecting their advantage in hydrolysis and UV resistance.
- Non-fluoropolymer coextruded polyolefin grades post the dimension's fastest expansion at a 16.9% CAGR through 2035
• By Application
- Utility-scale ground-mount installations generate USD 1.71 billion of 2025 demand, the largest single application pool.
- Commercial and industrial rooftop systems grow at a 15.2% CAGR as distributed generation mandates tighten in the EU and Japan.
- Floating and off-grid deployments hold 4.3% of application revenue but attract disproportionate qualification spending.
• By Geography
- Asia-Pacific anchors the Solar PV Backsheet Market with a 15.1% CAGR over 2026–2035, the highest of any region.
- North America accounts for 13.8% of 2025 global revenue, lifted by domestic content thresholds.
- Middle East & Africa contributes USD 0.12 billion in 2025, with Saudi and Emirati gigawatt tenders driving high-UV specification work.
Market Size and Forecast (2021–2035)
Figures below are compiled from a combination of: module shipment data from national customs filings and industry associations; converter capacity checks across 40+ manufacturing locations; and bottom-up pricing gathered from module OEM procurement teams spanning China, India, Germany and the United States. Historical values are reconciled against installed DC capacity reported by the International Energy Agency Photovoltaic Power Systems Program, then normalized for backsheet-per-watt intensity that declined from about 0.041 to 0.033 USD/W from 2021 to 2025 as thickness reduction and glass-glass substitution advanced [1][8].




 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA


