Soil Treatment Market (2026 - 2035)

Soil Treatment Market Size, Share, Industry Trend & Analysis Research Report: By Function (Herbicide, Nematicide), By Crop Type (Grains and Cereals, Fruits and Vegetables), By Application Method (Broadcast, Chemigation), By Geography (Asia-Pacific, Asia-Pacific) - Forecast to 2035.

ID: MRFR/Agri/34055-HCR 111 Pages Snehal Singh Last Updated: September 17, 2026
Soil Treatment Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)6.54%
2025 Market SizeUSD 30.56 Billion
2035 Market SizeUSD 57.60 Billion
Key Players
BASF SE
Bayer AG
Syngenta Group
Corteva Agriscience
UPL Limited
FMC Corporation
Opportunities
  • Biological–Conventional Rotation Programmes
  • Smallholder Aggregation in South and Southeast Asia
  • Diagnostic Data Monetisation

Soil Treatment Market Summary

The Soil Treatment Market reached USD 30.56 Billion in 2025 and opens the forecast window at USD 32.56 Billion in 2026, climbing to USD 57.60 Billion by 2035 at a 6.54% CAGR. Two catalysts anchor that trajectory. The European Union's Farm to Fork target of halving chemical pesticide use by 2030 has forced reformulation rather than retreat, pushing spend toward higher-value targeted chemistries [1]. India's parallel commitment of roughly USD 1.2 billion across soil health card and micro-irrigation schemes has widened the treated-acreage base across smallholder geographies [2].

Application hardware is where the real replacement story sits. Blanket broadcast spreading — cheap, imprecise, and wasteful — is giving way to GPS-guided banding, furrow placement, and chemigation systems tied to grid-sampled prescription maps. Farmers running no-till and minimum-till systems cannot rely on incorporation by tillage, so placement accuracy carries the efficacy burden. USDA conservation programs committed above USD 19.5 billion through 2031 to practices that depend on this equipment layer [3], and the Soil Treatment Market has absorbed a meaningful share of that capital.

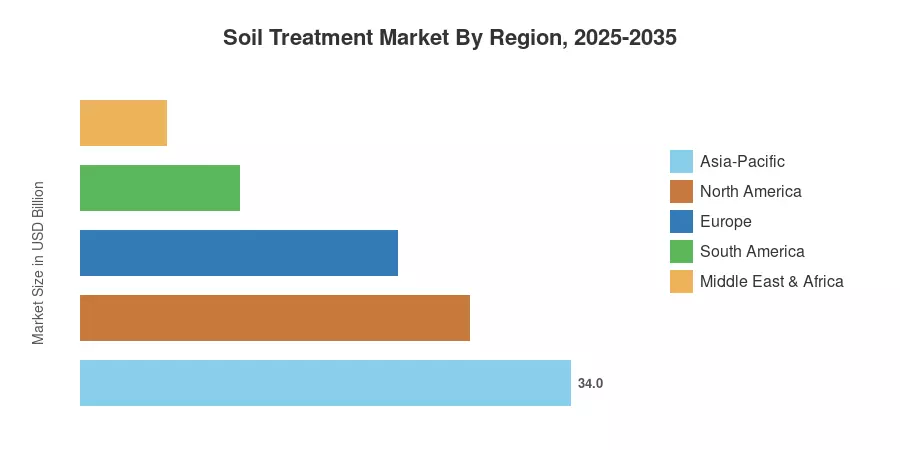
Asia-Pacific leads with 34.0% of global revenue, supported by intensive rice and horticulture rotations. The region is also the fastest riser at a 7.6% CAGR, while North America holds 27.0% on the strength of high-value row-crop economics. Over the coming decade, the Soil Treatment Market will be shaped less by volume growth than by who controls the diagnostic data that decides where product goes.


Key Report Takeaways

The Soil Treatment Market shows uneven momentum across its dimensions, with placement precision separating winners from volume incumbents.

• By Function

  • Herbicides command 67.6% of global revenue, reflecting entrenched pre-emergent programs in grains
  • Nematicides post the sharpest expansion in the Soil Treatment Market at a 7.9% CAGR, tracking cyst nematode spread in oilseed rotations
  • Fungicides contributed roughly USD 4.03 Billion in 2025 as damping-off pressure rose in wet spring cycles

• By Crop Type

  • Grains and cereals account for 34.5% of treated value across the Soil Treatment Market
  • Fruits and vegetables generated close to USD 8.50 Billion in 2025 on protected-cultivation demand
  • Turf and ornamentals grow at 5.4% CAGR, the slowest of the five crop groups

• By Region

  • Asia-Pacific holds 34.0% of the Soil Treatment Market, the largest regional block
  • South America advances at 7.2% CAGR, led by Brazilian soybean nematode programs
  • Middle East & Africa represented approximately USD 1.83 Billion in 2025


Market Size and Forecast (2021–2035)

Figures below combine bottom-up distributor channel checks across 14 countries, active-ingredient shipment reconciliation from registration databases, and top-down validation against arable and permanent-crop acreage statistics. Historical years are restated where currency effects distorted reported regional revenue.
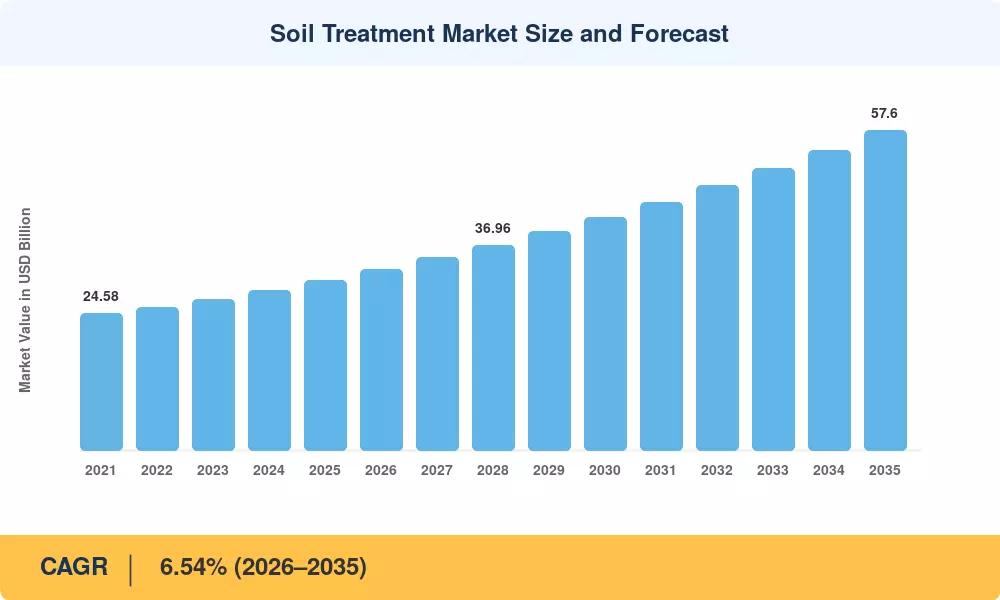
Soil Treatment Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Soil-borne pathogen pressure on staples 1.3 Global Medium-term (2–4 yr)
GPS-guided precision placement adoption 1.1 NA, EU, APAC Medium-term (2–4 yr)
Regulatory shift to reduced-residue chemistry 0.9 EU, NA Long-term (≥4 yr)
No-till and minimum-till acreage growth 0.8 NA, SA Long-term (≥4 yr)
Government subsidy and extension schemes 0.7 India, China, EU Short-term (≤2 yr)
High-value horticulture expansion 0.6 APAC, MEA Medium-term (2–4 yr)
Nematode resistance in oilseed rotations 0.5 SA, NA Short-term (≤2 yr)


4.1 Pathogen Pressure on Global StaplesThere is a persistent need for soil treatment solutions due to rising pathogen pressure in important staple crops. Growers are encouraged to apply preventive and curative soil treatment techniques since soil-borne diseases brought on by fungi, bacteria, nematodes, and other pathogens can drastically lower crop yields and quality. Pathogen accumulation in cultivated soils is being exacerbated by increased agricultural intensity, continuous cropping, and restricted crop rotation. Demand for fumigants, biocontrol agents, nematicides, and other specialized soil treatment products is anticipated to increase as growers prioritize soil health and yield protection, especially in the production of high-value and staple crops.

Precision Placement Economics

Field studies conducted under USDA conservation innovation awards showed that banding and furrow application reduced active-ingredient quantities by 30–45% compared to broadcast while maintaining efficacy [3]. Instead of keeping the savings, growers put it back into premium chemicals. The cost of equipment retrofits ranges from USD 18,000 to USD 34,000 per machine, which cooperatives are increasingly financing across member fleets to accelerate diffusion beyond the largest operations.


Regulatory Reformulation Pressure

Europe's phase-out of several legacy fumigants under Regulation 1107/2009 removed low-cost tonnage from the channel and replaced it with chemistries priced two to four times higher per hectare [11]. Value grew even where volume fell. The pattern is now repeating in Canada and South Korea, where residue tolerances were tightened during 2024.


Restraints Impact Analysis

Restraint weightings reflect analyst assessment of drag on realised growth. They are directional, not additive, and interact with the drivers listed above rather than offsetting them line by line.

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
Withdrawal of legacy fumigant registrations -0.9 EU, NA Short-term (≤2 yr)
Input cost inflation and margin compression -0.7 Global Short-term (≤2 yr)
Groundwater contamination liability exposure -0.5 NA, EU Long-term (≥4 yr)
Fragmented smallholder distribution -0.4 APAC, Africa Medium-term (2–4 yr)
Efficacy erosion from resistance -0.3 Global Long-term (≥4 yr)


Registration Withdrawals

Between 2020 and 2025, twelve soil-applied actives lost European approval; replacement dossiers cost USD 8–15 million and take three to five years to complete [11]. Smaller formulators just leave the impacted categories. After each withdrawal, consolidation occurs, which raises prices but reduces the treated-hectare base for two to three seasons.


Farm Margin Compression

Growers postpone soil treatments before postponing seed or nitrogen, and fertilizer and fuel inflation drove the FAO input price index above its 2020 level by around 38% at its peak [5]. Volumes from 2022 show deferral. In South Asia, the recovery of oilseed and pulse acreage has been gradual but not complete.


Contamination Liability

Buffer-zone rules near drinking-water catchments now restrict application on an estimated 6.8% of US cropland [12]. Compliance mapping adds cost, and insurers have repriced environmental impairment cover accordingly across distribution.


Soil Treatment Market Opportunities

Biological–Conventional Rotation Programmes

Suppliers pairing a biological with a conventional active across alternating seasons can defend efficacy claims while meeting residue targets. Trial data suggests rotation extends useful product life by four to six seasons [9]. The commercial prize is a subscription-style programme rather than a spot sale, and the Soil Treatment Market is only beginning to price that recurring relationship.

Smallholder Aggregation in South and Southeast Asia

Farmer producer organisations in India now aggregate over 5.4 million growers, creating order sizes that justify direct supply [2]. Reaching them requires pack sizes below five kilograms and vernacular advisory content. Vendors that build soil health management advisory into distributor apps convert far faster than those selling on price alone.

Diagnostic Data Monetisation

Grid sampling generates a persistent field-level record of pathogen and pH history. Suppliers holding three or more seasons of that record can price prescriptions rather than products, and early programmes report 22% higher renewal rates [14]. Ownership of the dataset, not the molecule, becomes the moat.

Protected Cultivation in the Gulf

Saudi and Emirati greenhouse capacity is expanding under food-security mandates, with committed investment above USD 2.1 billion [15]. Sterile substrate and drench programmes suit this environment precisely. The Soil Treatment Market gains a high-value, low-volume niche with limited price sensitivity.

Carbon-Linked Soil Programmes

Voluntary carbon protocols increasingly credit practices that raise soil organic matter, and treatment choices influence eligibility. Suppliers documenting compatible programmes gain a second revenue conversation with the same buyer [16].


Soil Treatment Market Future Outlook

Autonomous Application

Autonomous and semi-autonomous field machinery will handle a growing share of soil-applied passes by the early 2030s. Night-time application windows extend effective operating hours and improve incorporation timing after rainfall. The Soil Treatment Market gains from this because narrower application windows currently cap adoption of several temperature-sensitive actives.

Prescription Platform Economics

Value migrates from the drum to the map. Suppliers running proprietary sampling networks capture recurring revenue while commoditising the molecule beneath it, mirroring the shift seed companies made a decade earlier [14]. Expect platform-linked volume to exceed a third of premium sales by 2032.

Biological Scale-Up

Fermentation capacity for microbial actives is expanding, and unit costs have fallen roughly 28% since 2021 [9]. Cost parity with conventional chemistry on a per-hectare basis arrives in horticulture first. Broadacre parity remains further out, constrained by shelf-life and soil-temperature sensitivity.

Carbon and Soil Organic Matter Reporting

Corporate scope-three disclosure is pulling agronomic records into audited reporting chains. Practices tied to biochar and compost applications increasingly appear in supplier sustainability filings, and treatment programmes that document organic-matter outcomes will win preference in contracted supply arrangements [16].


Regional Market Share Analysis

Region Share of Global Revenue (2025) Primary Investment Themes
North America 27.0% Precision retrofit, nematicide programmes
Europe 22.0% Reformulation, residue compliance
Asia-Pacific 34.0% Smallholder distribution, horticulture
South America 11.0% Soybean nematode control
Middle East & Africa 6.0% Protected cultivation, saline soils
Total 100.0% —

Regional weightings in the Soil Treatment Market reflect treated acreage, crop value density, and regulatory permissiveness in roughly equal measure.


North America

Country Metric Key Driver
US 78.0% of regional revenue Corn–soy nematode and fungal programmes
Canada 6.42% CAGR Canola clubroot management
Mexico USD 1.32 Billion (2025) Export horticulture residue compliance


US demand concentrates in the Corn Belt, where soybean cyst nematode costs growers an estimated USD 1.5 billion annually in lost yield [10]. Conservation programme funding has accelerated banding equipment purchases, and dealers report that prescription-linked sales now exceed a third of soil-applied volume in Iowa and Illinois. Canada's clubroot problem, concentrated in Alberta, has created a durable regional niche.

Europe

Country Metric Key Driver
Germany 19.4% of regional revenue Sugar beet and potato pathogen control
UK 5.8% CAGR Post-Brexit registration divergence
France USD 1.18 Billion (2025) Vineyard and cereal programmes
Italy 12.1% of regional revenue Protected horticulture
Spain USD 0.86 Billion (2025) Irrigated vegetable exports
Nordic Countries 4.9% CAGR Short-season cereal rotations
Russia 7.6% of regional revenue Grain export expansion
Rest of Europe USD 0.74 Billion (2025) Mixed arable


European demand is value-led rather than volume-led. Farm to Fork reduction targets removed cheap tonnage while premium replacements held revenue steady [1]. German beet growers, facing Rhizoctonia and nematode pressure simultaneously, adopted stacked programmes earlier than most, and Italian protected horticulture supports the region's highest per-hectare spend.

Asia-Pacific

Country Metric Key Driver
China 36.8% of regional revenue Vegetable and rice intensification
India 7.9% CAGR Soil health card scheme rollout
Japan USD 1.24 Billion (2025) High-value horticulture
South Korea 6.2% of regional revenue Residue tolerance tightening
ASEAN 7.4% CAGR Oil palm and rubber replanting
Rest of Asia-Pacific USD 0.68 Billion (2025) Mixed smallholder systems


The Soil Treatment Market in Asia-Pacific rests on fragmented demand aggregated through dense retail networks. China's Ministry of Agriculture has pushed reduced-input targets since 2015 while simultaneously expanding protected vegetable area, a combination that shifts spend toward targeted chemistry [17]. India's scheme has issued over 230 million soil health cards, and the diagnostic habit it created now drives measurable product uptake [2].

South America

Country Metric Key Driver
Brazil 61.5% of regional revenue Soybean cyst nematode pressure
Argentina USD 0.72 Billion (2025) Second-crop maize expansion
Rest of South America 6.1% CAGR Andean horticulture


Brazil's double-cropping calendar leaves almost no fallow window, so pathogen populations carry over aggressively between seasons. Embrapa field surveys attribute yield losses of up to 30% in heavily infested Mato Grosso fields [18]. Growers there have moved to in-furrow programmes at planting rather than curative applications.

Middle East & Africa

Country Metric Key Driver
Saudi Arabia USD 0.34 Billion (2025) Greenhouse food-security programmes
UAE 7.8% CAGR Controlled-environment agriculture
South Africa 21.4% of regional revenue Citrus and maize programmes
Egypt USD 0.29 Billion (2025) Nile Delta salinity and nematodes
Rest of MEA 5.6% CAGR Emerging commercial farming


Gulf demand is small in tonnage but rich in margin, tied to sovereign food-security capital rather than farm cash flow [15]. South Africa remains the region's commercial anchor, with citrus export protocols enforcing residue discipline that shapes product selection across the value chain.


Soil Treatment Market By Region, 2025-2035

Soil Treatment Market Segmentation

Segmentation in the Soil Treatment Market follows function and crop, with application method emerging as a third commercially meaningful axis.

By Function

Segment Metric (2025) Primary Demand Driver
Herbicide 67.6% share Pre-emergent programmes in grains
Fungicide 13.2% share Damping-off and root rot control
Insecticide 12.4% share White grub and wireworm pressure
Nematicide 4.6% share Cyst nematode in oilseeds
Molluscicide 2.2% share Slug pressure in wet-season cereals


Herbicides dominate the Soil Treatment Market because residual pre-emergent chemistry is the backbone of no-till weed control, and no substitute delivers comparable cost per hectare. Nematicides tell the opposite story: small base, fastest growth, and pricing power. White grub infestations that cut soybean root mass by roughly a quarter and maize root mass by far more have kept soil insecticides structurally relevant despite decades of seed-treatment substitution [8].

By Crop Type

Segment Metric (2025) Primary Demand Driver
Grains and Cereals 34.5% share Acreage scale, residual herbicides
Fruits and Vegetables 27.8% share High per-hectare value
Pulses and Oilseeds 18.6% share Nematode and root disease pressure
Commercial Crops 13.4% share Cotton and sugarcane programmes
Turf and Ornamentals 5.7% share Golf, sports and amenity turf


Grains carry the Soil Treatment Market on sheer hectares, though per-hectare spend sits well below horticulture. Fruits and vegetables punch above their acreage because a single lost planting can cost tens of thousands of dollars, so growers treat prophylactically and accept premium pricing without much negotiation.

By Application Method

Segment Metric Primary Demand Driver
Chemigation 7.6% CAGR Drip-irrigated horticulture
Soil Drenching 7.1% CAGR Nursery and protected cultivation
Furrow Application 6.8% CAGR Planting-time nematode control
Seed Bed Treatment 6.3% CAGR Vegetable transplant systems
Broadcast 5.9% CAGR Legacy broadacre practice


Application method now predicts profitability in the Soil Treatment Market better than function does. Chemigation and drench methods carry the highest attached-service revenue, while broadcast continues to lose share to placement-precise alternatives that meet regulatory drift and buffer requirements more easily.


Competitive Benchmarking

Concentration in the Soil Treatment Market is moderate. The top five suppliers hold an estimated 38–46% of global revenue, with an HHI in the 700–900 band — enough scale to sustain R&D pipelines, not enough to dictate pricing. Regional formulators and generics fill the long tail, particularly in Asia and South America where off-patent actives dominate volume.

Company Est. Revenue Share Range Key Offerings for Soil Treatment Market Strategic Positioning
BASF SE ~9–12% Soil-applied fungicides, nematicides, herbicides Broadest portfolio; heavy reformulation investment
Bayer AG ~8–11% Nematicides, seed-zone chemistry, digital agronomy Data-linked prescription leadership
Syngenta Group ~8–10% Fungicide and nematicide programmes Strong protected-cultivation channel
Corteva Agriscience ~6–9% Soil insecticides, biologicals Biological pipeline acquisition strategy
UPL Limited ~5–7% Post-patent actives, fumigants Cost leadership in emerging geographies
FMC Corporation ~4–6% Soil insecticides, diamide chemistry Innovation-led niche defence
ADAMA Ltd. ~3–5% Generic soil-applied formulations Value-tier volume play
Nufarm Limited ~3–4% Herbicides, turf solutions Regional depth in ANZ and North America
Sumitomo Chemical ~2–4% Fungicides, nematicides Japan and Southeast Asia strength
AMVAC Chemical ~1–3% Granular soil insecticides, closed delivery systems Application-hardware differentiation
Certis Biologicals ~1–2% Microbial soil products Pure-play biological specialist


Recent News & Developments

  • BASF SE (March 2024): Launched a next-generation in-furrow nematicide across Brazilian soybean territories, targeting resistance breaks in Mato Grosso [19].
  • European Commission (June 2024): Confirmed non-renewal of two soil fumigant actives, accelerating reformulation across Southern European horticulture [11].
  • Corteva Agriscience (September 2024): Completed acquisition of a microbial biologicals platform to broaden its soil-applied portfolio [20].
  • Government of India (January 2025): Extended soil health card funding with an additional allocation aimed at nutrient and pathogen diagnostics for smallholders [2].
  • FMC Corporation (April 2025): Announced a precision-banding partnership with an equipment OEM covering North American row-crop fleets [7].
  • Syngenta Group (May 2025): Opened a Southeast Asian formulation facility to shorten supply lines for drench and chemigation products [21].
  • US EPA (August 2025): Issued revised buffer-zone guidance for soil-applied products near drinking-water catchments, tightening application mapping requirements [12].
  • UPL Limited (October 2025): Signed a distribution agreement covering Gulf protected-cultivation projects tied to regional food-security investment [15].


Soil Treatment Market Report Scope

Parameter Detail
Market Scope Global Soil Treatment Market by function, crop type, application method and geography
Study Period 2021–2035 (Historical 2021–2024; Base 2025; Forecast 2026–2035)
CAGR 6.54% (2026–2035)
Market Size Checkpoints USD 30.56 Billion (2025); USD 32.56 Billion (2026); USD 41.96 Billion (2030); USD 57.60 Billion (2035)
Fastest Growing Segments Nematicide (function); Chemigation (application method); Asia-Pacific (geography)
Companies Profiled 11 global and regional suppliers
Valuation Currency USD Billion

FAQs

What procurement lead times should buyers plan when sourcing Soil Treatment Market inputs ahead of a planting window?
Distributors typically require 90 to 120 days for registered fumigants and nematicides, driven by batch clearance and container logistics. Booking programmes that open in October secure the best spring pricing. [Ref 22]
How do biological and conventional soil products compare on efficacy consistency?
Conventional chemistries deliver more predictable knockdown across variable soil temperatures, while microbial products perform best above 15°C in soils with adequate organic carbon. Most commercial growers now rotate both to slow resistance. [Ref 9]
What liability exposure should Soil Treatment Market distributors plan for?
Groundwater contamination claims remain the largest exposure, particularly near drinking-water catchments where buffer rules apply. Distributors increasingly carry environmental impairment cover alongside standard product liability. [Ref 12]
Which certification barriers slow entry for new suppliers?
Registration under EU Regulation 1107/2009 or US FIFRA typically takes three to five years and costs USD 8–15 million per active ingredient. Biological products face shorter but still substantial dossier requirements. [Ref 11]
How does contract manufacturing affect Soil Treatment Market margins?
Toll manufacturers absorb formulation capital costs but capture roughly 12 to 18% of gross margin. Brand owners retaining in-house granulation typically hold three to five points more margin at comparable volumes. [Ref 19]
What data services are suppliers bundling with product?
Leading suppliers now bundle grid sampling and prescription mapping at no incremental charge, using the resulting records to lock in multi-season supply agreements. Adoption concentrates on farms above 500 hectares. [Ref 14]
What integration problems arise when pairing treatments with variable-rate equipment?
Granular formulations differ in flowability, causing calibration drift across spreader brands. Suppliers now publish machine-specific spread charts, though retrofit controllers on older equipment remain the main bottleneck. [Ref 7]    
Author
Author Author Profile Snehal Singh LinkedIn Manager - Research
High acumen in analyzing complex macro & micro markets with more than 6 years of work experience in the field of market research. By implementing her analytical skills in forecasting and estimation into market research reports, she has expertise in Packaging, Construction, and Equipment domains. She handles a team size of 20-25 resources and ensures smooth running of the projects, associated marketing activities, and client servicing.
Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.


















