Smart Home Installation Service Market (2026 - 2035)

Smart Home Installation Service Market Size, Share and Research Report By System (Lighting Control, Home Monitoring/Security, Thermostat, Video Entertainment, Smart Appliances, Other Systems), By Channel (Retailers, E-Commerce, Original Equipment Manufacturer (OEM)), By Installation Type (Professional-Installed, Do-It-Yourself (DIY)), By Customer Type (Residential, Commercial/Small Business), By Dwelling Type (Single-Family Homes, Multi-Unit Dwellings, New-Build Constructions, Retrofit Projects), By Connectivity Standard (Wi-Fi, Zigbee, Z-Wave, Thread, Bluetooth Mesh) and By Regional (North America, Europe, South America, Asia Pacific, Middle East and Africa) - Industry Forecast to 2035.
ID: MRFR/ICT/26380-HCR 128 Pages Ankit Gupta, Aarti Dhapte Last Updated: October 15, 2026
Smart Home Installation Service Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)22.7%
2025 Market SizeUSD 9.62 Billion
2035 Market SizeUSD 74.66 Billion
Key Players
ADT Inc.
Vivint
Best Buy
Comcast
Amazon
Resideo Technologies
Opportunities
  • Urban Housing Growth in Emerging Markets
  • Energy Data and Grid-Service Business Models
  • Multi-Unit Retrofit Programs

Smart Home Installation Service Market Summary

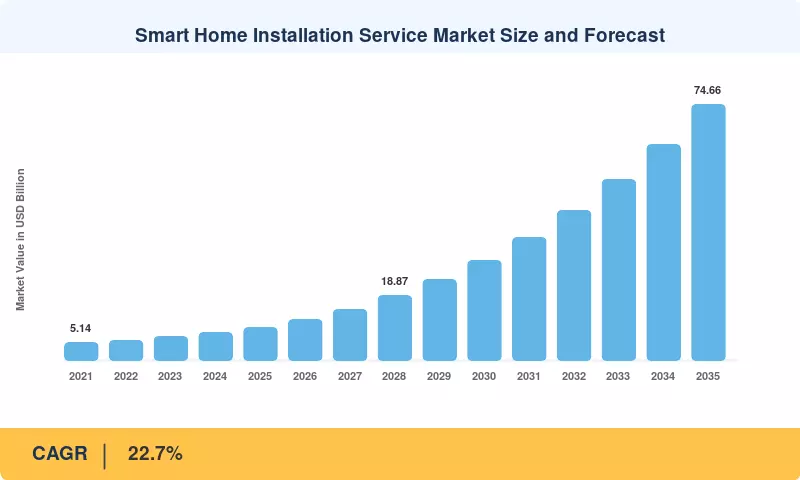
The Smart Home Installation Service Market was valued at USD 9.62 Billion in 2025 and is projected to reach USD 11.84 Billion in 2026, climbing to USD 74.66 Billion by 2035 at a CAGR of 22.7% over 2026–2035. Two catalysts anchor this trajectory. The U.S. Department of Energy's USD 8.8 billion Home Energy Rebates programs reward households for installing efficient, controllable equipment [3], and the Connectivity Standards Alliance's Matter standard gives installers a single commissioning workflow across competing brands [1]. Demand is moving away from one-off device mounting toward whole-home design, programming, and recurring service contracts.

Legacy hardwired alarm panels, standalone programmable thermostats, and proprietary hubs are giving way to IP-based, app-managed systems built on Wi-Fi, Thread, and Matter. Matter 1.4, released in November 2024, extended the standard to heat pumps, solar inverters, and home batteries [2], drawing installers into energy-management work that previously belonged to electricians and HVAC contractors. ENERGY STAR-certified smart thermostats save households roughly 8% on heating and cooling costs [4], a payback argument installers now use at the point of sale.

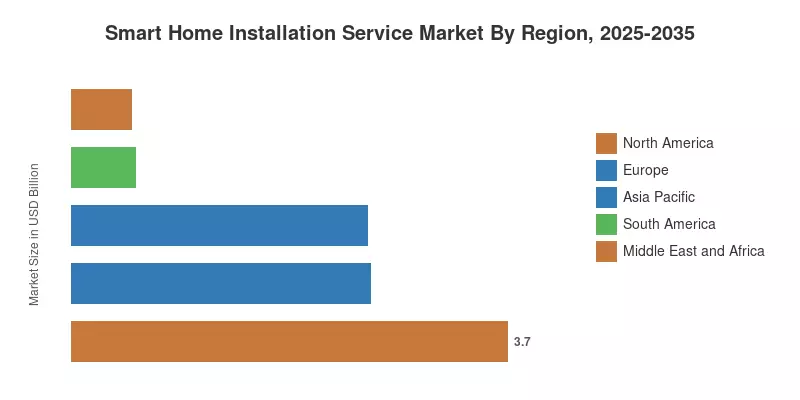
North America leads with a 38.5% share in 2025, supported by high security-monitoring penetration and dense big-box installation networks. Asia Pacific is the fastest-growing region at a 26.1% CAGR, led by urban apartment construction in China and India. Europe ranks second with revenue of USD 2.54 billion, as the recast Energy Performance of Buildings Directive pushes building automation into renovation work [5]. Over the next decade, the Smart Home Installation Service Market will reward providers that bundle installation with monitoring, energy optimization, and remote support.

Key Report Takeaways

• By System

  • Home Monitoring/Security held 42.6% of the Smart Home Installation Service Market in 2025, serving as the entry point for most multi-device projects
  • Smart Appliances is the fastest-growing system category at a 24.3% CAGR, as Matter-certified kitchen and laundry equipment requires professional commissioning

• By Channel

  • Retailers captured 48.0% share in 2025, converting in-store demonstrations into same-day installation bookings
  • E-Commerce is expanding at a 23.1% CAGR on the strength of one-click installation add-ons at checkout

• By Installation Type

  • Professional-Installed services generated 65.6% of Smart Home Installation Service Market revenue in 2025, reflecting buyer reluctance to handle wiring and multi-vendor integration
  • Do-It-Yourself (DIY) is advancing at a 26.6% CAGR, driven by QR-code onboarding and adhesive-mount hardware

• By Customer Type

  • Residential customers accounted for a 77.9% share in 2025
  • Commercial/Small Business is growing at a 24.8% CAGR as retailers, clinics, and offices adopt access control and energy monitoring

• By Dwelling Type

  • Single-Family Homes represented a 58.4% share in 2025
  • Multi-Unit Dwellings are expanding at a 25.4% CAGR as landlords standardize building-wide platforms

• By Connectivity Standard

  • Wi-Fi held a 46.3% share in 2025 as the default transport for cameras and video doorbells
  • Thread is the fastest-growing standard at a 27.9% CAGR, propelled by Matter certification

• By Region

  • North America led the Smart Home Installation Service Market with a 38.5% share in 2025
  • Asia Pacific is projected to grow at a 26.1% CAGR through 2035
  • Europe generated USD 2.54 billion in 2025

Market Size and Forecast (2021–2035)

Estimates for the Smart Home Installation Service Market combine bottom-up modeling of installation visits, average labor tickets, and attached service subscriptions with top-down validation against vendor filings, retailer service disclosures, and housing data [13][15][16][18]. Historical values reflect reported revenue from security integrators, retail service desks, and independent home automation installation firms, while forecasts incorporate device shipment outlooks, rebate disbursement schedules, and protocol adoption curves. Spike years correspond to standard releases and regulatory milestones that changed how quickly households bought professionally commissioned systems.
Smart Home Installation Service Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Matter and Thread interoperability adoption ~+4.1% Global Medium term (2–4 yrs)
Bundled security monitoring and insurance incentives ~+3.6% North America, Europe Short term (≤2 yrs)
Energy-efficiency rebates and building directives ~+3.2% North America, Europe Medium term (2–4 yrs)
Connected appliance commissioning ~+2.9% Global Medium term (2–4 yrs)
Aging-in-place and remote care demand ~+2.4% North America, Europe, Japan Long term (≥4 yrs)
Builder-integrated packages in new construction ~+2.2% North America, Asia Pacific Long term (≥4 yrs)
Retail and online bundled installation offers ~+2.0% Global Short term (≤2 yrs)

Matter and Thread Interoperability Adoption

Matter removed the biggest cost in multi-brand projects: separate apps and pairing routines for every device family. Version 1.2, published in October 2023, added nine device types including refrigerators, dishwashers, laundry washers, and room air conditioners [1]. Installers can now onboard a lock, a thermostat, and a washer through one controller, cutting site time and post-visit support calls. Thread border routers built into mainstream hubs give technicians a self-healing mesh that tolerates dense housing better than legacy radios.

Bundled Security Monitoring and Insurance Incentives

Security remains the most reliable on-ramp for professional installation because monitoring contracts finance the labor. ADT serves more than six million monitored customers and reports recurring monthly revenue as its core performance metric [15], an economic model that subsidizes upfront installation. Home insurers commonly discount premiums by 5–20% for professionally monitored intrusion, fire, and water-leak systems. That discount shortens payback periods and keeps security installs resilient even when discretionary spending softens.

Energy-Efficiency Rebates and Building Directives

Public money is steering households toward controllable equipment that needs correct configuration. The U.S. Inflation Reduction Act allocated USD 8.8 billion to Home Energy Rebates, with electrification rebates of up to USD 14,000 per qualifying household [3]. In Europe, the recast EPBD requires building automation and control systems in non-residential buildings with HVAC systems above 290 kW, with the threshold falling to 70 kW by 2029 [5]. Both regimes reward documented, professionally commissioned installations over self-installed devices.

Connected Appliance Commissioning

Wi-Fi and Thread radios are now standard on mid- and high-end versions from appliance manufacturers. According to Parks Associates, around 45% of internet-connected households in the United States have at least one smart home gadget [17], but without setup, appliance connectivity is frequently useless. Commissioning, firmware management, and warranty registration are increasingly offered as paid add-ons by retailers and manufacturers. As homes subsequently connect appliances to utility programs or energy dashboards, each connected appliance also generates an incentive to return.

Aging-in-Place and Remote Care Demand

Demographics favor sensor-based safety systems installed by professionals. AARP research finds that 77% of U.S. adults aged 50 and older want to remain in their current homes as they age [9]. Fall detection, medication reminders, smart lighting, and door sensors require careful placement and caregiver app configuration, tasks families rarely attempt themselves. Japan and Western Europe show similar patterns, and long-term care insurers have begun piloting reimbursement for monitored home sensors.

Builder-Integrated Packages in New Construction

Homebuilders use pre-wired smart packages to differentiate inventory and lift sale prices. U.S. housing starts reached about 1.37 million units in 2024 [18], and national builders increasingly include smart locks, thermostats, and video doorbells as standard features commissioned before handover. In Asia Pacific, India's Smart Cities Mission has funded integrated urban infrastructure across 100 cities [19], encouraging developers to market connected apartments. Builder contracts give installers predictable, high-volume work at lower acquisition cost.

Retail and Online Bundled Installation Offers

Large retailers convert device sales into service revenue at checkout. Best Buy reported fiscal 2025 revenue of about USD 41.5 billion and positions in-home installation and its Geek Squad membership as core to customer retention [16]. Online marketplaces now attach fixed-price installation to device listings, giving buyers a transparent quote before purchase. This packaging reduces the friction of finding a qualified technician and lifts attach rates for professional services on mid-priced devices.

Restraints Impact Analysis

Restraint weightings show the directional drag each factor places on the Smart Home Installation Service Market growth rate. Like driver impacts, they overlap and are not additive.

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
Shortage of skilled low-voltage technicians ~−2.1% Global Medium term (2–4 yrs)
Data privacy and cybersecurity compliance costs ~−1.6% Europe, North America Short term (≤2 yrs)
Upfront cost sensitivity in emerging economies ~−1.4% Asia Pacific, South America, Middle East and Africa Long term (≥4 yrs)
Legacy protocol fragmentation ~−1.2% Global Short term (≤2 yrs)
Marketplace commission and DIY price pressure ~−0.9% North America, Europe Medium term (2–4 yrs)

Shortage of Skilled Low-Voltage Technicians

The most stringent restriction on project throughput is labor supply. According to the U.S. Bureau of Labor Statistics, employment for electricians is expected to increase by 11% between 2023 and 2033, with roughly 80,200 positions annually [10]. Smart home providers compete with solar, EV charger, and data center builders for the same personnel. Longer lead times limit revenue growth for businesses that are unable to hire quickly enough and drive some buyers toward do-it-yourself kits.

Data Privacy and Cybersecurity Compliance Costs

Security rules raise the cost of compliant installations. The UK's PSTI regime, in force since April 2024, bans universal default passwords on connectable products [7]. The EU Cyber Resilience Act entered into force in December 2024, with reporting obligations from September 2026 and full application in December 2027 [8]. Installers must document configurations, manage firmware updates, and train staff, adding overhead that smaller firms struggle to absorb.

Upfront Cost Sensitivity in Emerging Economies

Price remains a barrier outside wealthy urban households. In much of South America, Africa, and Southeast Asia, a professionally installed multi-device package can equal several weeks of median household income. Buyers often purchase a single camera or smart plug and skip paid setup altogether. Saudi Arabia's Vision 2030 housing program targets 70% homeownership by 2030 [20], yet affordability programs focus on structure rather than connected upgrades.

Legacy Protocol Fragmentation

Millions of homes still run Zigbee and Z-Wave security panels alongside newer Wi-Fi and Thread devices. Bridging these ecosystems requires multi-protocol hubs and technician expertise across several standards, which lengthens site visits [1]. Some legacy devices cannot be updated to Matter, forcing a choice between stranding the investment or paying for replacement. That uncertainty delays upgrade decisions in the installed base.

Marketplace Commission and DIY Price Pressure

Although they deliver project volume, digital aggregators usually keep 15–25% of the installation price, which reduces installer margins. Concurrently, households are encouraged to self-install entry-level devices due to declining hardware costs and better app onboarding [17]. Providers must provide design, network optimization, and support guarantees that DIY buyers cannot match in order to defend labor costs.

Smart Home Installation Service Market Opportunities

Urban Housing Growth in Emerging Markets

Rapid apartment construction in India, Saudi Arabia, and Brazil creates a large pool of first-time smart home buyers. Developers in these markets favor turnkey, builder-installed packages that keep per-unit costs low through volume contracting [19][20]. Providers that partner with developers early can establish service relationships worth years of subscription revenue, positioning the Smart Home Installation Service Market for share gains outside North America.

Energy Data and Grid-Service Business Models

Connected thermostats, water heaters, batteries, and EV chargers turn homes into flexible grid assets. The IEA identifies demand-side flexibility as essential to integrating variable renewables [12]. Installers can enroll customers in utility demand-response programs, share performance data with consent, and earn recurring fees or revenue shares tied to verified load reduction. This model converts a one-time visit into an annuity.

Multi-Unit Retrofit Programs

Landlords and property managers are standardizing access control, leak detection, and thermostats across portfolios to cut operating costs and attract tenants. Building-wide deployments create demand for professional smart home integration across hundreds of units under a single contract, with predictable scheduling during unit turnover [18]. Retrofit work also generates long-term maintenance agreements.

Managed Aging-in-Place Services

Families and care providers increasingly pay for monitored sensor packages that support independent living [9]. Installers can bundle fall-detection sensors, smart lighting, and caregiver dashboards into a monthly subscription that includes battery replacement and annual checkups. Partnerships with home-care agencies and insurers offer a referral channel with lower acquisition cost than consumer advertising.

Commercial and Small Business Fit-Outs

Small retailers, clinics, and offices want access control, video surveillance, and energy monitoring without enterprise-scale integrator pricing. Residential installers already hold the skills and device relationships to serve this segment at competitive rates [5]. Packaged commercial tiers with service-level guarantees can lift average ticket sizes meaningfully.

Smart Home Installation Service Market Future Outlook

AI-Assisted Diagnostics and Remote Commissioning

Artificial intelligence will shift a growing share of installation work off-site. Controllers that self-report signal strength, battery health, and configuration errors let technicians fix faults remotely, reducing repeat truck rolls. Vision-based tools that guide customers through mounting while a technician completes programming over video will make hybrid service tiers mainstream by the early 2030s, though broadband gaps will limit adoption in rural areas.

Grid-Interactive Homes and Energy Management

Buildings account for roughly 30% of global final energy consumption, according to the IEA [11], making homes a major lever for decarbonization. As heat pumps, rooftop solar, home batteries, and EV chargers spread, households will need professionals to coordinate these assets through a single energy manager. Matter 1.4 support for energy devices [2] gives installers a standards-based path into this work, and utility programs will increasingly fund it.

Subscription Platforms and Recurring Revenue

Installation economics will resemble telecom more than contracting. Contracts that waive or reduce upfront labor in exchange for multi-year monitoring, maintenance, and support plans are becoming more common among top providers in the smart home installation services market [15]. In addition to improving valuations and client lifetime value, recurring revenue provides suppliers with an incentive to maintain systems rather than abandon customers after their initial visit.

Security Labeling and Trust as Differentiators

Cybersecurity credentials will become a selling point rather than a compliance chore. The FCC's Cyber Trust Mark [6], the UK PSTI regime [7], and the EU Cyber Resilience Act [8] create clear baselines that informed buyers can check. Installers that document secure configurations, manage firmware lifecycles, and offer breach-response support will win landlords, insurers, and commercial clients who carry liability for connected devices.

Regional Market Share Analysis

Region Key Metric (2025) Primary Investment Themes
North America 38.5% share Monitored security, energy rebates, builder packages
South America 5.6% share Urban security demand, retail-led installations
Europe USD 2.54 Billion EPBD renovation, heat pump controls, cybersecurity compliance
Asia Pacific 26.1% CAGR Connected apartments, smart city programs, appliance connectivity
Middle East and Africa USD 0.51 Billion Luxury villas, giga-projects, urban security
Total USD 9.62 Billion —

Regional performance in the Smart Home Installation Service Market tracks security-monitoring culture, housing construction rates, and public energy incentives. North America remains the revenue anchor, Europe is shaped by building and cybersecurity regulation, and Asia Pacific contributes the strongest growth on the back of urban apartment development.

North America

Country Key Metric (2025) Key Driver
United States 81.4% share of region Monitored security bundles and rebate-funded thermostats
Canada USD 0.41 Billion Heating-efficiency programs and new condominium supply
Mexico 24.9% CAGR Urban security demand and retail installation expansion

The United States dominates regional revenue through dense networks of security dealers, retail installation desks, and builder partnerships. Federal Home Energy Rebates and state programs reward smart thermostats and heat pump controls [3], while the FCC's Cyber Trust Mark gives installers a recognizable security credential for recommended devices [6]. Canada follows with growth tied to winter energy savings, and Mexico benefits from rising middle-class security spending in major metros.

South America

Country Key Metric (2025) Key Driver
Brazil 54.2% share of region Condominium security and telecom-bundled installs
Argentina 21.6% CAGR Urban security upgrades and hardware import recovery
Rest of South America USD 0.13 Billion Chile and Colombia apartment construction

Brazil accounts for most regional spending, led by video surveillance and access control in São Paulo and Rio de Janeiro apartment buildings. Retail chains and telecom operators bundle installation with broadband subscriptions to reach price-sensitive households. Argentina's growth reflects pent-up demand in Buenos Aires, although currency volatility complicates imported hardware pricing.

Europe

Country Key Metric (2025) Key Driver
Germany USD 0.62 Billion Heat pump controls and building renovation subsidies
United Kingdom 21.8% share of region Security installs and smart meter integration
France 20.4% CAGR Energy renovation incentives for older housing
Italy USD 0.27 Billion Building renovation tax credits and cooling control
Spain 22.1% CAGR Multi-unit retrofits and solar self-consumption
Rest of Europe 23.5% share of region Nordic heating automation and Benelux renovation

European demand is regulation-led. The recast EPBD pushes building automation into renovation and new construction [5], while the UK PSTI regime and the EU Cyber Resilience Act raise the bar for compliant device configuration [7][8]. Germany leads on heating controls tied to heat pump adoption, the United Kingdom on security and smart meters, and southern markets on cooling management and multi-unit retrofits.

Asia Pacific

Country Key Metric (2025) Key Driver
China 39.6% share of region Developer-installed connected apartments
Japan USD 0.48 Billion Aging-in-place monitoring and energy management
India 31.2% CAGR Smart city projects and premium residential towers
South Korea 11.4% share of region Apartment-wide platforms from construction groups
Rest of Asia Pacific 25.3% CAGR Australian retrofits and Southeast Asian condominiums

China leads on volume, where developers ship connected apartments with pre-installed hubs and appliance ecosystems. India posts the fastest country-level growth as smart city programs and premium residential towers adopt integrated access control and lighting [19]. Japan's aging population supports monitoring and safety installations, while South Korea's apartment-centric housing favors builder-commissioned platforms.

Middle East and Africa

Country Key Metric (2025) Key Driver
Middle East 62.5% share of region Luxury residential and mixed-use developments
Saudi Arabia 27.4% CAGR Vision 2030 housing and giga-project construction
United Arab Emirates USD 0.11 Billion Branded residences and villa automation
Turkey 18.2% share of region Urban apartment construction and security demand
Rest of Middle East USD 0.04 Billion Qatar and Kuwait premium housing
Africa 37.5% share of region Urban security and estate developments
South Africa USD 0.09 Billion Security-led installs and load-shedding resilience
Nigeria 26.8% CAGR Gated estates in Lagos and Abuja
Kenya 25.9% CAGR Nairobi apartment growth and mobile-first platforms
Rest of Africa USD 0.03 Billion North African urban housing

The Middle East accounts for most regional spending, led by luxury villas, branded residences, and giga-projects in Saudi Arabia and the United Arab Emirates. Saudi Arabia's Vision 2030 housing program is expanding the new-build pipeline [20]. In Africa, South Africa leads on security-driven installations, while Nigeria and Kenya show early growth in urban estates with backup-power and surveillance integration.

Smart Home Installation Service Market By Region, 2025-2035

Smart Home Installation Service Market Segmentation

By System

Within the Smart Home Installation Service Market, Home Monitoring/Security leads because monitoring contracts finance installation labor and create the first foothold in a household. Smart Appliances grows fastest as Matter-certified refrigerators, ovens, and washers require commissioning and warranty registration. Lighting Control and Thermostat installs ride energy incentives, Video Entertainment serves premium media rooms, and Other Systems such as leak detection and window shades fill out whole-home projects.

Segment Key Metric (2025) Primary Demand Driver
Lighting Control USD 1.31 Billion Scene programming and energy savings
Home Monitoring/Security 42.6% share Crime concerns and monitoring contracts
Thermostat 21.4% CAGR Utility rebates and heat pump controls
Video Entertainment 11.2% share Premium media rooms and whole-home audio
Smart Appliances 24.3% CAGR Matter-certified kitchen and laundry equipment
Other Systems USD 0.48 Billion Leak detection, shades, and access control

By Channel

Across the Smart Home Installation Service Market, Retailers hold the largest share because in-store advisors and live demonstrations convert shoppers into scheduled installations. E-Commerce expands fastest as marketplaces attach fixed-price installation to device listings and guarantee arrival windows. Original Equipment Manufacturer (OEM) channels, dominated by vertically integrated security and appliance brands, capture margin from hardware through ongoing monitoring.

Segment Key Metric (2025) Primary Demand Driver
Retailers 48.0% share In-store demonstrations and financing
E-Commerce 23.1% CAGR Transparent pricing and checkout bundling
Original Equipment Manufacturer (OEM) USD 2.12 Billion Vertically integrated security and appliance offers

By Installation Type

For the Smart Home Installation Service Market, Professional-Installed services dominate because structured wiring, exterior drilling, and multi-vendor integration exceed most homeowners' skills. Do-It-Yourself (DIY) grows faster as QR-code onboarding and video tutorials lower barriers for entry-level devices. Many households start with a DIY doorbell or plug and later hire professionals for whole-home projects, so the two tiers feed each other.

Segment Key Metric (2025) Primary Demand Driver
Professional-Installed 65.6% share Complex wiring and multi-system integration
Do-It-Yourself (DIY) 26.6% CAGR Simplified app onboarding and low hardware prices

By Customer Type

Inside the Smart Home Installation Service Market, Residential customers generate the bulk of revenue, motivated by safety, energy savings, and voice-assistant convenience. Commercial/Small Business accounts grow faster as shops, clinics, and offices adopt access control, surveillance, and energy monitoring at prices below enterprise integrators. Residential installers with commercial tiers capture larger tickets and service-level agreements.

Segment Key Metric (2025) Primary Demand Driver
Residential 77.9% share Safety, comfort, and energy savings
Commercial/Small Business 24.8% CAGR Access control and energy monitoring

By Dwelling Type

In the Smart Home Installation Service Market, Single-Family Homes lead because owners control their property and invest in whole-home systems. Multi-Unit Dwellings grow fastest as landlords standardize building-wide hubs, keyless entry, and leak detection. New-Build Constructions benefit from builder pre-wiring, while Retrofit Projects remain a large revenue pool as aging housing stock is upgraded room by room.

Segment Key Metric (2025) Primary Demand Driver
Single-Family Homes 58.4% share Owner investment in whole-home systems
Multi-Unit Dwellings 25.4% CAGR Portfolio-wide landlord deployments
New-Build Constructions 21.3% CAGR Builder-installed smart packages
Retrofit Projects USD 3.18 Billion Upgrades to aging housing stock

By Connectivity Standard

For connectivity, the Smart Home Installation Service Market relies most heavily on Wi-Fi, the default transport for cameras, doorbells, and streaming devices. Thread grows fastest because Matter certification and built-in border routers simplify low-power mesh networks. Zigbee and Z-Wave persist in installed security panels, while Bluetooth Mesh gains ground in lighting fixtures and locks.

Segment Key Metric (2025) Primary Demand Driver
Wi-Fi 46.3% share Cameras, doorbells, and high-bandwidth devices
Zigbee USD 1.73 Billion Installed lighting and sensor ecosystems
Z-Wave 13.8% share Legacy security panels and locks
Thread 27.9% CAGR Matter certification and border-router hubs
Bluetooth Mesh 19.6% CAGR Lighting fixtures and smart locks

Competitive Benchmarking

The Smart Home Installation Service Market is moderately fragmented, with an estimated HHI of roughly 650–850 and the top five providers holding about 36–40% of revenue. National security firms, big-box retailers, cable operators, and e-commerce platforms compete alongside thousands of regional integrators and independent technicians. Scale advantages come from monitoring revenue, retail foot traffic, and technician networks, while local firms compete on design expertise and response times.

Company Est. Revenue Share Range Key Offerings for Smart Home Installation Service Market Strategic Positioning
ADT Inc. ~11–14% Professionally installed security, ADT+ platform, monitoring Monitoring-led recurring revenue with insurer partnerships
Vivint (NRG Energy) ~8–11% Whole-home security and automation with in-house technicians Energy-integrated home services under NRG
Best Buy (Geek Squad) ~6–9% In-home installation, memberships, device setup Retail-attached services with national reach
Comcast (Xfinity Home) ~4–6% Security and automation bundled with broadband Connectivity-bundled subscription model
Amazon ~3–5% Installation services attached to device purchases, Ring and Alexa ecosystem E-commerce checkout bundling and device ecosystem
Resideo Technologies ~3–5% First Alert, Honeywell Home, ADI distribution, Snap One integration platforms Distribution and professional channel scale
Asurion ~2–4% Tech support and in-home setup for carriers and retailers White-label service partner model
HelloTech ~1–3% On-demand smart home installation marketplace Gig-technician network for retail partners
Angi ~1–3% Fixed-price installation booking through Angi and Handy Marketplace lead generation for independent pros
Brinks Home ~1–2% DIY and professionally installed monitored security Flexible installation tiers for value buyers
Vector Security ~1–2% Residential and commercial security integration Regional dealer network with commercial reach

Recent News & Developments

  • NRG Energy (March 2023): Completed its acquisition of Vivint Smart Home, combining retail energy with home automation and giving installers a path to sell energy-management services alongside security [13]
  • Connectivity Standards Alliance (October 2023): Released Matter 1.2, adding refrigerators, dishwashers, laundry washers, and other appliance types, which expanded the commissioning workload for installers [1]
  • Resideo Technologies (June 2024): Completed its acquisition of Snap One, strengthening its professional integrator channel and distribution reach [14]
  • Connectivity Standards Alliance (November 2024): Released Matter 1.4 with support for heat pumps, solar inverters, batteries, and EV chargers, opening energy-management work to installers [2]
  • Federal Communications Commission (January 2025): Launched the U.S. Cyber Trust Mark program, giving buyers and installers a recognizable label for devices meeting baseline security criteria [6]

Smart Home Installation Service Market Report Scope

Parameter Details
Market Scope Professional and DIY installation, configuration, and support services for smart home systems sold through retailers, e-commerce, and OEM channels to residential and commercial/small business customers
Study Period 2021–2035
Base Year 2025
Historical Data 2021–2024
Forecast Period 2026–2035
Market Size in 2025 USD 9.62 Billion
Market Size in 2035 USD 74.66 Billion
CAGR (2026–2035) 22.7%
Fastest Growing Segments Thread (27.9% CAGR); Do-It-Yourself (DIY) (26.6% CAGR); Commercial/Small Business (24.8% CAGR); Smart Appliances (24.3% CAGR)
Regions Covered North America, Europe, South America, Asia Pacific, Middle East and Africa and ROW
Companies Profiled ADT Inc., Vivint (NRG Energy), Best Buy (Geek Squad), Comcast (Xfinity Home), Amazon, Resideo Technologies, Asurion, HelloTech, Angi, Brinks Home, Vector Security
Valuation Currency USD Billion
Methodology 350+ primary expert interviews; bottom-up market sizing; top-down validation; data triangulation; scenario-based forecasting; real-time project tracking

FAQs

How should homeowners evaluate a provider in the Smart Home Installation Service Market?
Check licensing for low-voltage and electrical work, Matter training, and written post-installation support terms. Providers offering remote diagnostics usually resolve faults without a second visit, lowering lifetime ownership cost [10].
Does a Cyber Trust Mark label change installation decisions?
Yes. Labeled devices meet baseline security criteria, so installers can document compliance for insurers and landlords with less custom testing [6].
Which contract model is gaining favor in the Smart Home Installation Service Market?
Contracts that waive upfront labor in exchange for 36- to 60-month monitoring or maintenance subscriptions are spreading. They turn installation into recurring revenue and improve provider valuations [15].
How do landlords approach smart retrofits in rental buildings?
Landlords favor building-wide hubs, keyless entry, and leak sensors installed during unit turnover. Scheduling work between tenancies avoids access disputes and lets owners recover costs through amenity fees [18].
What integration issue most often delays projects in the Smart Home Installation Service Market?
Weak Wi-Fi coverage is the leading cause of failed commissioning. Many installers now run a site survey and add mesh access points or a Thread border router before mounting devices [1].
Are utilities becoming buyers of installation services?
Increasingly, yes. Utilities are adding demand to the Smart Home Installation Service Market by paying installers to enroll and configure thermostats and water heaters, since connected loads earn grid-flexibility value [12].
What skills will installers need most by 2030?
Network engineering, cybersecurity hardening, and energy-device commissioning will matter more than basic mounting. Technicians certified on heat pumps, batteries, and Matter controllers can command premium labor rates [2].
Author
Author Author Profile Ankit Gupta LinkedIn Team Lead - Research
Ankit Gupta is a seasoned market intelligence and strategic research professional with over six plus years of experience in the ICT and Semiconductor industries. With academic roots in Telecom, Marketing, and Electronics, he blends technical insight with business strategy. Ankit has led 200+ projects, including work for Fortune 500 clients like Microsoft and Rio Tinto, covering market sizing, tech forecasting, and go-to-market strategies. Known for bridging engineering and enterprise decision-making, his insights support growth, innovation, and investment planning across diverse technology markets.
Co-Author Co-Author Profile Aarti Dhapte LinkedIn AVP - Research
A consulting professional focused on helping businesses navigate complex markets through structured research and strategic insights. I partner with clients to solve high-impact business problems across market entry strategy, competitive intelligence, and opportunity assessment. Over the course of my experience, I have led and contributed to 100+ market research and consulting engagements, delivering insights across multiple industries and geographies, and supporting strategic decisions linked to $500M+ market opportunities. My core expertise lies in building robust market sizing, forecasting, and commercial models (top-down and bottom-up), alongside deep-dive competitive and industry analysis. I have played a key role in shaping go-to-market strategies, investment cases, and growth roadmaps, enabling clients to make confident, data-backed decisions in dynamic markets.
Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.



















