Remote Tank Monitoring System Market (2026 - 2035)

Remote Tank Monitoring System Market Size, Share and Research Report By Monitoring Type (Point-Level Monitoring, Continuous-Level Monitoring), By Technology (Contact Sensors, Non-Contact Sensors), By Connectivity (Cellular (4G LTE, 5G, NB-IoT, Cat-M), LPWAN (LoRaWAN, Sigfox), Satellite (LEO / GEO), Short-Range RF / Wi-Fi / BLE), By Tank Type (Above-Ground Fixed-Roof, Above-Ground Floating-Roof, Underground / UST), By End-User Industry (Oil and Gas, Chemicals and Petrochemicals, Water and Wastewater, Food and Beverage, Agriculture and Irrigation, Power Generation, Mining and Metals, Pharmaceuticals and Healthcare), By Service Model (Stand-alone Hardware Sales, Hardware-as-a-Service (HaaS) Subscription, Fully Managed Turnkey Platforms) and By Regional (North America, Europe, South America, Asia Pacific, Middle East and Africa) - Industry Forecast to 2035.
ID: MRFR/ICT/30034-HCR 100 Pages Nirmit Biswas, Aarti Dhapte Last Updated: October 14, 2026
Remote Tank Monitoring System Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)21.8%
2025 Market SizeUSD 2.83 Billion
2035 Market SizeUSD 20.17 Billion
Key Players
Emerson Electric Co.
Schneider Electric SE
Honeywell International Inc.
Endress+Hauser Group
VEGA Grieshaber KG
Dover Corporation
Opportunities
  • Rural Water and Agriculture in Emerging Economies
  • Data Monetization and Subscription Business Models
  • Methane Measurement and Reporting Services

Remote Tank Monitoring System Market Summary

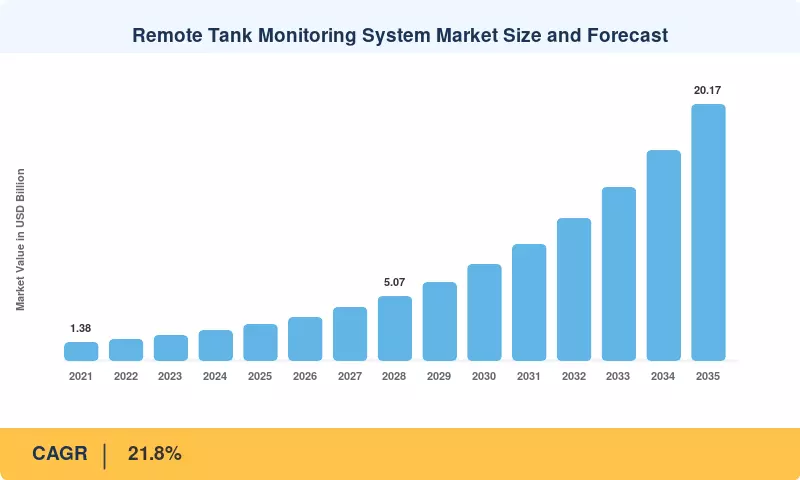
The Remote Tank Monitoring System Market was valued at USD 2.83 Billion in 2025 and is forecast to reach USD 3.42 Billion in 2026, climbing to USD 20.17 Billion by 2035 at a CAGR of 21.8% during 2026–2035. Two policy catalysts anchor that trajectory. The U.S. EPA's final methane standards for oil and gas sources (OOOOb/c) raised monitoring expectations for storage vessels [2]. The EU Methane Regulation, in force since August 2024, adds leak detection, measurement and reporting duties across the oil and gas chain [3].

Technology is shifting just as quickly. Manual dipsticks, sight glasses and wired float gauges read during site visits are giving way to battery-powered radar and ultrasonic sensors that report over cellular, LPWAN or satellite links to cloud dashboards. This move from periodic manual readings to wireless tank gauging matters at scale: the IEA estimates the oil and gas sector still releases roughly 120 million tonnes of methane a year, a meaningful portion from venting and leaking storage infrastructure [6].

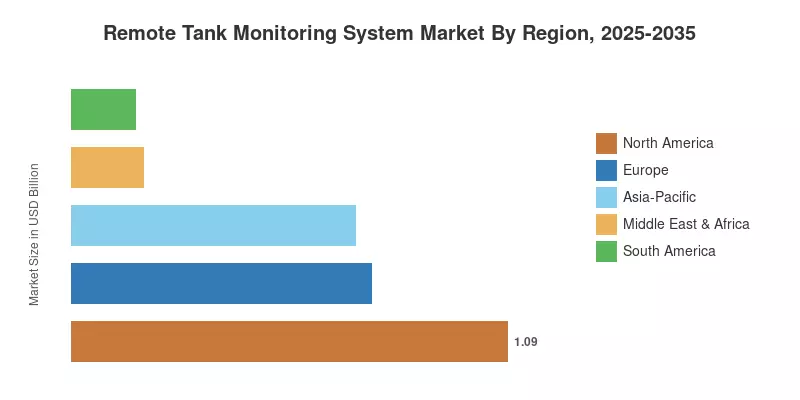
North America is the dominant region with a 38.6% share in 2025, supported by federal spill-prevention rules and a dense network of propane, fuel and lubricant distributors. Asia-Pacific is the fastest-growing region at a 25.1% CAGR, led by rural water programs in India and chemical-park safety mandates in China. Europe ranks second, driven by methane and industrial-emissions compliance. Over the next decade, recurring software and connectivity revenue will account for a steadily larger slice of vendor income.

Key Report Takeaways

The Remote Tank Monitoring System Market divides along six product and buyer dimensions plus geography. Each bullet below carries one headline metric, and every figure ties back to the detailed analysis in later sections.

• By Monitoring Type

  • Continuous-Level Monitoring holds 63.2% of Remote Tank Monitoring System Market revenue in 2025, as regulators favor uninterrupted level tracking over threshold alarms.
  • Point-Level Monitoring generated USD 1.04 Billion in 2025, serving low-value and non-hazardous liquids where budget drives the purchase.

• By Technology

  • Non-Contact Sensors account for 60.6% of 2025 revenue, led by 80 GHz radar in corrosive and high-temperature service.
  • Contact Sensors expand at a 22.0% CAGR through 2035 on custody-transfer replacement cycles.

• By Connectivity

  • Cellular (4G LTE, 5G, NB-IoT, Cat-M) carries 49.3% of 2025 revenue on the back of low-cost modules and data plans.
  • Satellite (LEO / GEO) is the fastest-growing link type at a 22.4% CAGR.

• By Tank Type

  • Above-Ground Fixed-Roof tanks represent a 45.8% share of 2025 revenue.
  • Above-Ground Floating-Roof installations grow at a 22.1% CAGR as overfill and methane audits tighten.

• By End-User Industry

  • Oil and Gas leads the Remote Tank Monitoring System Market with a 30.4% share in 2025.
  • Agriculture and Irrigation posts the fastest growth at a 22.5% CAGR.

• By Service Model

  • Stand-alone Hardware Sales retain a 55.6% share of 2025 revenue.
  • Hardware-as-a-Service (HaaS) Subscription grows at a 22.2% CAGR as distributors shift spending to opex.

• By Region

  • North America leads with a 38.6% share in 2025.
  • Asia-Pacific expands fastest at a 25.1% CAGR.
  • Europe generated USD 0.75 Billion in 2025.

Market Size and Forecast (2021–2035)

Market Research Future sized the Remote Tank Monitoring System Market by combining shipment estimates for level sensors and gateways, installed-base counts from distributor and operator interviews, and subscription revenue disclosed in vendor filings. Historical values were reconciled against regulatory inventories such as EPA's underground storage tank counts [9] and EIA storage-capacity surveys [8]. Growth runs steadily above 19% across the series; the step-up from 2025 to 2026 reflects methane-rule compliance dates rather than a one-off spike, and no anomalous year appears in the forecast.
Remote Tank Monitoring System Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Methane and emissions regulation ~+4.1% North America, Europe Medium-term (2–4 yr)
Spill-prevention and overfill compliance ~+3.6% North America, global terminals Short-term (≤2 yr)
Falling cellular and LPWAN connectivity costs ~+3.2% Global Short-term (≤2 yr)
Distributor logistics and vendor-managed inventory ~+2.9% North America, Europe, Asia-Pacific Medium-term (2–4 yr)
Water scarcity and precision agriculture programs ~+2.4% Asia-Pacific, Middle East & Africa Long-term (≥4 yr)
LEO satellite coverage for off-grid assets ~+2.0% South America, Middle East & Africa, Australia Long-term (≥4 yr)

Methane and Emissions Regulation

Methane rules are turning tank monitoring from an operational convenience into a compliance requirement. EPA projects that its OOOOb/c standards, finalized in December 2023, will avoid about 58 million tons of methane between 2024 and 2038, with storage vessels among the covered sources [2]. The EU Methane Regulation adds mandatory leak surveys and measurement-based reporting [3]. Operators now pair continuous level data with pressure readings to flag thief-hatch and vent anomalies that drive storage emissions.

Spill-Prevention and Overfill Compliance

EPA's SPCC rule applies to facilities storing more than 1,320 gallons of oil above ground, requiring overfill prevention and documented inspections [1]. API Standard 2350 sets the overfill-management framework that terminal operators reference in insurance and audit reviews [5]. Below ground, EPA counts roughly 540,000 active underground storage tanks at nearly 200,000 sites, each subject to release-detection rules [9]. Remote level data gives owners a timestamped compliance record in place of handwritten logs.

Falling Connectivity Costs

Low-power cellular has made per-tank connectivity affordable. Ericsson reports cellular IoT connections passed 3 billion in 2023 and continue to grow as NB-IoT and LTE-M networks mature [10]. GSMA data show module prices sliding toward single-digit dollars in volume [11], while the LoRa Alliance counts more than 350 million LoRaWAN end devices deployed [12]. Cheaper links let distributors justify sensors on small residential and farm tanks that were previously uneconomic.

Distributor Logistics and Vendor-Managed Inventory

Fuel, propane, lubricant and chemical distributors are the most consistent buyers because remote readings convert will-call and fixed-route deliveries into demand-driven dispatch. Industry case studies cited in Dover's reporting point to 20–30% fewer truck rolls once tank levels feed routing software [21]. Fewer partial deliveries lift drop size, lower driver overtime and reduce run-out callouts. Distributors facing driver shortages treat sensors as a labor-substitution investment rather than an IT expense.

Water Scarcity and Precision Agriculture

Water stress is pushing utilities and farms toward metered, monitored storage. The World Bank estimates water scarcity could cost some regions up to 6% of GDP by 2050 [13]. India's Jal Jeevan Mission, with a total outlay of about INR 3.6 lakh crore, funds village water tanks that increasingly carry level sensors [14]. In the U.S., USDA's EQIP program co-funds irrigation and nutrient-management upgrades that include tank telemetry for fertilizer and water storage [15].

LEO Satellite Coverage for Off-Grid Assets

GSMA reports that about 4% of the world's population still lives outside mobile broadband coverage, and the land-area gap is far larger [11]. Low-earth-orbit constellations such as Starlink are closing that gap for oil fields, mines and ranches with lower latency and cheaper terminals than legacy GEO services [25]. Hybrid modems that fail over between satellite and cellular cut data costs, opening tank sites that cellular-only devices could never reach.

Restraints Impact Analysis

Restraint weightings below indicate the directional drag each factor places on the Remote Tank Monitoring System Market forecast. Like the driver weightings, they overlap and should not be summed against the CAGR.

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
High retrofit cost in hazardous areas ~-2.3% Global Short-term (≤2 yr)
Cybersecurity exposure of connected OT ~-1.9% North America, Europe Medium-term (2–4 yr)
2G/3G network sunsets and coverage gaps ~-1.6% Global Short-term (≤2 yr)
Integration with legacy SCADA and ERP ~-1.4% Global Medium-term (2–4 yr)
Battery life and field maintenance ~-1.1% South America, Middle East & Africa, Asia-Pacific Long-term (≥4 yr)

High Retrofit Cost in Hazardous Areas

Explosion-proof radar transmitters with hazardous-area certifications are usually priced at USD 1,500–4,000 per measurement point, excluding installation, wiring and hot-work permits [19]. Terminals often have to decommission tanks to install new nozzles, adding to the cost of downtime. Mid-tier chemical and fuel storage providers with fully depreciated float gauges will wait until inspections force them to upgrade, slowing adoption.

Cybersecurity Exposure of Connected OT

Every cellular gateway on a tank creates a new path into operational systems. NIST's Cybersecurity Framework 2.0, released in February 2024, extends governance expectations to supply-chain and device risks [23]. New EU product-security rules raise compliance costs for connected hardware [24]. Refinery and pipeline security teams frequently insist on private APNs or on-premises data hosting, lengthening procurement cycles by several months.

2G/3G Network Sunsets and Coverage Gaps

U.S. carriers retired 3G networks by 2022, stranding thousands of legacy tank monitors, and European operators continue phasing out 2G and 3G through the late 2020s [10]. Each sunset forces unplanned replacement spending that customers view as a cost of ownership, not an upgrade. Buyers burned by earlier stranding now demand multi-network or satellite fallback, raising device prices.

Integration with Legacy SCADA and ERP

Many tank farms run SCADA systems built around Modbus or proprietary protocols, while newer sensors publish over MQTT or REST APIs [11]. Bridging the two requires gateways and custom mapping that small integrators struggle to support. Delivery data must also flow into billing and ERP platforms, and failed integrations leave operators running parallel manual records, eroding the business case.

Battery Life and Field Maintenance

Most wireless tank sensors use lithium primary cells that last five to ten years, although the life is reduced considerably with high transmission rates and satellite uplinks [12]. Batteries on isolated farms, mines or well pads can have to be replaced with a truck roll that costs more than the gadget. Extreme heat in the Gulf and extreme cold in northern Canada both accelerate cell degradation.

Remote Tank Monitoring System Market Opportunities

Five opportunity areas stand out for vendors and investors in the Remote Tank Monitoring System Market over the forecast period.

Rural Water and Agriculture in Emerging Economies

India, Southeast Asia and East Africa are building village water storage and irrigation networks at scale, with public budgets attached [14]. Vendors offering low-cost ultrasonic sensors on NB-IoT or LoRaWAN, with local-language dashboards, can win multi-thousand-tank tenders. Asia-Pacific's 25.1% regional CAGR reflects this pipeline, and partnerships with state water boards offer a repeatable entry path.

Data Monetization and Subscription Business Models

Tank-level data is valuable to more than the tank owner. Distributors price contracts using consumption histories, insurers utilize them to underwrite spill risk, and suppliers plan refinery and blending production with aggregated demand; Vendors shifting from hardware sales to HaaS bundles reap the recurring value. A new, yet credible revenue stream is anonymized demand indices sold to commodity dealers.

Methane Measurement and Reporting Services

OGMP 2.0 asks member companies to reach source-level, measurement-based reporting, and the EU Methane Regulation mirrors that ambition [3][7]. Tank sensors that combine level, pressure and temperature can feed emissions models for flashing and venting losses. Vendors packaging certified emissions data alongside inventory readings can sell into compliance budgets, which are larger and less discretionary than operations budgets.

Hybrid Satellite-Cellular Coverage for Remote Assets

Mines in Chile and Australia, ranches in Brazil and well pads across the Middle East sit outside reliable cellular coverage. Dual-mode modems that default to cellular and fall back to LEO satellite reduce data costs while guaranteeing delivery [25]. Satellite (LEO / GEO) already shows the fastest connectivity growth, and vendors with certified hybrid hardware face limited competition today.

Energy-Transition Fuels and Feedstocks

Biofuel blending terminals, depots for sustainable aviation fuel, ammonia storage and tanks for hydrogen carriers all need accurate level and inventory data, frequently under more stringent safety regulations than traditional fuels [22]. These locations are now being built so monitoring can be selected at the design stage rather than retrofitted. Early references in these areas position vendors for the long-term storage build-out detailed in Section 8.3.

Remote Tank Monitoring System Market Future Outlook

Four themes will shape how the Remote Tank Monitoring System Market evolves over the next decade, each shifting value from hardware toward data and services.

Predictive Replenishment and Autonomous Dispatch

Machine-learning models trained on years of consumption data will forecast tank depletion days and trigger deliveries without human review. Distributors already link level feeds to routing engines [21]; the next step is closed-loop dispatch that books trucks, drivers and supply automatically. Forecast accuracy, not sensor precision, will become the main point of competition.

Platform Economics and Recurring Revenue

Vendors are reorganizing around subscription platforms that bundle hardware, connectivity and analytics. Schneider Electric's full acquisition of AVEVA [17] and Emerson's purchase of the remaining AspenTech stake [18] show large automation groups buying software depth. Over time, platform owners will capture most margin while commodity sensors face steady price pressure.

Storage for Energy-Transition Fuels

The IEA's World Energy Outlook 2024 expects strong growth in biofuels and low-emissions hydrogen through 2035, each requiring new storage [22]. Ammonia, methanol and liquid organic hydrogen carriers bring toxicity and flammability risks that regulators will expect to be monitored continuously. Greenfield terminals will specify remote monitoring from day one, lowering installation costs compared with retrofits.

Emissions Reporting and ESG Disclosure

Corporate climate disclosure rules and OGMP 2.0 commitments push operators toward measured rather than estimated emissions [7]. Industrial tank telemetry will feed emissions inventories, linking working and standing losses to actual throughput and temperature data. Auditable, timestamped tank records will become part of the evidence chain for investor and regulator reporting.

Regional Market Share Analysis

Region Key Metric (2025) Primary Investment Themes
North America 38.6% share SPCC and methane compliance; propane and fuel distributor logistics
Europe USD 0.75 Billion EU Methane Regulation; industrial-emissions permits; chemical parks
Asia-Pacific 25.1% CAGR Rural water programs; chemical safety mandates; agriculture
South America 5.7% share Upstream oil and gas; agribusiness storage
Middle East & Africa USD 0.18 Billion National oil company digitalization; diesel backup and water storage
Total USD 2.83 Billion —

Regional demand in the Remote Tank Monitoring System Market follows regulation and logistics density. North America leads on compliance and distributor scale, Europe on emissions rules, and Asia-Pacific on new infrastructure.

North America

Country Key Metric (2025) Key Driver
United States 81.4% of regional revenue SPCC, UST and OOOOb/c compliance; propane distributor networks
Canada 20.9% CAGR Federal methane regulations; remote oil sands and farm assets
Mexico USD 0.08 Billion Fuel-theft prevention; terminal modernization

The United States anchors regional demand through overlapping federal rules: SPCC for aboveground storage [1], release detection for roughly 540,000 underground tanks [9] and methane standards for oil and gas storage vessels [2]. Canada's federal methane regulations target a 75% reduction from 2012 oil and gas levels by 2030, pushing operators in Alberta and Saskatchewan toward continuous tank data. Mexico's demand centers on fuel-theft detection, where sudden unexplained level drops trigger alerts at terminals and service stations.

Europe

Country Key Metric (2025) Key Driver
United Kingdom 17.8% of regional revenue Heating-oil distribution; North Sea terminal upgrades
Germany USD 0.19 Billion Chemical parks; NB-IoT network density
France 20.1% CAGR Water utilities; agricultural cooperatives
Italy 9.6% of regional revenue Fuel logistics; food and beverage storage
Spain 20.7% CAGR Irrigation and drought management
Russia USD 0.06 Billion Domestic suppliers serving oil storage
Rest of Europe 14.9% of regional revenue Nordic and Benelux port terminals

European demand rests on two pillars: the EU Methane Regulation for hydrocarbon storage [3] and the revised Industrial Emissions Directive, which tightens permit conditions for chemical and refining installations [4]. Germany's chemical clusters lead adoption, helped by dense NB-IoT coverage. Spain and France show above-average growth from drought-driven irrigation and water-utility programs. Russia's market is served largely by domestic suppliers, as sanctions restrict access to Western sensor and software vendors.

Asia-Pacific

Country Key Metric (2025) Key Driver
China 36.2% of regional revenue Hazardous-chemical online monitoring mandates
Japan USD 0.10 Billion Aging fuel infrastructure; labor shortages
India 27.4% CAGR Jal Jeevan Mission; fuel retail expansion
South Korea 7.9% of regional revenue Petrochemical complexes; 5G industrial networks
Australia and New Zealand USD 0.07 Billion Mining and agriculture across remote sites
Southeast Asia 26.3% CAGR Palm oil and fuel distribution; water utilities
Rest of Asia-Pacific 4.6% of regional revenue Port and bunkering terminals

China's Ministry of Emergency Management requires online monitoring of major hazard installations at chemical facilities, making level and pressure telemetry standard in chemical parks. India is the fastest-growing country, combining rural water storage under the Jal Jeevan Mission [14] with rapid fuel-retail expansion. Australia and New Zealand depend on satellite-backed monitoring for mines and stations far from cellular towers [25], while Japan uses remote readings to offset a shrinking pool of delivery drivers.

South America

Country Key Metric (2025) Key Driver
Brazil 58.7% of regional revenue Offshore and onshore oil storage; agribusiness
Argentina 22.6% CAGR Vaca Muerta shale development
Rest of South America USD 0.03 Billion Mining in Chile and Peru

Brazil leads regional spending as oil producers and large agribusiness groups monitor fuel, fertilizer and crop-protection storage across vast estates. Argentina's Vaca Muerta shale play is adding well-pad tank batteries in areas with patchy coverage, favoring satellite and hybrid links. Mining operations in Chile and Peru account for most demand in the rest of the region, monitoring diesel, reagents and process water at high-altitude sites.

Middle East & Africa

Country Key Metric (2025) Key Driver
Saudi Arabia 31.5% of regional revenue National oil company digitalization; Vision 2030
United Arab Emirates 24.2% CAGR Smart-terminal programs; water storage
Turkey USD 0.02 Billion Fuel import terminals; agriculture
Rest of Middle East 10.8% of regional revenue Gulf storage hubs
South Africa USD 0.02 Billion Mining and fuel distribution
Nigeria 23.5% CAGR Diesel backup storage; fuel-theft control
Kenya 3.9% of regional revenue Water utilities; agriculture
Rest of Africa USD 0.01 Billion Mining and humanitarian water storage

Saudi Arabia's Vision 2030 digitalization agenda pushes national energy and water utilities toward centralized asset monitoring [16]. The UAE grows fastest in the Gulf as terminal operators deploy smart-tank programs at export hubs. In Africa, Nigeria's heavy reliance on diesel backup power and persistent fuel theft create strong demand for level alerts. At the same time, Kenya's water utilities and South Africa's mining sector add steady, smaller volumes.

Remote Tank Monitoring System Market By Region, 2025-2035

Remote Tank Monitoring System Market Segmentation

The Remote Tank Monitoring System Market is analyzed across six segmentation dimensions. Each table discloses one metric per segment.

By Monitoring Type

Segment Key Metric Primary Demand Driver
Point-Level Monitoring USD 1.04 Billion (2025) Low-cost high/low alarms for non-hazardous liquids
Continuous-Level Monitoring 63.2% share (2025) Regulatory demand for uninterrupted level tracking

Within the Remote Tank Monitoring System Market, Continuous-Level Monitoring is both the dominant and the faster-growing approach. SPCC programs and Europe's emissions permits favor uninterrupted level records, and continuous data feeds consumption forecasting and leak detection that justify a premium price. Point-Level Monitoring still serves water, lubricant and food tanks where a simple high or low alarm is enough. Still, its share is gradually eroding as buyers standardize on real-time visibility across mixed tank fleets.

By Technology

Segment Key Metric Primary Demand Driver
Contact Sensors (Float and Tape Gauge, Magnetostrictive, Hydrostatic Pressure) 22.0% CAGR (2026–2035) Custody-transfer accuracy; replacement of installed probes
Non-Contact Sensors (Ultrasonic, Radar / FMCW, Optical / Laser) 60.6% share (2025) Corrosive, foaming and high-temperature service

Technology choice in the Remote Tank Monitoring System Market splits between wetted and non-wetted measurement. Non-Contact Sensors lead because Radar / FMCW units, particularly 80 GHz designs [20], handle vapor and foam without maintenance. At the same time, Ultrasonic devices cover cost-sensitive water tanks and Optical / Laser units serve niche solids and narrow vessels. Contact Sensors grow slightly faster as Magnetostrictive and Hydrostatic Pressure probes replace aging Float and Tape Gauge installations in custody-transfer service, where millimeter accuracy remains contractually required.

By Connectivity

Segment Key Metric Primary Demand Driver
Cellular (4G LTE, 5G, NB-IoT, Cat-M) 49.3% share (2025) Low module and data-plan costs
LPWAN (LoRaWAN, Sigfox) USD 0.62 Billion (2025) Private networks across dense tank farms
Satellite (LEO / GEO) 22.4% CAGR (2026–2035) Off-grid oil fields, mines and ranches
Short-Range RF / Wi-Fi / BLE 15.2% share (2025) In-plant links to local gateways

Connectivity defines installation cost across the Remote Tank Monitoring System Market. Cellular leads because NB-IoT and Cat-M plans allow years of battery life at low monthly cost [10]. LPWAN suits operators running private LoRaWAN networks across large sites [12]. Satellite (LEO / GEO) grows fastest as LEO terminals shrink in price and size [25], while Short-Range RF / Wi-Fi / BLE links connect sensors to on-site gateways inside refineries and chemical plants.

By Tank Type

Segment Key Metric Primary Demand Driver
Above-Ground Fixed-Roof 45.8% share (2025) Water, chemical and food liquid storage
Above-Ground Floating-Roof 22.1% CAGR (2026–2035) Overfill standards and methane audits at crude terminals
Underground / UST USD 0.79 Billion (2025) Release-detection rules at fuel retail sites

Tank geometry drives sensor selection in the Remote Tank Monitoring System Market. Above-Ground Fixed-Roof tanks lead because they dominate water, chemical and food storage, where vapor management is simpler. Above-Ground Floating-Roof tanks grow fastest as API 2350 overfill practices [5] and methane audits push crude terminals toward radar that compensates for roof movement. Underground / UST demand remains steady, anchored by release-detection obligations at fuel stations [9].

By End-User Industry

Segment Key Metric Primary Demand Driver
Oil and Gas 30.4% share (2025) Midstream and terminal compliance
Chemicals and Petrochemicals USD 0.46 Billion (2025) Hazardous-material safety rules
Water and Wastewater 13.1% share (2025) Utility storage and treatment chemicals
Food and Beverage 21.2% CAGR (2026–2035) Hygienic storage and batch traceability
Agriculture and Irrigation 22.5% CAGR (2026–2035) Water scarcity and precision-farming grants
Power Generation 6.4% share (2025) Backup fuel and treatment chemicals
Mining and Metals USD 0.14 Billion (2025) Diesel and reagent tracking at remote sites
Pharmaceuticals and Healthcare 20.4% CAGR (2026–2035) Validated storage and GMP records

End-user demand in the Remote Tank Monitoring System Market remains anchored in Oil and Gas, where midstream terminals and well-pad tank batteries face the heaviest compliance load. Chemicals and Petrochemicals follow on safety mandates. Agriculture and Irrigation grows fastest as farms connect fertilizer and water tanks to variable-rate application equipment, helped by programs such as EQIP [15]. Power Generation, Mining and Metals, and Pharmaceuticals and Healthcare add steady, specialized demand.

By Service Model

Segment Key Metric Primary Demand Driver
Stand-alone Hardware Sales 55.6% share (2025) Capex ownership at refineries and pipelines
Hardware-as-a-Service (HaaS) Subscription 22.2% CAGR (2026–2035) Opex budgets among distributors and cooperatives
Fully Managed Turnkey Platforms USD 0.51 Billion (2025) Operators lacking in-house IT staff

Commercial models in the Remote Tank Monitoring System Market are shifting toward recurring revenue. Stand-alone Hardware Sales still lead because large refineries and pipeline operators prefer owning assets and integrating them into existing control systems. Hardware-as-a-Service (HaaS) subscriptions grow fastest as propane dealers and farm cooperatives move spending from capex to opex. Fully Managed Turnkey Platforms appeal to smaller operators that want installation, connectivity and analytics handled by one provider.

Competitive Benchmarking

Competition in the Remote Tank Monitoring System Market is moderately fragmented. Market Research Future estimates the top five vendors hold roughly 33–41% of 2025 revenue, implying an HHI in the 650–800 range. Large automation groups dominate refinery and terminal accounts with radar and tank-gauging systems, while specialist telemetry firms lead in propane, fuel distribution and agriculture through subscription platforms.

Company Est. Revenue Share Range Key Offerings for Remote Tank Monitoring System Market Strategic Positioning
Emerson Electric Co. ~7–10% Rosemount radar level transmitters and tank gauging systems Terminal and refinery leader; deepening software via AspenTech
Schneider Electric SE ~6–9% EcoStruxure monitoring; AVEVA industrial software Platform-led strategy integrating sensors with analytics
Honeywell International Inc. ~6–9% Enraf tank gauging; inventory management software Custody-transfer specialist for large tank farms
Endress+Hauser Group ~5–8% Micropilot radar sensors; Netilion cloud services Process-industry breadth; strong in chemicals
VEGA Grieshaber KG ~4–7% VEGAPULS radar; VEGA Inventory System Radar specialist with inventory-as-a-service offering
Dover Corporation (Anova) ~4–6% Anova tank monitors and fuel-distributor software Distributor logistics focus across propane and fuel
SkyBitz ~3–5% SmartTank cellular and satellite monitors Remote-asset telematics for fuel and chemicals
ATEK Access Technologies ~2–4% TankScan wireless monitors Lubricant and chemical distribution specialist
Otodata Wireless Network Inc. ~2–4% Cellular propane and heating-oil monitors Low-cost devices for residential delivery fleets
Franklin Fueling Systems ~2–4% Automatic tank gauges for fuel retail Underground storage compliance at service stations

Recent News & Developments

  • Schneider Electric (January 2023): Completed the full acquisition of AVEVA, consolidating industrial software that underpins tank inventory and asset-performance applications [17].
  • U.S. EPA (December 2023): Finalized OOOOb/c methane standards covering storage vessels, raising demand for continuous monitoring at well sites and compressor stations [2].
  • NIST (February 2024): Released Cybersecurity Framework 2.0, which operators now reference when approving connected tank gateways [23].
  • European Union (August 2024): The revised Industrial Emissions Directive entered into force, tightening permit conditions for chemical and refining installations [4].
  • European Union (August 2024): The EU Methane Regulation entered into force, introducing leak detection and measurement-based reporting duties for oil and gas operators [3].
  • Emerson (March 2025): Completed its acquisition of the remaining AspenTech shares, adding optimization software that can sit on top of tank-level data [18].

Remote Tank Monitoring System Market Report Scope

Parameter Details
Market Scope The Remote Tank Monitoring System Market covers level sensors, connectivity modules, gateways and software platforms sold through hardware, subscription and managed-service channels for oil, chemical, water, agricultural and industrial storage tanks.
Study Period 2021–2035
Base Year 2025
Historical Data 2021–2024
Forecast Period 2026–2035
Market Size in 2025 USD 2.83 Billion
Market Size in 2035 USD 20.17 Billion
CAGR (2026–2035) 21.8%
Fastest Growing Segments Agriculture and Irrigation (22.5% CAGR); Satellite (LEO / GEO) (22.4% CAGR); Hardware-as-a-Service (HaaS) Subscription (22.2% CAGR); Above-Ground Floating-Roof (22.1% CAGR)
Regions Covered North America, Europe, South America, Asia Pacific, Middle East and Africa and ROW
Companies Profiled Emerson Electric Co., Schneider Electric SE, Honeywell International Inc., Endress+Hauser Group, VEGA Grieshaber KG, Dover Corporation (Anova), SkyBitz, ATEK Access Technologies, Otodata Wireless Network Inc., Franklin Fueling Systems
Valuation Currency USD Billion
Methodology 350+ primary expert interviews; bottom-up market sizing; top-down validation; data triangulation; scenario-based forecasting; real-time project tracking

FAQs

How should buyers compare radar and ultrasonic options in the Remote Tank Monitoring System Market?
Radar, especially 80 GHz units, handles vapor, foam and temperature swings, while ultrasonic sensors cost less but lose accuracy in condensing or dusty headspace. Most buyers reserve radar for hydrocarbons and chemicals and specify ultrasonic for water and benign liquids [20].
What payback period do operators typically see from tank telemetry deployments?
Distributors that replace fixed-schedule deliveries with sensor-triggered dispatch often recover hardware and subscription costs within 12–24 months. Payback is fastest where driver wages, fuel prices and run-out penalties are highest [21].
Which certifications matter when procuring Remote Tank Monitoring System Market solutions for hazardous areas?
Sensors in Zone 0/1 or Class I, Division 1 locations need ATEX or IECEx approval, and overfill-protection loops usually require a SIL rating. Buyers should confirm the sensor, gateway and enclosure are certified as a combined assembly [5].
When do EU cyber rules start to bite for connected tank sensors?
The Cyber Resilience Act's main obligations apply from December 2027, requiring vulnerability handling and security updates across a product's support period. Vendors without secure boot and signed firmware face redesign costs before then [24].
Can existing SCADA historians ingest data from new remote tank sensors?
Most current platforms publish readings over MQTT, OPC UA or REST APIs, which modern historians and ERP systems accept directly. Older Modbus-only SCADA usually needs an edge gateway for protocol translation [11].
What emerging use cases are opening new demand in the Remote Tank Monitoring System Market?
Backup diesel tanks at data centers and telecom towers are a fast-rising niche because uptime contracts penalize fuel run-outs. Hyperscale campuses keep large generator fuel reserves, making continuous level visibility a resilience requirement [22].
How can buyers avoid vendor lock-in on subscription contracts?
Specify open data export, standard protocols and the right to re-point sensors to another cloud before signing multi-year HaaS agreements. Leading vendors in the Remote Tank Monitoring System Market increasingly accept these terms to win utility and municipal tenders [17].
Author
Author Author Profile Nirmit Biswas LinkedIn Senior Research Analyst
With 5+ years of expertise in Market Intelligence and Strategic Research, Nirmit Biswas specializes in ICT, Semiconductors, and BFSI. Backed by an MBA in Financial Services and a Computer Science foundation, Nirmit blends technical depth with business acumen. He has successfully led 100+ projects for global enterprises and startups, including Amazon, Cisco, L&T and Huawei, delivering market estimations, competitive benchmarking, and GTM strategies. His focus lies in transforming complex data into clear, actionable insights that drive growth, innovation, and investment decisions. Recognized for bridging engineering innovation with executive strategy, Nirmit helps businesses navigate dynamic markets with confidence.
Co-Author Co-Author Profile Aarti Dhapte LinkedIn AVP - Research
A consulting professional focused on helping businesses navigate complex markets through structured research and strategic insights. I partner with clients to solve high-impact business problems across market entry strategy, competitive intelligence, and opportunity assessment. Over the course of my experience, I have led and contributed to 100+ market research and consulting engagements, delivering insights across multiple industries and geographies, and supporting strategic decisions linked to $500M+ market opportunities. My core expertise lies in building robust market sizing, forecasting, and commercial models (top-down and bottom-up), alongside deep-dive competitive and industry analysis. I have played a key role in shaping go-to-market strategies, investment cases, and growth roadmaps, enabling clients to make confident, data-backed decisions in dynamic markets.
Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Global Diameter Signaling Market
Case Study
Information and Communications Technology
Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.



















