Recloser Market Summary
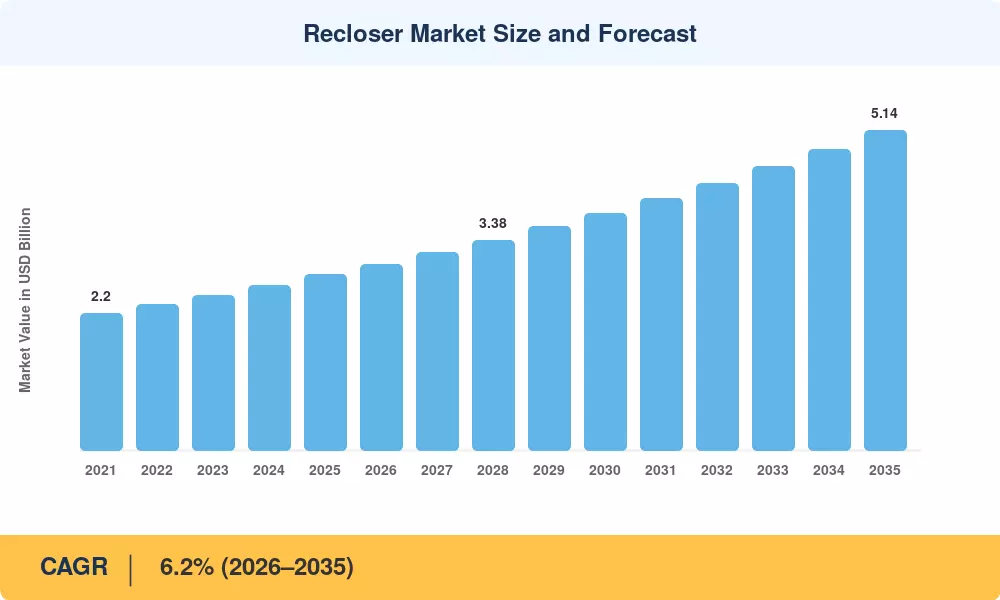
The global Recloser Market reached an estimated USD 2.82 billion in 2025 and is projected to grow from USD 2.99 billion in 2026 to USD 5.14 billion by 2035, registering a CAGR of 6.2% during the forecast period. Grid modernization mandates in North America and aggressive rural electrification programs across India and Sub-Saharan Africa are the twin policy engines powering this expansion. Utilities spent a combined USD 48 billion on distribution automation upgrades in 2024 alone, and reclosers sit at the center of every fault-isolation strategy [1].
Legacy oil-filled reclosers are steadily losing ground to solid-dielectric and vacuum-interrupter designs that eliminate SF₆ gas entirely. The U.S. Department of Energy's Grid Resilience and Innovation Partnerships (GRIP) program allocated USD 10.5 billion through 2026, with distribution-level fault management among eligible project categories [2]. European utilities face binding EN 50549 interconnection codes that demand faster auto-reclosing sequences, accelerating the replacement cycle for aging hydraulic-control units.
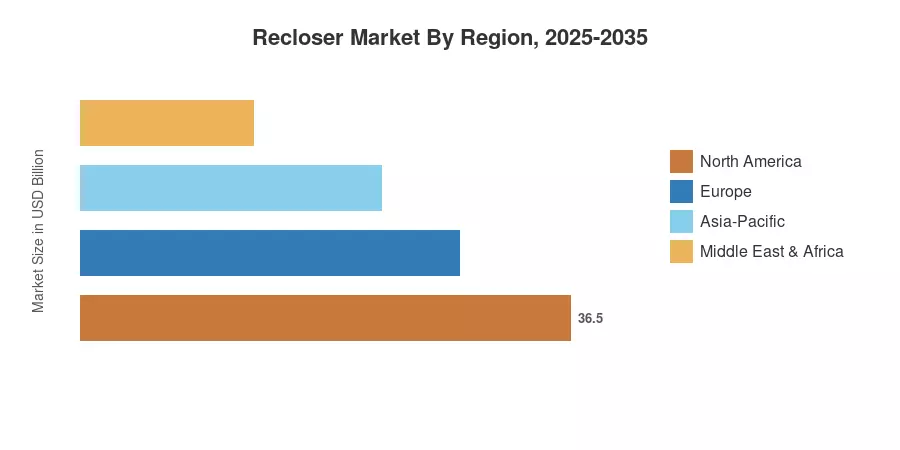
Asia-Pacific commands roughly 38% of the Recloser Market by revenue, driven by China's State Grid Corporation and India's Revamped Distribution Sector Scheme (RDSS). North America holds approximately 28% share, buoyed by wildfire-mitigation spending in California and Texas resilience upgrades. Europe contributes around 22%, with the remaining share split between South America and the Middle East & Africa — the latter posting the fastest regional CAGR above 7.8% as electrification gaps close. The Recloser Market is entering a decade defined by intelligence at the grid edge.
Key Report Takeaways
• By Technology
- Vacuum-interrupter reclosers hold an estimated 52% share of the Recloser Market, favored for their maintenance-free operation and arc-quenching performance in overhead distribution networks.
- Oil-insulated units are declining at a negative growth rate of –1.4% annually as utilities phase out environmentally hazardous dielectrics.
- Solid-dielectric reclosers represent the fastest-growing technology segment with a CAGR of 8.1% through 2035.
• By Application
- Utility distribution accounts for approximately USD 1.75 billion of the Recloser Market in 2025, reflecting mandatory fault-location, isolation, and service-restoration (FLISR) deployments.
- Industrial applications are growing at a 5.9% CAGR as mining and petrochemical facilities upgrade internal medium-voltage protection.
• By Region
- Asia-Pacific leads the Recloser Market at 38% global share, anchored by massive state-funded grid builds in China and India.
- Middle East & Africa posts the highest regional CAGR of 7.8%, driven by off-grid electrification and renewable integration in East Africa.
- North America contributes approximately USD 0.79 billion, with wildfire-prevention mandates as the primary catalyst.
Recloser Market Size and Forecast (2021–2035)
Market Research Future's sizing methodology triangulates bottom-up equipment shipment data from over 40 OEMs with top-down utility capital expenditure disclosures. Historical figures (2021–2024) are reconciled against publicly filed procurement records, while forecast values (2026–2035) apply segment-level growth assumptions validated through primary interviews with distribution planning engineers across 12 countries.



 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA


