Reactive Adhesives Market Summary
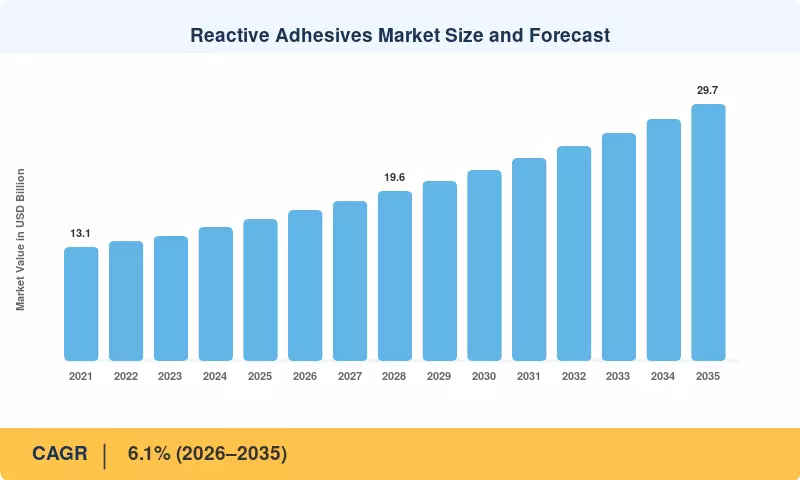
The Reactive Adhesives Market closed 2025 at USD 16.4 billion and enters the forecast window at USD 17.4 billion in 2026, expanding at a 6.1% CAGR to reach USD 29.7 billion by 2035. Two catalysts anchor that trajectory. The first is regulatory: tightening volatile organic compound limits under the U.S. EPA's architectural and industrial maintenance rules and the EU Industrial Emissions Directive have pushed formulators away from solvent-borne chemistries [1][2]. The second is capital: global light-vehicle electrification investment exceeded USD 250 billion in announced plant commitments through 2030, and every battery enclosure, busbar and thermal interface in those plants needs bonded joints rather than welds [3]. Together these forces position the Reactive Adhesives Market as a structural-materials story, not a commodity-chemicals one.
Manufacturers are retiring mechanical fastening, spot welding and solvent-based contact cements in favour of chemistries that cure into load-bearing polymer networks. Rivets and welds create stress concentrations and galvanic corrosion risk in aluminium–steel–composite stacks; cured adhesive lines distribute load and seal simultaneously. The European Commission's Circular Economy Action Plan and its associated substitution funding have accelerated the phase-out of legacy solvent lines across roughly 40% of EU converting capacity since 2021 [4].
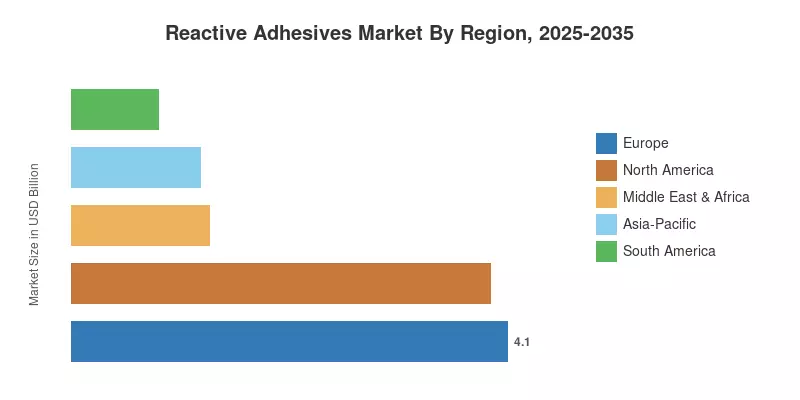
Asia-Pacific anchors the Reactive Adhesives Market with a 41.5% revenue share in 2025, supported by Chinese electronics assembly and Indian automotive capacity additions. Middle East & Africa grows fastest at a 7.9% CAGR off a small base as Gulf industrial-diversification programmes commission downstream converting plants. Europe holds second position, where diisocyanate stewardship rules and automotive lightweighting mandates keep specification activity high. The next decade will reward formulators who can prove bond durability under third-party test protocols rather than those competing on price per kilogram.
Key Report Takeaways
• By Resin Type
- Polyurethane chemistries lead the Reactive Adhesives Market with a 31.0% revenue share in 2025, sustained by flexible-substrate bonding in transportation and footwear
- Epoxy systems generated USD 4.5 billion in 2025 across structural, electronics-encapsulation, and civil-repair applications
- Acrylic and methacrylate systems post the fastest chemistry-level growth at a 6.8% CAGR, driven by fast-fixture assembly lines
• By End User
- Building and construction accounts for 24.0% of Reactive Adhesives Market demand, tied to prefabricated panel and façade adhesion
- Automotive and transportation contributed USD 3.69 billion in 2025 as multi-material body architectures displaced welded assemblies
- Electronics and electricals expand at an 8.1% CAGR, the highest of any end-use sector
• By Region
- Asia-Pacific holds 41.5% of the Reactive Adhesives Market, the largest regional block
- Middle East & Africa records a 7.9% CAGR, the fastest regional growth rate through 2035
- Europe generated USD 4.10 billion in 2025, second only to Asia-Pacific
Market Size and Forecast (2021–2035)
Estimates blend company-reported segment revenues from Henkel, H.B. Fuller, Sika, 3M and Arkema with customs-level trade flows, converter capacity surveys and end-use production statistics from OICA and SEMI [5][6][7]. Historical years are reconciled bottom-up by chemistry and top-down by end-use consumption; forecast years apply sector-weighted demand elasticities rather than a flat growth assumption.




 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA



