Preclinical CRO Market (2026 - 2035)

Preclinical CRO Market Research Report By Service Type (Biologics Testing, Small Molecule Testing, Toxicology Testing, Pharmacology Testing), By Therapeutic Area (Oncology, Neurology, Cardiology, Infectious Diseases), By Validation Type (In Vivo Studies, In Vitro Studies, Comparative Studies, Regulatory Studies), By End User (Pharmaceutical Companies, Biotechnology Companies, Academic Institutions, Research Organizations) and By Regional (North America, Europe, South America, Asia Pacific, Middle East and Africa) - Growth & Industry Forecast 2025 To 2035
ID: MRFR/HS/5807-CR 200 Pages Rahul Gotadki, Nidhi Mandole Last Updated: September 11, 2026
Preclinical CRO Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)8.0%
2025 Market SizeUSD 6.99 Billion
2035 Market SizeUSD 15.09 Billion
Key Players
Charles River Laboratories
Labcorp Drug Development
WuXi AppTec
Inotiv
ICON plc
Eurofins Scientific
Opportunities
  • Organoid-Led Oncology Screening
  • New Approach Methodology Qualification Services
  • Emerging-Market Capacity Build

Preclinical CRO Market Summary

The Preclinical CRO Market closed 2025 at USD 6.99 billion and opens the forecast window at USD 7.55 billion in 2026, tracking toward USD 15.09 billion by 2035 at an 8.0% CAGR. Two catalysts explain most of that trajectory. The FDA Modernization Act 2.0 removed the statutory requirement for animal testing in every investigational new drug application, legitimizing alternative safety packages almost overnight [1]. Simultaneously, sponsors have shifted to asset-light research and development structures, pushing discovery-stage safety and pharmacokinetic work outside their own walls at a pace that internal capacity build-outs cannot match [2].

Distributed contract platforms are displacing in-house single-site and legacy vivarium networks, Good Laboratory Practice suites layered with computational screening. Patient-derived xenograft colonies remain underlie cancer programs, but organoid panels and AI-driven liability prediction now intercept failures earlier and cheaper. This change was consolidated by venture and strategic capital. In 2024, biotechnology firms raised over USD 24 billion globally and a disproportionate amount was invested in virtual corporations with no laboratory footprint at all [3].


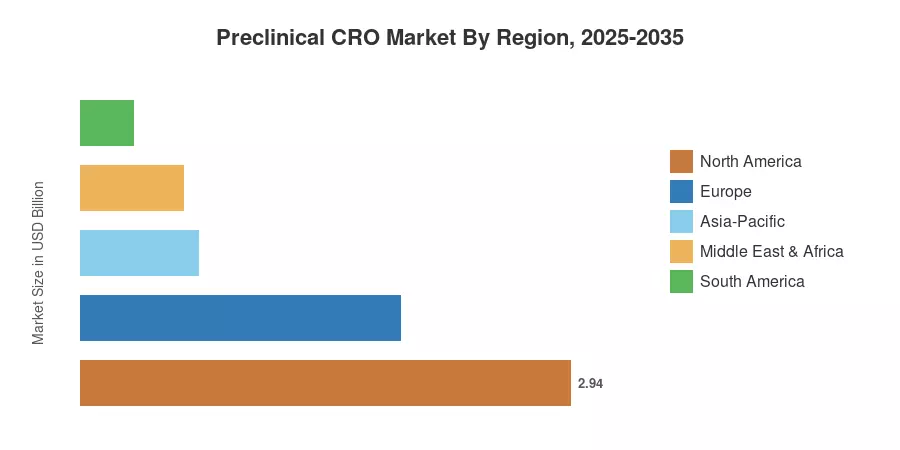
North America commands 42.0% of 2025 revenue on regulatory proximity and dense accredited capacity. Asia-Pacific has the highest growth rate of 10.1% CAGR, driven by cost arbitrage in China and India. Second is Europe at 27.5% with a mature chemical safety base and standardized ICH adoption. Capability, not price, will determine the next decade's worth.


Key Report Takeaways

• By Service

  • Toxicology testing held 37.7% of Preclinical CRO Market revenue in 2025, the single largest service pool.
  • Safety pharmacology is compounding at 11.4% annually through 2035 as cardiovascular liability screening tightens.
  • Bioanalysis and DMPK studies generated USD 1.99 billion in 2025

• By Model Type

  • Patient-derived xenograft models captured 49.8% share in 2025
  • Patient-derived organoid models are advancing at a 12.9% CAGR, the fastest of any model class


• By Geography

  • North America contributed USD 2.94 billion to the Preclinical CRO Market in 2025
  • Asia-Pacific posts a 10.1% CAGR through 2035, the fastest regional rate
  • Europe accounted for 27.5% of 2025 revenue

Market Size and Forecast (2021–2035)

Estimates are based on a combination of service-line revenue disclosures of listed providers, GLP facility registries, sponsor outsourcing ratios based on research and development expenditure forms, and bottom-up study-volume modeling. Historical data are aligned to audited segment reporting. Forecast values are based on capacity-adjusted demand curves for the Preclinical CRO Market.
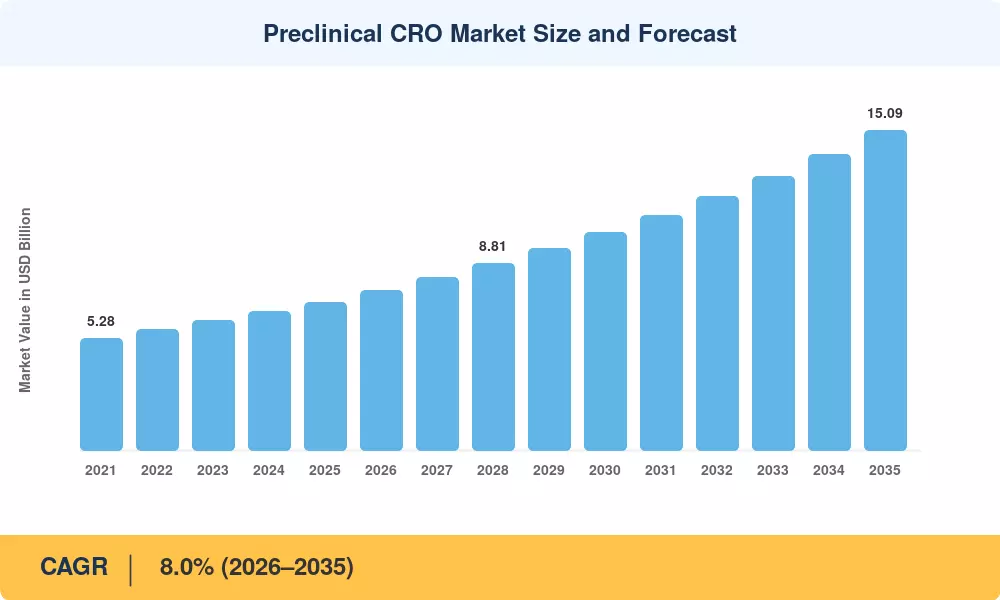
Preclinical CRO Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Asset-light R&D outsourcing by sponsors 2.1 Global Short-term (≤2 yr)
FDA Modernization Act 2.0 implementation 1.6 North America Medium-term (2–4 yr)
Cost arbitrage in China and India 1.4 Asia-Pacific Short-term (≤2 yr)
Cardiovascular safety liability scrutiny 1.1 Global Medium-term (2–4 yr)
AI-enabled in-silico screening adoption 0.9 North America, Europe Long-term (≥4 yr)
Biologics and cell therapy pipeline growth 0.8 Global Long-term (≥4 yr)
Academic translational grant funding 0.5 North America, Europe Medium-term (2–4 yr)


Asset-Light Sponsor Models

Virtual and semi-virtual biotechs now originate a substantial slice of new molecular entities, and almost none maintain their own accredited vivarium. Analysis of 2024 research and development disclosures across mid-cap sponsors shows outsourced discovery spend rising above 62% of total early-stage budgets, up roughly eight percentage points in four years [2]. That structural change converts fixed internal cost into contracted variable cost, and it lands directly on preclinical providers who can absorb full IND-enabling packages.

Regulatory Modernization

Passage of the FDA Modernization Act 2.0 in December 2022 replaced mandatory animal testing language with a broader evidence standard covering organ chips, computational models, and cell-based assays [1]—providers responded by qualifying alternative platforms rather than abandoning classical work. The practical result has been additive: sponsors now commission both a conventional package and a supporting new-approach-methodology dataset, lifting per-program spend by an estimated 9–14% on affected filings [11].

Asia-Pacific Cost Structure

Study execution in China and India runs 35–45% below comparable North American pricing for equivalent GLP scope, and turnaround on non-rodent capacity is often shorter [7]. India's Department of Pharmaceuticals allocated INR 5,000 crore under its Promotion of Research and Innovation in Pharma MedTech Sector scheme, part of which underwrites contract research infrastructure [12]. Western sponsors increasingly split packages, running pivotal toxicology domestically while placing screening tiers offshore.

Safety Pharmacology Intensification

Revised ICH S7B and E14 guidance introduced a best-practice framework for proarrhythmia risk assessment, expanding the in vitro and in vivo evidence expected before first-in-human dosing [5]. Novel modalities including bispecifics and gene therapies carry liability profiles that historical datasets do not cover well. Safety pharmacology consequently grows at 11.4% annually, outpacing every other service line.

Restraints Impact Analysis

Restraint weightings reflect directional drag on growth momentum under a base-case scenario. They are not additive to the forecast CAGR and should be read as relative severity indicators rather than deterministic deductions.

Restraint ~% Drag on CAGR Geographic Relevance Impact Timeline
Biotech funding volatility −1.3 North America, Europe Short-term (≤2 yr)
Non-human primate supply constraints −0.9 Global Medium-term (2–4 yr)
Data integrity and audit findings −0.6 Asia-Pacific Medium-term (2–4 yr)
Cross-border data transfer restrictions −0.5 Asia-Pacific, Europe Long-term (≥4 yr)
Specialist scientific staff shortages −0.4 Global Long-term (≥4 yr)


Funding Cycle Sensitivity

Small and mid-cap sponsors fund the majority of discovery-stage contracts, and their spending tracks capital markets almost one-for-one. Global biotech venture inflows fell close to 30% from the 2021 peak before stabilizing, and the 2024 soft patch is visible in the 6.7% growth print that year [3]. Providers with heavy exposure to seed-stage clients absorbed cancellation rates well above their large-pharma-weighted peers.

Biological Supply and Ethical Pressure

Non-human primate availability tightened sharply after export restrictions and enforcement actions disrupted established channels, lifting per-animal costs several-fold and stretching study-start queues [13]. Ethical review committees in Europe apply the 3Rs framework with increasing rigor, adding weeks to protocol approval. Both forces raise the floor price of large-species toxicology preclinical research and push sponsors toward alternative designs.

Quality and Compliance Exposure

Regulatory inspections at offshore facilities have produced observations relating to raw data traceability and electronic record controls, and a single significant finding can invalidate an entire submission package [14]. Sponsors respond with duplicate audits and split sourcing, which raises transaction cost and slows the migration of high-value work to lower-cost geographies.

Preclinical CRO Market Opportunities

Organoid-Led Oncology Screening

Patient-derived organoid panels reproduce tumor heterogeneity with shorter cycle times than xenograft colonies, and they scale across hundreds of donor lines. Providers building biobanked organoid libraries can price per-compound screening rather than per-animal, a structurally higher-margin model [6]. Growth at 12.9% annually makes this the fastest-moving model class in the taxonomy.

New Approach Methodology Qualification Services

Sponsors need help proving that organ-on-chip or computational evidence will survive review. A qualification advisory line — protocol design, historical control curation, regulatory correspondence — carries consultancy economics on top of laboratory revenue [11]. Early movers are effectively selling regulatory confidence rather than bench hours.

Emerging-Market Capacity Build

Brazil, Saudi Arabia, and the ASEAN bloc have all announced life-science localization programs, and none currently hosts sufficient accredited preclinical capacity to serve domestic pipelines [17]. Middle East and Africa grow at 8.8% from a small base, and first-entrant providers can lock multi-year government-linked contracts before pricing compresses.

Historical Control Data Monetization

Decades of control-arm results sit unused inside provider archives. Curated, de-identified historical control databases licensed to sponsors reduce animal use, shrink study designs, and generate recurring subscription revenue with near-zero marginal cost [9]. Several mid-tier providers have begun bundling database access into master service agreements.

Integrated Discovery-to-IND Packages

Sponsors increasingly prefer one accountable partner across pharmacology, DMPK, and safety rather than four vendors and a coordinator. Bundled programs command 12–18% pricing premiums and materially improve revenue visibility [2]. Consolidation among large providers is largely a race to assemble this capability set.

Preclinical CRO Market Future Outlook

Computational Displacement, Not Replacement

Machine learning models trained on curated historical control data will intercept a growing share of failures before any animal is dosed. Realistic projections suggest computational triage removes 15–20% of low-value studies by 2032 while raising complexity — and price — of those that remain [9]. Volume flattens; revenue does not.

Platform Economics

Providers are converting from project shops into platforms, monetizing data assets, assay libraries, and regulatory know-how alongside bench capacity. Subscription and access-fee revenue currently represents a low single-digit share of provider income; a mid-teens share by 2035 would materially reshape valuation multiples across the sector [2].

Modality Shift Toward Advanced Therapies

Cell and gene therapy programs in active development exceeded 2,000 globally as of 2024, and their preclinical requirements differ fundamentally from small molecules — biodistribution, immunogenicity, and long-term tumorigenicity dominate [8]. Providers that qualify these specialized capabilities early will capture disproportionate pricing power.

Sustainability and Animal Welfare Reporting

Institutional investors now request 3Rs performance metrics alongside financial reporting, and several large sponsors publish annual animal-use reductions [18]. Expect welfare disclosure to become a formal procurement criterion within the decade, advantaging providers with validated alternative platforms and transparent audit trails.

Regional Market Share Analysis

Region Metric (2025 / Forecast) Primary Investment Themes
North America 42.0% share GLP capacity expansion, NAM qualification
Europe 27.5% share 3Rs compliance, chemical safety testing
Asia-Pacific 10.1% CAGR Cost arbitrage, domestic pipeline growth
South America USD 0.32 Billion Regulatory harmonization, clinical bridging
Middle East & Africa 8.8% CAGR Sovereign life-science funds, localization
Total USD 6.99 Billion

Regional performance in the Preclinical CRO Market reflects three variables: accredited capacity density, regulatory proximity to major filing agencies, and unit cost. The table below reports one metric per region.


North America

Country Metric Key Driver
US 84.5% of region FDA proximity and accredited site density
Canada 7.4% CAGR Scientific Research and Experimental Development tax credits
Mexico USD 0.13 Billion Nearshoring of laboratory services


North America anchors the Preclinical CRO Market because sponsors value pre-submission dialogue with reviewers more than they value unit savings. The National Center for Advancing Translational Sciences committed sustained funding to tissue-chip validation, seeding a domestic alternative-methods ecosystem that providers now commercialize [10]. Canada's federal tax credit regime meaningfully reduces effective study cost for sponsors with local subsidiaries, and Toronto and Montreal have both added specialty bioanalysis capacity since 2023.

Europe

Country Metric Key Driver
Germany 24.8% of region Chemical and pharmaceutical safety base
UK 7.3% CAGR Life Sciences Vision funding
France USD 0.27 Billion National oncology cluster demand
Italy 9.6% of region Contract manufacturing spillover
Spain 7.5% CAGR Cost-competitive GLP sites
Nordic Countries USD 0.14 Billion Academic translational partnerships
Russia 3.8% of region Domestic substitution programs
Rest of Europe 6.6% CAGR Central European capacity growth


European demand rests on Directive 2010/63/EU, which codifies the 3Rs and requires justification for every animal procedure [18]. That framework slowed volume growth but pushed providers up the value curve into complex, well-documented study designs that sponsors cannot easily replicate offshore. Germany's chemical safety infrastructure — built originally for REACH compliance — cross-subsidizes pharmaceutical toxicology capacity, giving it the region's deepest bench.

Asia-Pacific

Country Metric Key Driver
China 38.4% of region Integrated discovery platforms at scale
India 12.4% CAGR PRIP scheme and skilled scientific labor
Japan USD 0.29 Billion PMDA-aligned domestic programs
South Korea 8.9% of region Biosimilar and cell therapy pipelines
ASEAN 10.6% CAGR Singapore and Malaysia capacity additions
Rest of Asia-Pacific USD 0.10 Billion Australian early-phase incentives


Asia-Pacific is the growth engine of the Preclinical CRO Market, and China supplies most of the volume. Domestic providers built end-to-end platforms that compress discovery-to-IND timelines below Western benchmarks, while the National Medical Products Administration's ICH accession improved dossier portability [19]. India differentiates on scientific labor economics rather than pure throughput, and the PRIP scheme's infrastructure component targets exactly the accredited capacity gap that currently caps its share [12].

South America

Country Metric Key Driver
Brazil 58.2% of region ANVISA modernization and local pipelines
Argentina 8.1% CAGR Academic biotech spinouts
Rest of South America USD 0.06 Billion Regional clinical bridging studies


Brazil dominates a small regional base, supported by ANVISA's progressive alignment with international guidance and by domestic manufacturers moving beyond generics into biosimilars [17]. Capacity remains thin: most pivotal toxicology still routes to North America. The near-term opportunity is exploratory and screening-tier work, where proximity and language reduce coordination friction for local sponsors.

Middle East & Africa

Country Metric Key Driver
Saudi Arabia 27.4% of region Vision 2030 biotech localization
UAE 9.6% CAGR Free-zone research infrastructure
South Africa USD 0.05 Billion Infectious disease research base
Egypt 11.2% of region Pharmaceutical manufacturing cluster
Rest of MEA 8.0% CAGR Sovereign health investment programs


Saudi Arabia's National Biotechnology Strategy targets domestic capability across the development chain by 2030, with dedicated funding for research infrastructure [20]. Execution risk is high and accredited capacity remains minimal, yet sovereign backing removes the demand uncertainty that constrains private investment elsewhere. South Africa's infectious disease research base gives it a defensible specialty niche rather than broad-spectrum competition.

Preclinical CRO Market By Region, 2025-2035

Preclinical CRO Market Segmentation

Segmentation across the Preclinical CRO Market follows service line, biological model type, and end-user category. Each table reports a single metric per sub-segment.

By Service

Segment Metric Primary Demand Driver
Toxicology Testing 37.7% share IND-enabling package requirements
Bioanalysis & DMPK Studies USD 1.99 Billion Regulated bioanalytical method validation
Safety Pharmacology 11.4% CAGR Revised ICH S7B proarrhythmia framework
Other Services 15.3% share Efficacy models and formulation support


Toxicology remains the revenue backbone of the Preclinical CRO Market because no filing route avoids it entirely — the evidence standard changed, the evidence requirement did not [1]. Safety pharmacology grows faster than the aggregate because novel modalities generate liability questions that legacy datasets cannot answer, and because cardiovascular assessment expectations tightened materially under revised guidance [5].

By Model Type

Segment Metric Primary Demand Driver
Patient-Derived Xenograft (PDX) Models 49.8% share Established oncology translational validity
Patient-Derived Organoid (PDO) Models 12.9% CAGR Faster, higher-throughput tumor screening
In-Silico / AI-Driven Models 22.6% share Early liability prediction and cost reduction


Xenograft models retain their lead within the Preclinical CRO Market on the strength of a two-decade regulatory track record that reviewers trust. Organoids are winning the screening tier first — where speed and donor diversity matter more than precedent — and will migrate into confirmatory roles as validation packages accumulate [6].

By End User

Segment Metric Primary Demand Driver
Biopharma & Pharma Companies 59.2% share Pipeline volume and outsourcing mandates
Academic & Research Institutes 11.0% CAGR Translational grant funding expansion
Medical Device Companies USD 0.99 Billion Biocompatibility and implant safety testing
Government & Others 10.3% share Public health and biodefense programs


Biopharma sponsors dominate Preclinical CRO Market spending and set its pricing conventions, though their share is slowly diluting. Academic institutes grow fastest as translational funding pushes university programs toward IND-quality data they cannot generate internally, creating a client segment with different scale, cadence, and service expectations [10].

Competitive Benchmarking

Concentration is moderate. The top five providers account for around 38-43% of global revenue, implying an HHI in the 500-700 range — competitive by antitrust standards but consolidating steadily as scale giants buy up niche capabilities. And below the leaders, there’s a long tail of regional and specialist providers competing on turnaround and therapeutic focus rather than breadth.

Company Est. Revenue Share Range Key Offerings for Preclinical CRO Market Strategic Positioning
Charles River Laboratories ~15–19% Toxicology, model supply, safety assessment Scale leader with integrated model sourcing
Labcorp Drug Development ~7–10% Toxicology, bioanalysis, discovery services Diagnostics-linked data advantage
WuXi AppTec ~6–9% Integrated discovery-to-IND platforms Cost and speed leadership in Asia-Pacific
Inotiv ~4–6% General and specialty toxicology, DMPK Consolidator of US mid-tier capacity
ICON plc ~3–5% Early development and bioanalytical services Clinical continuity for sponsors
Eurofins Scientific ~3–5% Bioanalysis, biocompatibility, GLP testing Distributed laboratory network
Evotec SE ~2–4% Discovery pharmacology, in-silico platforms Science-led partnership model
Pharmaron ~2–4% Safety assessment, DMPK, radiolabeling Cross-border capacity in China and UK
Frontage Laboratories ~1–3% Bioanalysis, DMPK, toxicology Mid-cap sponsor specialist
Crown Bioscience ~1–3% PDX and organoid oncology platforms Translational oncology model depth
Altasciences ~1–3% Preclinical-to-Phase I continuum Integrated early-phase handoff


Recent News & Developments

Deal activity across the Preclinical CRO Market has centered on capability acquisition rather than pure capacity addition.

  • US FDA (April 2025): Published a roadmap to reduce animal testing requirements for monoclonal antibodies, prioritizing computational and human-cell-based approaches — a direct signal on qualification priorities [11]
  • Charles River Laboratories (February 2025): Announced a strategic review and portfolio restructuring following softer demand from small-cap biotech clients, reshaping capacity planning across the sector [4]
  • Inotiv (October 2024): Completed consolidation of multiple US toxicology sites to lift utilization and reduce fixed-cost exposure [4]
  • Evotec SE (June 2024): Expanded its AI-driven discovery partnership framework, extending in-silico liability screening into partner pipelines [9]
  • India Department of Pharmaceuticals (March 2024): Opened PRIP scheme funding windows covering contract research infrastructure and translational facilities [12]
  • NMPA China (November 2023): Advanced ICH guideline implementation, improving mutual recognition of domestically generated preclinical dossiers [19]
  • ICH (February 2023): Finalized the S7B/E14 question-and-answer framework establishing best practice for proarrhythmia risk assessment [5]
  • Saudi Arabia (December 2023): Launched the National Biotechnology Strategy with dedicated allocations for research infrastructure through 2030 [20]

Preclinical CRO Market Report Scope

Parameter Detail
Market Scope Global outsourced preclinical research services across toxicology, bioanalysis and DMPK, safety pharmacology, and adjacent discovery support
Study Period 2021–2035 (Historical 2021–2024; Base Year 2025; Forecast 2026–2035)
CAGR 8.0% (2026–2035)
Market Size Checkpoints USD 6.99 Billion (2025); USD 7.55 Billion (2026); USD 15.09 Billion (2035)
Fastest Growing Segments Safety Pharmacology (service); Patient-Derived Organoid Models (model type); Academic & Research Institutes (end user)
Companies Profiled 11 leading providers benchmarked in the Preclinical CRO Market
Valuation Currency USD Billion

FAQs

How should a sponsor shortlist vendors in the Preclinical CRO Market?
Weight inspection history and scientific staff turnover above headline price. Request the provider's last three regulatory inspection outcomes and study-director tenure data before pricing discussions begin [14].
Which contracting structure best controls budget overruns on toxicology packages?
Milestone-based fixed-fee contracts with defined change-order triggers outperform time-and-materials arrangements. Specify animal cost pass-through caps explicitly, since biological supply volatility drives most unplanned spend [13].
Does the Preclinical CRO Market reward single-source or multi-vendor strategies?
Single-source suits integrated IND packages where handoff losses are costly. Multi-vendor protects programs with long timelines against capacity disruption, at the price of higher coordination overhead [2].
How do data ownership terms differ across geographies?
Western contracts typically assign all study data and derived analytics to the sponsor. Several Asian jurisdictions impose localization requirements that restrict raw data export, so negotiate transfer mechanics upfront [15].
What audit signals matter most when qualifying a new Preclinical CRO Market supplier?
Examine raw data traceability, electronic record audit trails, and archive retrieval speed. A provider that cannot produce a five-year-old raw dataset within days is a submission risk [24].
Can computational evidence fully replace animal data for an IND filing?
Not yet, in practice. Regulators accept alternative methods as supporting evidence, but full replacement requires case-by-case qualification and remains rare outside narrow modality classes [25].
What breaks when transferring assays between provider sites?
Historical control ranges rarely transfer cleanly, which complicates interpretation of borderline findings. Budget for a bridging study and insist on documented method transfer protocols before relocating any validated assay [24].    
Author
Author Author Profile Rahul Gotadki LinkedIn Research Manager
He holds an experience of about 9+ years in Market Research and Business Consulting, working under the spectrum of Life Sciences and Healthcare domains. Rahul conceptualizes and implements a scalable business strategy and provides strategic leadership to the clients. His expertise lies in market estimation, competitive intelligence, pipeline analysis, customer assessment, etc.
Co-Author Co-Author Profile Nidhi Mandole LinkedIn Senior Research Analyst
She is an extremely curious individual currently working in Healthcare and Medical Devices Domain. Nidhi is comfortably versed in data centric research backed by healthcare educational background. She leverages extensive data mining and analytics tools such as Primary and Secondary Research, Statistical Analysis, Machine Learning, Data Modelling. Her key role also involves Technical Sales Support, Client Interaction and Project management within the Healthcare team. Lastly, she showcases extensive affinity towards learning new skills and remain fascinated in implementing them.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of regulatory databases, peer-reviewed scientific journals, clinical pharmacology publications, and authoritative life sciences organizations. Key sources included the US Food & Drug Administration (FDA) Center for Drug Evaluation and Research (CDER), European Medicines Agency (EMA) Committee for Medicinal Products for Human Use (CHMP), National Institutes of Health (NIH) National Toxicology Program (NTP), US Department of Agriculture (USDA) Animal and Plant Health Inspection Service, Environmental Protection Agency (EPA) Office of Chemical Safety and Pollution Prevention, Organisation for Economic Co-operation and Development (OECD) Test Guidelines Programme, World Health Organization (WHO) International Programme on Chemical Safety, Centers for Disease Control and Prevention (CDC) National Institute for Occupational Safety and Health, Public Library of Science (PLOS), Society of Toxicology (SOT) publications, American Association for Laboratory Animal Science (AALAS) Journal, Association for Assessment and Accreditation of Laboratory Animal Care International (AAALAC) annual reports, BioPharma Dive, Contract Pharma outsourcing databases, and national regulatory authority filings from key pharmaceutical markets. These sources were used to collect preclinical study volume statistics, GLP (Good Laboratory Practice) certification data, toxicology safety assessment trends, regulatory paradigm shifts, and competitive landscape analysis for in vivo pharmacology, in vitro ADME (Absorption, Distribution, Metabolism, Excretion) studies, toxicology testing, bioanalytical services, and specialty pathology services.


Primary Research

To gather both qualitative and quantitative information, the primary research process involved interviewing players from both the supply and demand sides. Executives, COOs, CSOs, chiefs of business development, site directors, and heads of laboratory operations from regional and international preclinical CROs made up the supply side. On the demand side, we had CSOs, VPs of preclinical development, heads of external research and development sourcing, procurement leaders from biotech and pharmaceutical businesses, and medical device portfolio managers. Service line segmentation, capacity expansion timetables, outsourcing penetration rates, pricing models for GLP vs. non-GLP investigations, and therapeutic area-specific demand dynamics were all investigated through primary research, which also confirmed the timelines.

Primary Respondent Breakdown:

By Designation: C-level Executives (28%), Director Level (32%), Scientific/Technical Leads (40%)

By Region: North America (32%), Europe (35%), Asia-Pacific (25%), Rest of World (8%)

By Stakeholder Type: CRO Service Providers (45%), Pharmaceutical/Biotech Sponsors (40%), Academic/Government Research Institutes (15%)


Market Size Estimation

Global market valuation was derived through revenue mapping and study volume analysis across toxicology, pharmacokinetics, pharmacodynamics, and safety assessment services. The methodology included:

Identification of 60+ key contract research organizations across North America, Europe, Asia-Pacific, and Latin America

Service mapping across toxicology (acute, chronic, carcinogenicity), pharmacology (efficacy models, PD/PK), bioanalytical (LC-MS/MS, immunogenicity), pathology (histology, necropsy), and specialized cell & gene therapy preclinical services

Analysis of reported and modeled annual revenues specific to preclinical service portfolios

Coverage of CROs representing 65-70% of global market share in 2024

Extrapolation using bottom-up (study volume × average contract value by therapeutic area) and top-down (CRO revenue validation against sponsor R&D outsourcing budgets) approaches to derive segment-specific valuations across small molecule, biologics, and cell/gene therapy preclinical requirements

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.
















