Pipe Fittings Market Summary
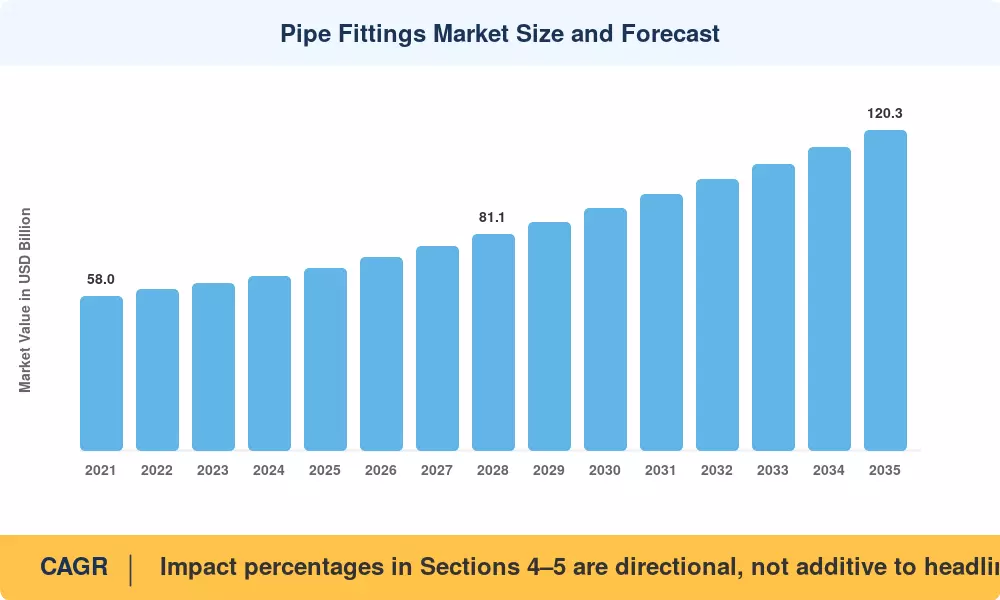
The global pipe fittings market reached an estimated USD 68.5 billion in 2025 and is projected to grow from USD 72.5 billion in 2026 to USD 120.3 billion by 2035, registering a CAGR of 5.8% over the forecast period (2026–2035). Two catalysts anchor this trajectory: accelerating urbanization across South and Southeast Asia — where the UN projects 2.5 billion additional urban residents by 2050 [1] — and aging water distribution networks across North America and Europe that require wholesale replacement [2]. The pipe fittings market benefits directly from both demand vectors.
Legacy cast iron and galvanized steel piping systems, many installed during mid-twentieth-century infrastructure buildouts, are being systematically replaced by corrosion-resistant polymer and composite alternatives. India's Jal Jeevan Mission alone has committed over USD 50 billion toward household water connections, driving demand for connection-grade fittings at an unprecedented pace [3]. In the United States, the Bipartisan Infrastructure Law earmarked USD 55 billion for water infrastructure improvements through 2030, with a significant share directed at lead service line replacement and distribution network upgrades [4]. These policy mandates create sustained, multi-year procurement pipelines for the pipe fittings market.
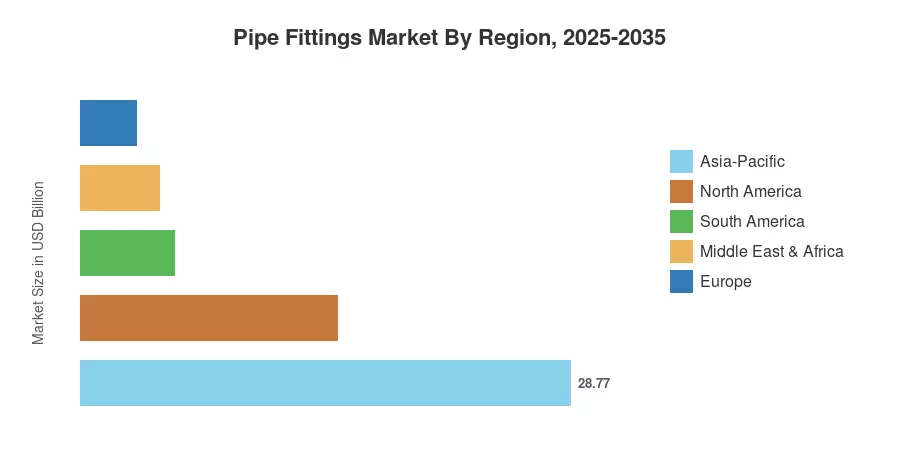
Asia-Pacific dominates the pipe fittings market with approximately 42% of global revenue, propelled by construction activity in China, India, and ASEAN nations. The region also registers the fastest growth at roughly 7.2% CAGR through 2035. North America holds the second-largest position with approximately 22% share, supported by federal infrastructure spending and municipal water system rehabilitation. Europe accounts for roughly 21%, with demand concentrated in district heating modernization and circular-economy mandates. As climate adaptation spending intensifies worldwide, the pipe fittings market is positioned for a decade of structurally elevated demand.
Key Report Takeaways
• By Material Type
- Plastic fittings (PVC, CPVC, HDPE, PP) account for approximately 38% of the global pipe fittings market, driven by lower installation costs and corrosion resistance.
- Steel fittings command the highest per-unit value, registering a segment CAGR of 4.9% as oil & gas and heavy industrial applications sustain demand.
- Copper fittings represent approximately USD 6.8 billion in 2025 value, concentrated in HVAC and medical gas applications.
• By End-Use Sector
- Water & wastewater treatment is the largest end-use segment in the pipe fittings market, capturing roughly 31% share globally.
- Oil & gas applications deliver the fastest segmental CAGR at 6.4%, tied to midstream pipeline expansion in the Middle East and North America.
- Residential construction accounts for approximately USD 16.2 billion, with growth concentrated in Asia-Pacific housing starts.
• By Geography
- Asia-Pacific leads the pipe fittings market at ~42% share, with China alone contributing roughly 18% of global demand.
- Middle East & Africa registers the second-fastest regional CAGR at 6.8%, driven by Saudi Arabia's NEOM and broader Vision 2030 construction programs.
- Europe's pipe fittings market share stands at approximately 21%, anchored by district energy retrofits and EU water reuse directives.
Pipe Fittings Market Size and Forecast (2021–2035)
Market Research Future employs a bottom-up methodology combining manufacturer revenue disclosures, trade data from national customs databases, and end-use consumption modeling across five regions. Historical figures (2021–2024) are triangulated against industry association shipment data. Forecast projections (2026–2035) apply a 5.8% CAGR anchored to construction output forecasts from and infrastructure spending commitments tracked by the Global Infrastructure Hub [5].