Perlite Market (2026 - 2035)

Perlite Market Research Report Information By Product Type (Expanded Perlite, Agro-Perlite, and Vapex & Specialty Grades), By Application (Insulation, Fire-Proofing & Refractory, Soil Amendment & Horticulture, Filtration, and Others), By End-Use Industry (Construction & Infrastructure, Horticulture & Agriculture, Industrial Manufacturing, and Others) – Forecast Till 2035
ID: MRFR/CnM/5255-HCR 100 Pages Chitranshi Jaiswal Last Updated: September 15, 2026
Perlite Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)5.25%
2025 Market SizeUSD 2.62 Billion
2035 Market SizeUSD 4.38 Billion
Key Players
Imerys S.A.
Keltech Energies
Aegean Perlites S.A.
Termolita S.A.
Cornerstone Industrial Minerals
Silbrico Corporation
Opportunities
  • Controlled-Environment Agriculture Expansion
  • Cryogenic Insulation for Hydrogen Economy
  • Data Monetization via Smart-Mining Platforms

Perlite Market Summary

The Perlite Market was valued at USD 2.62 billion in 2025, with the forecast period commencing at USD 2.76 billion in 2026 and projected to reach USD 4.38 billion by 2035, registering a CAGR of 5.25% during 2026–2035. Tightening energy-efficiency mandates across the European Union's Energy Performance of Buildings Directive (EPBD) recast and the U.S. Department of Energy's updated commercial building insulation codes are channeling fresh capital toward lightweight aggregates and construction insulation materials, directly accelerating demand for expanded perlite across residential and commercial envelopes[2].

A broad transformation is reshaping how builders, growers, and manufacturers source industrial mineral products. Legacy vermiculite-based insulation and synthetic polymer foams are giving way to perlite insulation solutions that deliver superior fire resistance, lower embodied carbon, and compatibility with passive-house design standards. The International Energy Agency estimates that USD 290 billion was invested globally in building-envelope upgrades during 2024, a figure that positions volcanic glass minerals as beneficiaries of the next decade's retrofit wave [3]. Horticultural perlite is simultaneously displacing peat-based substrates as EU peatland-protection regulations tighten, opening a parallel growth corridor for soil conditioning materials.

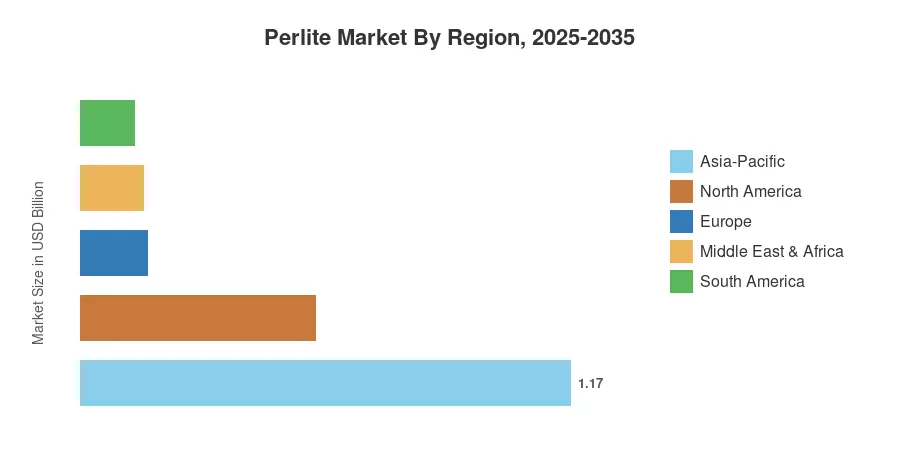
Asia-Pacific commands the largest share of the Perlite Market at approximately 44.8% of 2025 revenue, propelled by infrastructure spending across China and India. The region also posts the fastest CAGR at 6.25% through 2035. Europe holds the second-largest position with a roughly 24% share, driven by stringent thermal-performance benchmarks. North America follows closely, anchored by expanded perlite adoption in cryogenic storage and craft-beverage filtration aids

Key Report Takeaways

• By Product Type

  • Expanded perlite commanded approximately 62.5% of the Perlite Market share in 2025, underpinned by its dominant role in construction insulation materials and horticultural substrates
  • Vapex & Specialty Grades are advancing at the highest projected CAGR of 5.85% through 2035, driven by cryogenic storage and precision filtration aids applications
  • Agro-Perlite reached approximately USD 0.47 billion in 2025 as demand for soil conditioning materials expands in greenhouse cultivation

• By Application

  • Insulation accounted for roughly 40.1% of the Perlite Market size in 2025, reflecting the global push for fire-resistant materials in energy-efficient envelopes
  • Soil amendment and horticulture are growing at a 5.45% CAGR to 2035, fueled by peat-replacement mandates and precision agriculture

• By End-Use Industry

  • Construction & infrastructure captured approximately USD 1.01 billion in 2025 revenue within the Perlite Market, supported by lightweight aggregates adoption
  • Horticulture & agriculture posts the fastest end-use CAGR at 5.55% through 2035, as horticultural perlite replaces traditional growing media

• By Region

  • Asia-Pacific held 44.8% of the Perlite Market revenue in 2025, expanding at a 6.25% CAGR
  • North America accounted for roughly 21.5% share, driven by cryogenic insulation and filtration aids demand

Market Size and Forecast (2021–2035)

Market Research Future (MRFR)'s proprietary estimation framework combines primary interviews with perlite producers, trade-association data, and customs-volume analysis across 32 countries. Historical figures (2021–2024) rely on audited company revenues and USGS mineral-commodity summaries, while the forecast (2026–2035) applies regression modeling calibrated against construction-start indices, agricultural-input spending, and industrial-process demand for volcanic glass minerals.
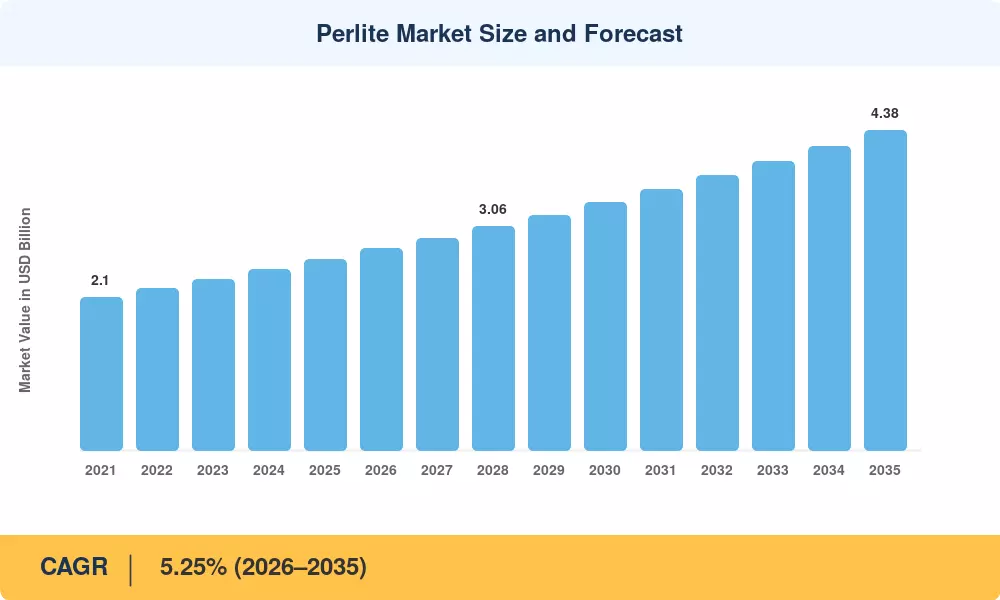
Perlite Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Energy-efficiency building codes +1.4% Europe, North America Medium-term (2–4 yr)
Urbanization & infrastructure spending +1.2% Asia-Pacific, South America Long-term (≥4 yr)
Peat-replacement regulations +0.8% Europe, North America Short-term (≤2 yr)
Cryogenic & LNG storage expansion +0.6% Middle East, Asia-Pacific Medium-term (2–4 yr)
Craft-beverage filtration growth +0.4% North America, Europe Short-term (≤2 yr)
Fire-safety code upgrades +0.5% Europe, Asia-Pacific Medium-term (2–4 yr)
Greenhouse & controlled-environment agriculture +0.6% Asia-Pacific, North America Long-term (≥4 yr)


Energy-Efficiency Building Codes

The EU's recast EPBD mandates that all new buildings achieve near-zero energy consumption by 2030, requiring wall and roof assemblies to meet U-values that favor construction insulation materials with low thermal conductivity. Expanded perlite loose-fill and board products deliver thermal conductivities of 0.04–0.06 W/m·K, positioning them as cost-effective alternatives to petrochemical foams. The European Commission has earmarked EUR 150 billion under the Renovation Wave strategy, directly funding retrofit projects that consume lightweight aggregates in cavity-wall insulation [2].

Urbanization and Infrastructure Spending

UN-Habitat estimates that between 2020 and 2025, the Asia-Pacific region will add 120 million urban dwellers. CNY 4.7 trillion was up in China's 14th Five-Year Plan for urban renovation initiatives that require mid-rise concrete masonry to use fire-resistant components. 20 million affordable housing units are the goal of India's Pradhan Mantri Awas Yojana, many of which use perlite insulation in roof screeds. These initiatives support the Perlite Market's long-term volume expansion throughout the area [6].

Peat-Replacement and Horticulture Mandates

The European Commission's proposal to restrict horticultural peat extraction by 2030 under the Nature Restoration Law has already shifted commercial growers toward horticultural perlite substrates. The Netherlands, the continent's largest greenhouse cluster, imported 18% more soil conditioning materials based on perlite in 2024 versus 2023. This regulatory tailwind converts a niche agricultural input into a mainstream growing medium and creates durable demand for the Perlite Market [3].

Cryogenic and LNG Storage Expansion

The International Gas Union projects that between 2025 and 2030, global LNG liquefaction capacity will increase by 230 MTPA. Ultra-low-density expanded perlite is needed for cryogenic tank insulation in order to keep temperatures below –162 °C. Perlite insulation solutions are required for all new storage tanks in Qatar's North Field expansion, which amounts to a USD 30 billion investment [11].

Restraints Impact Analysis

Impact estimates below represent directional headwinds on the Perlite Market CAGR. They are not directly subtracted from the growth rate and instead serve as risk-assessment inputs.

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
Logistics and freight cost volatility –0.5% Global Short-term (≤2 yr)
Competition from synthetic insulation foams –0.6% North America, Europe Medium-term (2–4 yr)
Dust-exposure occupational health regulations –0.3% Europe, North America Long-term (≥4 yr)
Limited awareness in emerging markets –0.4% Africa, South America Long-term (≥4 yr)
Energy-intensive expansion process –0.3% Global Medium-term (2–4 yr)


Logistics and Freight Cost Volatility

Raw perlite ore is mined primarily in Turkey, Greece, and the western United States, creating long supply chains to end-use markets in the Asia-Pacific and the Middle East. Container-freight indices surged 174% during 2021–2022, compressing distributor margins and inflating landed costs for industrial mineral products. Although rates have normalized, route-specific surcharges remain elevated on Red Sea corridors, affecting the delivered pricing of volcanic glass minerals for Gulf-state LNG projects [13].

Competition from Synthetic Insulation Foams

Extruded polystyrene (XPS) and polyisocyanurate (PIR) boards continue to capture share in high-performance wall assemblies where space constraints penalize thicker perlite insulation solutions. XPS manufacturers have invested over USD 1.2 billion collectively in low-GWP blowing-agent conversion, partially neutralizing the environmental advantage that fire-resistant materials derived from perlite historically held. The Perlite Market must accelerate product-innovation cycles to defend its position in premium construction insulation materials [14].

Occupational Health Regulations

Expanded perlite processing facilities are subject to extra engineering controls due to OSHA's planned modification of the permissible-exposure limit for respirable dust, which targets 25 μg/m³ for crystalline silica. Wet-suppression and ventilation modifications can cost up to $50,000 per production line for compliance, which disproportionately burdens small-to-mid-size processors and limits capacity increases in the Perlite Market [15].

Perlite Market Opportunities

Controlled-Environment Agriculture Expansion

Vertical-farming revenue is forecast to exceed USD 20 billion by 2030, per BloombergNEF. Horticultural perlite's sterile, pH-neutral profile makes it the substrate of choice for hydroponic and aeroponic systems, where soil conditioning materials must deliver precise aeration and moisture retention. Early movers offering pre-blended perlite-coir-zeolite mixes can capture premium pricing in this segment [8].

Cryogenic Insulation for Hydrogen Economy

As governments allocate over USD 100 billion to green-hydrogen infrastructure by 2030 [IEA, 2024], liquid-hydrogen storage tanks require lightweight aggregates capable of performing at –253 °C. Perlite insulation already dominates LNG cryogenics; extending certification to hydrogen specifications creates a high-margin adjacency. Companies investing in ultra-fine-grade expanded perlite for hydrogen dewars will lead this transition within the Perlite Market [11].

Data Monetization via Smart-Mining Platforms

IoT sensors are being used by Turkish and American perlite manufacturers to collect data on particle-size distribution, moisture content, and thermal-expansion ratios during ore-body drilling and kiln-expansion processes. Subscription-based digital services are supported, and premium positioning for industrial mineral products is made possible by monetizing this operational data through predictive-quality dashboards [10].

Emerging-Market Penetration in Sub-Saharan Africa

Ethiopia's Rift Valley hosts unexploited volcanic glass mineral reserves with an estimated 50 million tonnes of raw perlite ore. With affordable-housing programs across Kenya, Nigeria, and Tanzania targeting 3 million units by 2030, local perlite expansion capacity could displace imported construction insulation materials and compress delivered costs by 30–40% [16].

Cosmetics and Personal-Care Filtration

The global clean-beauty movement, valued at USD 12 billion in 2024, is driving demand for mineral-origin filtration aids that replace diatomaceous earth in cosmetic manufacturing. Perlite's low heavy-metal content and consistent particle geometry position it as a preferred filter aid for water-based formulations, unlocking a new application corridor for the Perlite Market [7].

Perlite Market Future Outlook

Decarbonization and Net-Zero Building Envelopes

The Global Alliance for Buildings and Construction targets a 50% reduction in building-sector emissions by 2030. Perlite insulation delivers among the lowest embodied-carbon footprints of any mineral insulation — approximately 0.9 kg CO₂-eq per functional unit compared with 3.2 kg for XPS. As Scope 3 reporting mandates expand under ISSB standards, construction insulation materials with transparent life-cycle data will capture specification preference, benefiting the Perlite Market throughout the decade [2][17].

Precision Agriculture and Substrate Innovation

BloombergNEF projects that the controlled-environment agriculture sector will attract USD 45 billion in cumulative investment by 2035. Horticultural perlite blended with biochar and coco-coir is emerging as the next-generation substrate, offering superior water-use efficiency for drought-prone growing regions. Producers investing in engineered soil conditioning materials tailored to specific crop profiles — from leafy greens to medicinal cannabis — will command premium margins [8].

Hydrogen Economy and Next-Generation Cryogenics

The IEA's Net Zero Roadmap anticipates 150 million tonnes of clean-hydrogen production by 2050, requiring massive liquid-hydrogen storage capacity. Expanded perlite remains the only commercially proven insulation for cryogenic temperatures below –200 °C, giving the Perlite Market a defensible position in hydrogen-economy infrastructure. Supply agreements between perlite producers and electrolyzer OEMs are expected to be formalized by 2028 [11][3].

Circular Economy and Waste-Stream Integration

Spent perlite from filtration aids applications is increasingly recycled into lightweight aggregates for road sub-base and green-roof substrates. The EU's Circular Economy Action Plan incentivizes mineral-waste reuse, potentially converting a disposal cost into a revenue stream for industrial mineral products processors. Companies that establish take-back programs and closed-loop supply chains will strengthen their competitive moat in the Perlite Market [17][9].

Regional Market Share Analysis

Region Key Metric Primary Investment Themes
Asia-Pacific 44.8% revenue share (2025) Urban infrastructure, fire-resistant materials, greenhouse expansion
Europe 6.15% CAGR (2026–2035) EPBD compliance, peat-replacement, perlite insulation retrofits
North America USD 0.56 Billion (2025) Cryogenic storage, filtration aids, and lightweight aggregates in commercial buildings
South America 4.85% CAGR (2026–2035) Affordable housing, soil conditioning materials for agribusiness
Middle East & Africa USD 0.15 Billion (2025) LNG terminal insulation, volcanic glass minerals exploration
Total USD 2.62 Billion (2025) —

The Perlite Market exhibits distinct regional demand patterns, shaped by construction cycles, agricultural practices, and industrial-process requirements. Asia-Pacific leads overall revenue, while Europe's regulatory environment creates premium pricing for construction insulation materials and horticultural perlite.


North America

Country Key Metric Key Driver
US 72.5% of regional share Expanded perlite in cryogenic LNG terminals and commercial insulation
Canada 5.05% CAGR Green-building codes in British Columbia and Ontario
Mexico USD 0.04 Billion Social-housing programs driving lightweight aggregates uptake


North America's Perlite Market benefits from vertically integrated supply chains anchored by domestic ore deposits in New Mexico, Arizona, and Oregon. The U.S. DOE's Better Buildings Initiative has directed USD 1.5 billion toward envelope-upgrade demonstrations that specify expanded perlite loose-fill, while Canada's National Building Code 2025 revision raises minimum R-values for roof assemblies, catalyzing demand for perlite insulation boards [4][2].

Europe

Country Key Metric Key Driver
Germany 5.95% CAGR Energiewende retrofit mandates; industrial mineral products demand
UK 18.2% of regional share Social-housing insulation programs
France USD 0.08 Billion RE2020 building regulation compliance
Italy 5.75% CAGR Seismic-retrofit programs using fire-resistant materials
Spain USD 0.05 Billion Horticultural perlite in the Almería greenhouse cluster
Nordic Countries 4.90% CAGR Passive-house standards and soil conditioning materials
Russia USD 0.04 Billion Domestic ore processing for construction insulation materials
Rest of Europe 4.65% CAGR Eastern European housing modernization


Europe's Perlite Market is driven by the continent's aggressive decarbonization timeline. Greece remains the EU's primary ore source, supplying approximately 60% of intra-European volcanic glass minerals trade. The EPBD recast requires all member states to adopt minimum energy-performance certificates by 2028, creating a regulatory floor for expanded perlite consumption in exterior wall and roof systems [2][9].

Asia-Pacific

Country Key Metric Key Driver
China 38.5% of regional share Massive urban-renewal and high-rise construction programs
India 7.15% CAGR Affordable-housing targets and horticultural perlite in poly-houses
Japan USD 0.09 Billion Seismic-resilient fire-resistant materials codes
South Korea 6.45% CAGR Green New Deal building-envelope standards
ASEAN USD 0.11 Billion Emerging greenhouse agriculture; lightweight aggregates imports
Rest of Asia-Pacific 5.85% CAGR Infrastructure spending across Central Asia


Asia-Pacific dominates the Perlite Market with the largest revenue share and fastest regional CAGR. China's perlite deposits in Hebei and Henan provinces supply local kiln-expansion operations, while Turkey exports significant volumes to India and Southeast Asia. India's controlled-environment agriculture area grew 35% between 2022 and 2025, lifting demand for soil conditioning materials and positioning horticultural perlite as a structural growth driver [6][8].

South America

Country Key Metric Key Driver
Brazil 58.3% of regional share Social-housing programs; expanded perlite in block manufacturing
Argentina 4.95% CAGR Perlite insulation for cold-storage facilities in Patagonia
Rest of South America USD 0.03 Billion Mining-sector demand for filtration aids


South America's Perlite Market is nascent but accelerating. Brazil's Minha Casa Minha Vida program specifies lightweight aggregates in concrete masonry for thermal comfort, while Argentina's growing wine industry increases consumption of filtration aids for oenological processing [16][7].

Middle East & Africa

Country Key Metric Key Driver
Saudi Arabia 35.4% of regional share NEOM and Jeddah Tower projects require fire-resistant materials
UAE 6.55% CAGR Green-building codes in Abu Dhabi and Dubai
South Africa USD 0.02 Billion Mining-process filtration and industrial mineral products
Egypt 5.25% CAGR New Administrative Capital construction insulation materials
Rest of MEA USD 0.03 Billion Exploration of volcanic glass mineral deposits in East Africa


The Middle East & Africa Perlite Market is concentrated around Gulf-state mega-projects and LNG infrastructure. Saudi Arabia's Vision 2030 allocates over USD 500 billion to construction, with the expanded use of expanded perlite in precast panels for fire resistance. Ethiopia and Kenya are evaluating local ore deposits that could reshape supply dynamics for the region [16][11].

Perlite Market By Region, 2025-2035

Perlite Market Segmentation

By Product Type

Segment Key Metric Primary Demand Driver
Expanded Perlite 62.5% market share (2025) Construction insulation materials and horticultural substrates
Agro-Perlite USD 0.47 Billion (2025) Greenhouse soil conditioning materials
Vapex & Specialty Grades 5.85% CAGR (2026–2035) Cryogenic insulation, cosmetic filtration aids


Expanded perlite continues to dominate the Perlite Market by product type, serving as the workhorse material across construction, horticulture, and industrial applications. Its cellular structure — formed when volcanic glass minerals are heated above 870 °C — creates a lightweight, non-combustible aggregate with thermal conductivity values competitive against synthetic alternatives. Global kiln capacity exceeded 4.5 million tonnes in 2024, with Turkey accounting for roughly 40% of raw ore supply[5].

Vapex & Specialty Grades represent the fastest-growing segment, driven by precision filtration aids for pharmaceutical, food-processing, and craft-beverage applications. These grades undergo proprietary surface treatment to achieve targeted particle-size distributions, enabling higher margin realization. Demand for fire-resistant materials rated to 1,260 °C is expanding within steel and petrochemical refractory lining, further broadening the application base for the Perlite Market [7][9].

By Application

Segment Key Metric Primary Demand Driver
Insulation 40.1% market share (2025) Energy-efficiency codes for construction insulation materials
Fire-Proofing & Refractory USD 0.39 Billion (2025) Industrial fire-resistant materials regulations
Soil Amendment & Horticulture 5.45% CAGR (2026–2035) Peat-replacement mandates driving horticultural perlite
Filtration USD 0.22 Billion (2025) Craft-beverage and pharmaceutical filtration aids
Others 4.35% CAGR (2026–2035) Cosmetics, cryogenics, and specialty uses


Insulation remains the largest application within the Perlite Market, reflecting the global shift toward energy-efficient building envelopes that rely on lightweight aggregates. Perlite insulation products — loose-fill, board, and pipe cover — are specified in commercial, residential, and industrial settings where non-combustibility is mandatory. The segment benefits from regulatory tailwinds in both Europe and North America [2].

Soil amendment and horticulture ranks as the fastest-growing application, propelled by the EU's peat-phase-out timeline and expanding greenhouse acreage in the Asia-Pacific. Horticultural perlite improves root-zone aeration, reduces overwatering risk, and is fully inert, making it compatible with organic certification standards. As vertical-farming operators scale production, demand for soil conditioning materials engineered for hydroponic channels is rising [8].

By End-Use Industry

Segment Key Metric Primary Demand Driver
Construction & Infrastructure USD 1.01 Billion (2025) Lightweight aggregates for floor screeds, roof insulation, and masonry fill
Horticulture & Agriculture 5.55% CAGR (2026–2035) Horticultural perlite replacing peat and vermiculite
Industrial Manufacturing 15.8% market share (2025) Filtration aids and refractory applications
Others USD 0.18 Billion (2025) Cosmetics, cryogenics, pharmaceuticals


Construction & infrastructure is the largest end-use industry in the Perlite Market, consuming expanded perlite in applications ranging from underfloor heating screeds to cavity-wall fill. The sector's scale ensures baseline demand even during cyclical downturns, while tightening building codes create incremental volume growth for construction insulation materials [6].

Horticulture & agriculture is the fastest-growing end-use industry, as commercial growers transition to perlite-based substrates. Industrial manufacturing maintains a stable share through consistent demand for filtration aids in beverage, pharmaceutical, and chemical processing, alongside refractory-grade volcanic glass minerals for steelmaking [7].

Competitive Benchmarking

The Perlite Market exhibits medium concentration, with an estimated HHI below 1,200 and the top five players collectively capturing approximately 35–40% of global revenue. The landscape is fragmented across regional processors, particularly in Turkey, Greece, and the U.S., where proximity to ore deposits confers logistics advantages. Competition centers on kiln-expansion capacity, particle-size consistency, and application-specific grading for industrial mineral products.

Company Est. Revenue Share Range Key Offerings for Perlite Market Strategic Positioning
Imerys S.A. ~7–10% Expanded perlite, filtration aids, specialty grades Vertically integrated; global distribution network
Keltech Energies (Keltec Group) ~4–6% Horticultural perlite, construction insulation materials Leading Indian processor; Asia-Pacific expansion
Aegean Perlites S.A. ~4–6% Raw and expanded perlite, lightweight aggregates Greek ore access; Mediterranean distribution
Termolita S.A. ~3–5% Perlite insulation boards and loose-fill South American market leader
Cornerstone Industrial Minerals ~3–5% Expanded perlite for horticulture and construction U.S. processing; vertically integrated supply
Supreme Perlite Company ~3–4% Construction and filtration-grade expanded perlite Pacific Northwest ore deposits
Silbrico Corporation ~2–4% Specialty horticultural perlite, soil conditioning materials Niche focus: branded retail products
Dicalite Management Group ~3–5% Filtration aids, industrial mineral products Diversified minerals portfolio
EP Minerals (U.S. Silica) ~2–4% Filtration and functional-filler perlite grades Integration with broader silica operations
Perlite Hellas ~2–3% Raw perlite ore, expanded perlite Greek ore reserves; EU supply chain


Recent News & Developments

  • Imerys S.A. (January 2025): Acquired Chemviron’s European perlite and diatomite assets, expanding its manufacturing footprint in France and Italy to strengthen its filtration and life sciences market segments [5].
  • Dicalite Management Group (January 2026 Upgraded processing systems and expanded active mining operations at its North American facilities to scale output capacity and meet high demand for perlite and diatomaceous earth filtration products. [7].


Perlite Market Report Scope

Parameter Detail
Market Scope Global Perlite Market covering product types, applications, end-use industries, and five geographic regions
Study Period 2021–2035
CAGR (Forecast) 5.25% (2026–2035)
Base Year Market Size USD 2.62 Billion (2025)
Forecast End Market Size USD 4.38 Billion (2035)
Fastest Growing Segment Vapex & Specialty Grades (by product type); Horticulture & Agriculture (by end-use)
Companies Profiled 10 (Imerys, Keltech Energies, Aegean Perlites, Termolita, Cornerstone Industrial Minerals, Supreme Perlite, Silbrico, Dicalite, EP Minerals, Perlite Hellas)
Valuation Currency USD Billion

FAQs

What raw-material sourcing risks should buyers evaluate before signing long-term perlite supply contracts?
Turkey supplies roughly 70% of globally traded raw ore, creating concentration risk if export tariffs or geopolitical disruptions interrupt shipments. Buyers should negotiate multi-origin clauses covering Greek, U.S., and emerging East African volcanic glass minerals deposits to hedge supply exposure [4].
How does expanded perlite compare with aerogel insulation on a cost-per-R-value basis for commercial buildings?
Expanded perlite delivers R-values of 2.5–3.5 per inch at roughly one-fifth the installed cost of aerogel blankets. Aerogel offers higher R-per-inch but remains cost-prohibitive for large-area cavity fill, where perlite insulation excels [2].
What quality-control certifications should procurement teams require from perlite suppliers?
ISO 9001 and EN 13055 certification for lightweight aggregates are baseline requirements. For filtration aids, NSF/ANSI 61 certification confirms potable-water-contact compliance, while REACH registration is mandatory for EU-destined industrial mineral products [12].
How is the Perlite Market adapting to tightening carbon-disclosure requirements under ISSB standards?
Leading producers now publish Environmental Product Declarations quantifying cradle-to-gate emissions for expanded perlite. Buyers specifying construction insulation materials with verified EPDs gain LEED and BREEAM credit advantages [17].
What logistics strategies minimize delivered cost for horticultural perlite in landlocked regions?
Regional expansion-kiln partnerships reduce freight by shipping raw ore in dense form and expanding locally. This model cuts the delivered cost of soil conditioning materials by 30–40% compared with importing pre-expanded product [13].
Can spent filtration perlite be reused, and does recycling affect performance in the Perlite Market?
Spent perlite from beverage filtration aids retains 85–90% of its structural integrity after thermal regeneration. Recycled grades serve effectively in lightweight aggregates for green-roof substrates and road sub-base applications [17].
What differentiates food-grade perlite from construction-grade perlite for procurement specification purposes?
Food-grade perlite must meet FDA 21 CFR 177.2600 purity thresholds and carry NSF certification for direct contact. Construction-grade volcanic glass minerals prioritize bulk density and thermal performance over heavy-metal limits [12].    
Author
Author Author Profile Chitranshi Jaiswal LinkedIn Team Lead - Research
Chitranshi is a Team Leader in the Chemicals & Materials (CnM) and Energy & Power (EnP) domains, with 6+ years of experience in market research. She leads and mentors teams to deliver cross-domain projects that equip clients with actionable insights and growth strategies. She is skilled in market estimation, forecasting, competitive benchmarking, and both primary & secondary research, enabling her to turn complex data into decision-ready insights. An engineer and MBA professional, she combines technical expertise with strategic acumen to solve dynamic market challenges. Chitranshi has successfully managed projects that support market entry, investment planning, and competitive positioning, while building strong client relationships. Certified in Advanced Excel & Power BI she leverages data-driven approaches to ensure accuracy, clarity, and impactful outcomes.
Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.

















