Payroll Outsourcing Market Summary
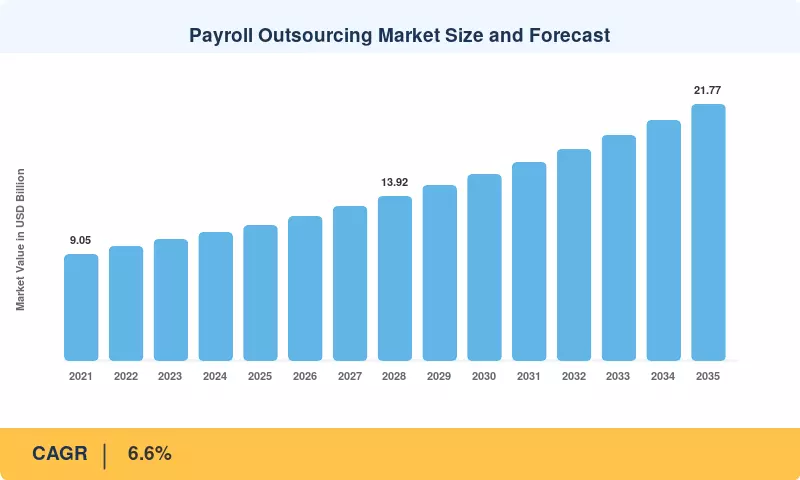
The Payroll Outsourcing Market was valued at USD 11.49 Billion in 2025 and is projected to grow from USD 12.25 Billion in 2026 to USD 21.77 Billion by 2035, a CAGR of 6.6% over 2026–2035. Two regulatory catalysts set the near-term pace. The EU Pay Transparency Directive (2023/970) required member states to transpose gender pay-gap reporting rules by June 2026 [1]. India's four labour codes, effective November 2025, consolidated 29 central labour laws and redefined the wage base for statutory contributions [2]. Both changes push employers toward specialist providers that absorb rule updates at scale.
A transition in the platform is the driving force behind the expansion. Cloud-native, multi-country platforms with API connections to HCM, ERP, and time-tracking systems are replacing legacy on-premises payroll engines, spreadsheet reconciliations, and country-by-country bureau contracts. The direction is confirmed by consolidation capital: In April 2025, Paychex completed its acquisition of Paycor for approximately USD 4.1 billion [7]. In August 2025, Thoma Bravo agreed to acquire Dayforce for approximately USD 12.3 billion [9]. Buyers now acquire managed payroll services as subscription bundles, as opposed to standalone processing contracts.
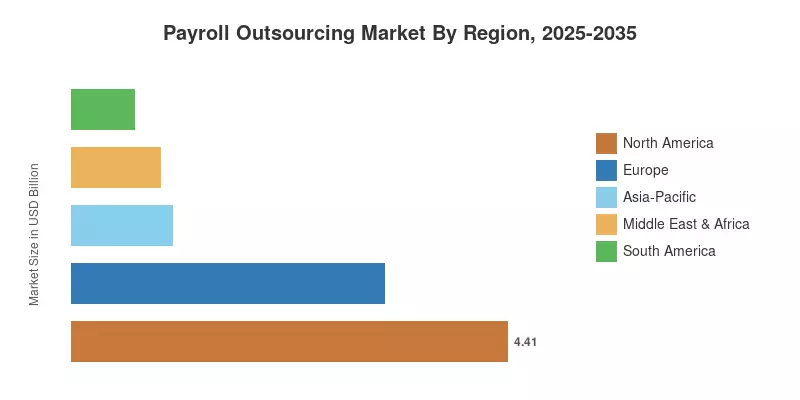
The Payroll Outsourcing Market is dominated by North America, which has a 38.4% share in 2025. This position is bolstered by a concentrated provider base and the complexity of multi-state taxes. India's labor code implementation and multinational expansion across ASEAN are the primary drivers of Asia-Pacific's 8.9% CAGR. Europe is the second-ranked region, with contract renewals being driven by real-time statutory filing and pay transparency reporting. Providers that combine a singular data model across countries with local compliance depth are most likely to increase their market share through 2035.
Key Report Takeaways
• By Service Type
- Hybrid arrangements held a 61.9% share of the Payroll Outsourcing Market in 2025, as employers keep data validation in-house while handing off calculation and filing.
- Fully Outsourced contracts are expanding at a 7.8% CAGR as confidence in vendor controls improves.
• By Deployment Model
- Cloud-Based delivery accounted for 84.9% of 2025 revenue and is the default for new deals.
- On-premises/Hosted deployments are growing at just 1.4% CAGR, concentrated in defense, energy and public-sector accounts.
• By Enterprise Size
- Large Enterprises contributed 59.1% of 2025 billings.
- SMEs are the fastest-growing buyer group in the Payroll Outsourcing Market, advancing at an 8.9% CAGR.
• By End-User Vertical
- BFSI led with a 26.8% share, reflecting strict audit trails and multi-entity structures.
- Healthcare and Life Sciences is the fastest-rising vertical at a 9.0% CAGR.
• By Payroll Component
- Core Pay-Run remained the entry point with a 41.3% share.
- Analytics & Reporting is the fastest-growing component at a 10.4% CAGR.
• By Region
- North America led with a 38.4% share in 2025.
- Europe generated USD 3.17 billion in 2025.
- Asia-Pacific is forecast to grow at an 8.9% CAGR.
Market Size and Forecast (2021–2035)
Market Research Future sized the Payroll Outsourcing Market through a bottom-up build of provider revenues from payroll processing, statutory filing and bundled payroll modules, cross-checked against employer headcount data from labour statistics agencies [5][6] and disclosures in provider annual reports [23][24]. Historical values reflect reported revenue; forecast values apply segment-level growth assumptions validated through primary interviews with buyers and vendors.




 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA



