Passwordless Authentication Market (2026 - 2035)

Passwordless Authentication Market Size, Share and Research Report By Component (Hardware, Software/Platform, Services), By Authentication Method (Biometrics, Passkeys, Token-based (FIDO2 Security Keys), Push Notification and Magic Link, Smart Card and PKI), By Deployment Mode (On-Premises, Cloud, Hybrid), By Organization Size (Small and Medium Enterprises, Large Enterprises), By End-User Industry (BFSI, IT and Telecom, Healthcare, Government and Defense, Retail and E-commerce, Manufacturing, Others) - Industry Forecast to 2035.
ID: MRFR/ICT/22639-HCR 100 Pages Ankit Gupta Last Updated: October 13, 2026
Passwordless Authentication Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)16.9%
2025 Market SizeUSD 22.40 Billion
2035 Market SizeUSD 110.14 Billion
Key Players
Microsoft
Okta
Cisco
Ping Identity
Thales
HID Global
Opportunities
  • Mobile-First Emerging Markets
  • Passwordless-as-a-Service Through MSPs
  • Wallet-Based Authentication for Regulated Services

Passwordless Authentication Market Summary

The global Passwordless Authentication Market was valued at USD 22.40 Billion in 2025 and is forecast to reach USD 27.00 Billion in 2026, climbing to USD 110.14 Billion by 2035 at a CAGR of 16.9% over 2026–2035. Two policy catalysts anchor this trajectory. U.S. federal agencies operate under OMB Memorandum M-22-09, which requires phishing-resistant multi-factor authentication across agency systems [2], while the EU's eIDAS 2.0 regulation obliges every member state to offer citizens a European Digital Identity Wallet by late 2026 [3]. Both mandates push buyers toward cryptographic credentials rather than shared secrets.

Legacy password databases, SMS one-time codes, and knowledge-based security questions are being retired in favor of public-key credentials bound to devices or synced across ecosystems. The economics are hard to ignore: IBM puts the average cost of a data breach at USD 4.88 million [6], and Verizon traces roughly 31% of breaches over the past decade to stolen credentials [5]. Platform owners have responded. Google made passkeys the default sign-in option in 2023 [8], and Microsoft followed with passwordless-by-default accounts in 2025 [9].

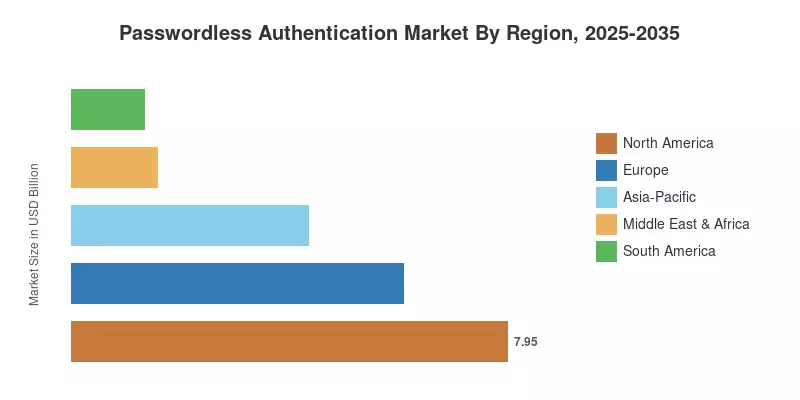
North America leads with a 35.5% revenue share, supported by federal zero-trust deadlines and dense enterprise identity spending. Asia-Pacific is the fastest-growing region at a 19.3% CAGR, propelled by national digital ID programs in India, Japan, and Singapore. Europe ranks second, with demand shaped by eIDAS 2.0 and strong customer authentication rules in payments. Over the next decade, regional leadership will hinge less on budgets and more on how quickly governments convert identity mandates into enforceable deadlines.

Key Report Takeaways

• By Component

  • Software/Platform held a 66.5% share of the Passwordless Authentication Market in 2025, anchored by identity suites embedded in enterprise security stacks
  • Services will post an 18.0% CAGR through 2035 as integration and adoption expertise become the main determinant of project ROI

• By Authentication Method

  • Biometrics accounted for a 45.8% share in 2025, driven by fingerprint and face sensors in nearly every modern smartphone
  • Passkeys are the fastest-growing method at an 18.3% CAGR, aided by cross-platform credential sync

• By Deployment Mode

  • Cloud led with a 52.9% share in 2025 because SaaS removes server maintenance and speeds patching
  • Hybrid deployments will expand at a 19.8% CAGR as data-residency rules keep signing keys on-premises

• By Organization Size

  • Large Enterprises represented a 58.4% share in 2025, reflecting budgets for enterprise-wide identity transformation
  • Small and Medium Enterprises will grow at an 18.8% CAGR, the steepest organizational curve in the Passwordless Authentication Market

• By End-User Industry

  • BFSI captured a 26.3% share in 2025, reflecting strict regulatory scrutiny of authentication failures
  • Retail and E-commerce will record an 18.1% CAGR as frictionless checkout directly lifts conversion

• By Region

  • North America held a 35.5% revenue share in 2025
  • Asia-Pacific will grow at a 19.3% CAGR, the fastest of any region
  • Europe generated USD 6.05 billion in 2025, shaped by digital wallet obligations

Market Size and Forecast (2021–2035)

Our estimates for the Passwordless Authentication Market combine vendor revenue disclosures, procurement records from public-sector tenders, and more than 350 interviews with identity architects, CISOs, and channel partners. Historical values for 2021–2024 were reconstructed bottom-up from company filings and validated top-down against enterprise security spending. Forecast years apply scenario-weighted adoption curves by segment and region, then reconcile to the global total.
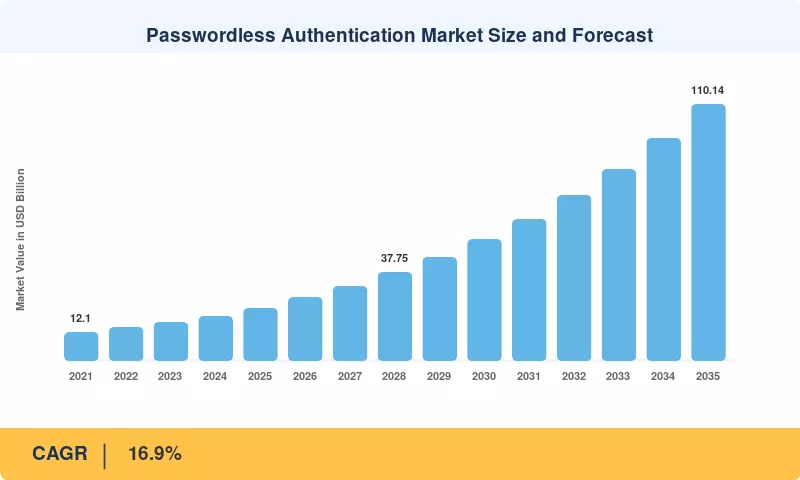
Passwordless Authentication Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Phishing-resistant MFA mandates +3.4% North America, Europe Medium-term (2–4 yr)
Escalating credential-based breach costs +3.0% Global Short-term (≤2 yr)
Platform-wide passkey support +2.8% Global Short-term (≤2 yr)
Zero-trust architecture adoption +2.2% North America, Europe, Asia-Pacific Medium-term (2–4 yr)
National digital ID and wallet programs +1.9% Europe, Asia-Pacific Long-term (≥4 yr)
Checkout conversion and payment security rules +1.5% Asia-Pacific, North America Medium-term (2–4 yr)
Helpdesk cost reduction +1.4% Global Short-term (≤2 yr)

Phishing-Resistant MFA Mandates

Instead of endorsing MFA, federal policy now specifies which types qualify. Agencies are instructed by OMB M-22-09 to use phishing-resistant techniques, thereby eliminating SMS codes and push approvals that can be socially engineered by attackers [2]. The only completely phishing-resistant choices are FIDO and PKI-based credentials, according to CISA's guidelines [14]. The mandate spills throughout supply chains for defense, healthcare, and IT services since federal contractors inherit these expectations through procurement clauses, expanding the addressable base well beyond government.

Escalating Credential-Based Breach Costs

Stolen credentials remain the attacker's cheapest entry point. Verizon attributes about 31% of breaches over ten years to compromised credentials [5], and IBM reports a USD 4.88 million average breach cost in 2024 [6]. Microsoft observed roughly 7,000 password attacks per second across its services [7]. These figures give CISOs a quantifiable case: removing the password removes the asset that phishing kits and credential-stuffing tools are built to harvest, which shortens the payback period on deployment.

Platform-Wide Passkey Support

Consumer readiness has largely been solved by operating system vendors. The FIDO Alliance reported in late 2024 that more than 15 billion online accounts could use passkeys [1]. Google made passkeys the default sign-in for personal accounts in 2023 [8], and Microsoft set new accounts to passwordless by default in 2025 [9]. Enterprises now inherit user familiarity at no training cost, which removes the adoption barrier that stalled earlier hardware-token programs.

Zero-Trust Architecture Adoption

Strong identity is the first control point in zero-trust models, which validate each request instead of relying on network location. Identity is presented by M-22-09 as the cornerstone of the government zero-trust approach [2]. Similar maturity models are used by private sector initiatives, which enable ongoing, risk-based access decisions by substituting device-bound credentials for passwords. As customers centralize identity and access tooling around zero-trust roadmaps, vendors who link authentication signals to device posture and session risk gain market share.

National Digital ID and Wallet Programs

Governments are building identity infrastructure that private services can reuse. Regulation (EU) 2024/1183 requires member states to provide digital identity wallets and obliges large platforms to accept them [3]. Japan enabled My Number Card functions on iPhone in June 2025 [11], and India's Aadhaar face authentication exceeded 100 million monthly transactions during 2025 [12]. Each program normalizes cryptographic, biometric-backed sign-in for hundreds of millions of citizens.

Checkout Conversion and Payment Security Rules

Payment regulators are tightening authentication while merchants push for lower friction. PCI DSS v4.0 extended MFA requirements to all access into cardholder data environments from March 2025 [10]. India's central bank issued directions in 2025 allowing alternative authentication factors beyond SMS OTP for digital payments, effective 2026 [20]. Passkeys satisfy both sides: strong cryptographic assurance with a single biometric gesture, which reduces cart abandonment linked to failed codes.

Helpdesk Cost Reduction

Password resets remain a persistent operational cost. Estimated a single reset costs organizations roughly USD 70 in labor [23], and resets often represent a large share of service desk tickets. Eliminating passwords removes forgotten-credential tickets and lockout escalations, freeing IT staff for higher-value work. CFOs increasingly accept passwordless projects on operational savings alone, independent of breach-avoidance arguments.

Restraints Impact Analysis

Restraint impacts are directional estimates of downward pressure on the forecast CAGR. They overlap with one another and with drivers, so they are not additive and represent analyst judgment informed by interviews and deployment data.

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
Legacy application integration complexity −2.1% Global Medium-term (2–4 yr)
Account recovery and device loss risk −1.6% Global Short-term (≤2 yr)
Biometric privacy regulation −1.3% North America, Europe Long-term (≥4 yr)
Upfront cost for smaller organizations −1.1% South America, Middle East & Africa Medium-term (2–4 yr)
Interoperability fragmentation across ecosystems −0.9% Global Short-term (≤2 yr)

Legacy Application Integration Complexity

Many enterprise applications still authenticate through LDAP binds, RADIUS, or hard-coded credential prompts that cannot accept FIDO assertions. Cisco Duo's research shows a persistent long tail of older operating systems and unsupported endpoints across enterprise fleets [22]. Bridging these systems requires proxies, gateways, or application rewrites, which extend project timelines and push some organizations to keep passwords as fallback indefinitely.

Account Recovery and Device Loss Risk

Device-bound credentials create a recovery problem: lose the phone or key, and the user loses access. Weak recovery flows, such as email links or helpdesk resets, can reintroduce the very phishing exposure passwordless was meant to remove. NIST SP 800-63-4 places explicit requirements on account recovery for higher assurance levels [4], forcing vendors and buyers to invest in identity-proofing workflows before retiring passwords.

Biometric Privacy Regulation

There is increased legal risk associated with biometric data. GDPR views biometrics as special-category data, while Illinois' Biometric Information Privacy Act offers a private right of action with statutory damages per violation [18]. as the majority of passwordless designs maintain templates on-device, legal teams often cause approvals to be delayed as they check data flows, which prolongs procurement cycles in North America and Europe by several months.

Upfront Cost for Smaller Organizations

Hardware security keys, identity platform licenses, and integration services carry costs that strain smaller firms in price-sensitive regions. Yubico's disclosures show hardware keys still command premium per-unit pricing relative to software authenticators [21]. Without managed service bundles, many SMEs in South America and Africa defer projects, relying instead on free authenticator apps with weaker assurance.

Interoperability Fragmentation Across Ecosystems

Passkeys synced inside one vendor ecosystem do not always move cleanly to another. Cross-platform credential exchange specifications from the FIDO Alliance are still maturing [1], and users switching between Android, iOS, and Windows can encounter inconsistent prompts. These rough edges raise support volumes during early rollouts and make some IT teams cautious about mandating passkeys for mixed-device workforces.

Passwordless Authentication Market Opportunities

Vendors that align product roadmaps with the following gaps can capture outsized share of incremental growth in the Passwordless Authentication Market.

Mobile-First Emerging Markets

Roughly 850 million people worldwide lack official identification, according to the World Bank's ID4D initiative [13], yet many own smartphones with biometric sensors. Vendors that pair low-cost biometric enrollment with national ID verification can serve banks, telecom operators, and government agencies in India, ASEAN, and Africa that skip password-centric architectures entirely.

Passwordless-as-a-Service Through MSPs

Managed service providers can bundle passwordless authentication with endpoint management and backup for a flat monthly fee per user. This subscription model converts a capital project into an operating expense, matching how SMEs buy IT. Vendors offering multi-tenant consoles, usage-based billing, and white-label options will gain distribution reach far beyond direct sales.

Wallet-Based Authentication for Regulated Services

Once EU digital identity wallets are live, banks, insurers, and telecom operators will need relying-party integrations that accept wallet credentials for onboarding and login [3]. Integrators that build certified connectors and verifiable-credential verification services early can monetize each relying-party onboarding, creating a recurring transaction-based revenue stream.

Workforce and Operational Technology Identities

Manufacturing plants, hospitals, and logistics hubs run shared terminals and OT consoles where passwords are often written on tape. Badge-tap and roaming-key authentication can secure these environments while speeding shift changes. Combining human and machine identity governance in one platform addresses a segment that consumer-focused vendors have largely ignored.

Fraud Analytics on Authentication Signals

Device, attestation, and behavioral telemetry are generated by each passwordless login. Risk intelligence can be sold as a premium add-on to payments and e-commerce clients by vendors who combine anonymized signals into consortia fraud-risk scores. As long as privacy-preserving safeguards meet regulatory requirements, the paradigm transforms authentication from a cost center into a data product.

Passwordless Authentication Market Future Outlook

The next decade will reshape the Passwordless Authentication Market around four themes that extend beyond simply removing passwords.

AI-Driven Adaptive Authentication

Authentication will shift from a single event at login to continuous risk scoring across the session. Machine learning models will weigh device attestation, location, and behavior to step up or relax assurance in real time. Microsoft's observation of thousands of password attacks per second [7] shows the volume problem AI must handle. Vendors with large telemetry pools will hold a structural advantage in model accuracy.

Deepfake and Injection Attack Defense

Generative AI lowers the cost of synthetic faces and voices, threatening remote biometric verification. Buyers will demand liveness detection, injection-attack resistance, and hardware attestation that proves a real sensor captured the sample. NIST SP 800-63-4 already addresses presentation-attack detection for biometrics [4]. Expect certification programs for liveness to become a procurement baseline by 2028.

Hyperscaler Bundling and Platform Economics

Cloud and operating system providers increasingly embed passkey technology at no incremental charge, compressing standalone pricing. Okta's filings highlight competition from bundled identity offerings [17]. Pure-play vendors will survive by specializing in regulated verticals, complex hybrid estates, and customer identity at scale. Consolidation through acquisition is likely as mid-tier vendors struggle to match bundled economics.

Convergence with Digital Wallets and Verifiable Credentials

Authentication and identity proofing will merge as wallets carry both login credentials and verified attributes such as age or licensure. The EU framework [3] and national programs in Asia [11][12] will drive relying parties to accept wallet presentations. By the early 2030s, onboarding, login, and authorization could occur through a single wallet interaction.

Regional Market Share Analysis

Region Metric Primary Investment Themes
North America 35.5% share Federal zero-trust deadlines, enterprise workforce passkeys, cyber insurance requirements
Europe USD 6.05 Billion eIDAS 2.0 wallets, payment authentication rules, data residency
Asia-Pacific 19.3% CAGR National digital ID, mobile payments, super-app authentication
South America 6.0% share Digital banking expansion, instant payment fraud controls
Middle East & Africa USD 1.57 Billion Government digital transformation, smart-city identity, mobile money
Total USD 22.40 Billion —

Regional growth in the Passwordless Authentication Market tracks the maturity of identity regulation, the density of enterprise security budgets, and the reach of national digital ID schemes.

North America

Country Metric Key Driver
US 82.0% share of region Federal mandates and large enterprise identity budgets
Canada 17.4% CAGR Open banking framework and provincial digital ID
Mexico USD 0.40 Billion Digital banking growth and payment fraud reduction

Federal requirements shape the region's demand profile. Agencies working toward M-22-09 targets [2] create reference architectures that contractors and state governments copy, while PCI DSS v4.0 enforcement pushes retailers and processors to upgrade authentication [10]. Canada's consumer-driven banking framework is prompting banks to adopt stronger customer authentication, and Mexican fintechs are deploying biometric login to curb account takeover in fast-growing digital wallets.

Europe

Country Metric Key Driver
Germany 22.5% share of region Strict data residency favoring hybrid deployments
UK USD 1.27 Billion Financial services modernization and public-sector identity
France 16.6% CAGR Government digital identity and payment security
Italy 8.4% share of region SPID and CIE public identity adoption
Spain USD 0.42 Billion Banking app biometric authentication
Nordic Countries 17.8% CAGR Mature national eID ecosystems
Russia 3.1% share of region Domestic vendor substitution
Rest of Europe USD 0.85 Billion EU wallet rollouts in Central and Eastern Europe

Regulation (EU) 2024/1183 is the single largest regional catalyst, requiring wallet availability and acceptance by major online platforms [3]. The European Commission's proposed Payment Services Regulation would tighten strong customer authentication and fraud liability [19], pushing banks toward device-bound credentials. Germany's data-residency expectations make hybrid models the default, while Nordic countries build on decades of bank-issued eID adoption.

Asia-Pacific

Country Metric Key Driver
China 34.0% share of region Super-app biometric payments and domestic standards
India 22.6% CAGR Aadhaar face authentication and payment rule changes
Japan USD 1.10 Billion My Number Card smartphone integration
South Korea 9.5% share of region Mobile ID and financial authentication reform
ASEAN 21.1% CAGR Bank SMS OTP phase-outs and digital ID programs
Rest of Asia-Pacific USD 0.55 Billion Australia's digital ID legislation and bank anti-scam measures

Government infrastructure drives the region's growth premium. India's Aadhaar platform supports massive biometric authentication volumes [12], and the RBI's 2025 directions open digital payments to alternatives beyond SMS OTP [20]. Singapore's major banks began phasing out SMS OTPs for account login in 2024 under guidance from MAS and the Association of Banks [25]. Japan's integration of My Number Card into iPhone [11] extends cryptographic identity to everyday consumer services.

South America

Country Metric Key Driver
Brazil 56.0% share of region Pix instant payments and open finance
Argentina 17.9% CAGR Digital banking adoption amid fraud growth
Rest of South America USD 0.35 Billion Fintech expansion in Colombia, Chile, and Peru

Brazil dominates regional spending as instant payments through Pix have raised the stakes of account takeover, pushing banks toward device binding and biometric confirmation. Argentina's banks face rising social-engineering fraud and are shifting customers to app-based biometric login. Across smaller markets, fintechs adopt cloud identity platforms from day one, avoiding legacy password infrastructure entirely.

Middle East & Africa

Country Metric Key Driver
Saudi Arabia 20.4% CAGR Vision 2030 digital government and banking
UAE 24.0% share of region UAE Pass national digital identity
South Africa USD 0.25 Billion Banking fraud prevention and POPIA compliance
Egypt 8.5% share of region Digital Egypt strategy and mobile wallets
Rest of MEA 15.8% CAGR Mobile money security in East and West Africa

Gulf states are building centralized digital identity platforms that private services reuse. The UAE Pass app links residents to hundreds of government and private services, while Saudi Arabia's digital government programs create demand for biometric-backed authentication in banking and public services. In sub-Saharan Africa, mobile money providers use biometrics to protect accounts for populations that ID4D data shows remain underserved by formal identity [13].

Passwordless Authentication Market By Region, 2025-2035

Passwordless Authentication Market Segmentation

By Component

Segment Metric Primary Demand Driver
Hardware USD 1.72 Billion FIPS-validated security keys for regulated and air-gapped environments
Software/Platform 66.5% share Identity suites anchoring enterprise security stacks
Services 18.0% CAGR Integration, recovery design, and user-adoption programs

Within the Passwordless Authentication Market, Software/Platform leads with a 66.5% share because identity suites from Microsoft and Okta sit at the center of access architecture. Services, growing at 18.0% CAGR, reflect a hard lesson from early rollouts: licenses alone rarely deliver results. Consultants connect passkeys to privileged-access vaults, design recovery flows, and run enrollment campaigns. Hardware remains a specialized niche, with security keys protecting administrators and FIPS-bound workloads.

By Authentication Method

Segment Metric Primary Demand Driver
Biometrics 45.8% share Ubiquitous smartphone fingerprint and face sensors
Passkeys 18.3% CAGR Cross-platform sync without hardware purchase
Token-based (FIDO2 Security Keys) USD 3.36 Billion Offline recovery and privileged-user protection
Push Notification and Magic Link 13.2% share Transitional step for lagging enterprises
Smart Card and PKI 11.2% CAGR Defense and critical infrastructure mandates

Method choice in the Passwordless Authentication Market is led by Biometrics at a 45.8% share, reflecting user preference for a glance or touch over typed codes. Passkeys expand fastest at 18.3% CAGR because synced credentials remove the cost and logistics of issuing hardware. Token-based keys hold firm among administrators, while push notifications persist as an interim step. Smart Card and PKI remain essential in defense and nuclear facilities.

By Deployment Mode

Segment Metric Primary Demand Driver
On-Premises USD 5.04 Billion Classified and defense environments
Cloud 52.9% share Lower maintenance and faster patching
Hybrid 19.8% CAGR Local key custody with cloud orchestration

Deployment preferences in the Passwordless Authentication Market favor Cloud, which holds a 52.9% share as SaaS removes server upkeep. Hybrid models grow fastest at 19.8% CAGR because German, Indian, and Gulf data-residency rules push organizations to keep signing keys local while consuming cloud policy engines. On-premises footprints persist in defense and sensitive R&D, though containerized FIDO servers running on Kubernetes are narrowing functional gaps with SaaS.

By Organization Size

Segment Metric Primary Demand Driver
Small and Medium Enterprises 18.8% CAGR Simplified cloud tiers and MSP bundles
Large Enterprises 58.4% share Enterprise-wide identity transformation budgets

Large Enterprises account for a 58.4% share of the Passwordless Authentication Market, as they have the staff and budgets to run organization-wide identity programs. Their deployments produced the templates vendors now pre-package for smaller buyers. Small and Medium Enterprises grow at 18.8% CAGR, helped by subscription tiers and managed providers that bundle authentication with endpoint management for less than the cost of one full-time administrator.

By End-User Industry

Segment Metric Primary Demand Driver
BFSI 26.3% share Regulatory penalties and account takeover losses
IT and Telecom USD 3.94 Billion SIM-swap fraud and developer access security
Healthcare 12.4% share Clinician workflow and patient data protection
Government and Defense 16.2% CAGR Zero-trust mandates and citizen portals
Retail and E-commerce 18.1% CAGR Checkout conversion and payment fraud
Manufacturing USD 1.97 Billion Shared terminals and OT zone access
Others 12.1% share Education, energy, and professional services

BFSI leads the Passwordless Authentication Market with a 26.3% share because regulators penalize weak authentication and fraud losses fall directly on institutions. Retail and E-commerce grow fastest at 18.1% CAGR, as passkeys at checkout cut abandonment tied to failed one-time codes. Healthcare adopts tap-and-go access to save clinician time, while government agencies deploy biometric portals for citizen services and manufacturers secure shared OT consoles.

Competitive Benchmarking

The Passwordless Authentication Market is moderately fragmented, with an estimated Herfindahl-Hirschman Index of roughly 650–800 and the top five vendors holding about 34–40% of revenue. Platform owners and identity suite vendors set the pace, hardware specialists defend regulated niches, and venture-backed pure-plays compete on developer experience and customer identity. Consolidation, illustrated by the Ping Identity and ForgeRock combination [16], continues to reshape the mid-tier.

Company Est. Revenue Share Range Key Offerings for Passwordless Authentication Market Strategic Positioning
Microsoft ~9–12% Entra ID passwordless, Windows Hello, Authenticator passkeys Bundled identity within cloud and productivity suites
Okta ~7–10% Workforce and Customer Identity, FastPass, passkey support Independent identity platform with broad integrations
Cisco (Duo) ~5–8% Duo Passwordless, device trust, risk-based access Security-stack bundling with network and endpoint signals
Ping Identity ~4–7% PingOne, DaVinci orchestration, ForgeRock platform Large-enterprise and hybrid deployment specialist
Thales ~4–6% SafeNet Trusted Access, FIDO devices, PKI Hardware-plus-software for regulated sectors
HID Global ~3–5% FIDO keys, smart cards, physical-logical access convergence Badge and credential leadership in workforce
Yubico ~3–5% YubiKey hardware security keys, enterprise subscriptions Phishing-resistant hardware standard bearer
IBM ~2–4% Security Verify, adaptive access Services-led identity transformation
Entrust ~2–4% Identity as a Service, PKI, digital onboarding Financial and government identity proofing
OneSpan ~1–3% Digipass, mobile authentication, FIDO solutions Banking-focused authentication
Transmit Security ~1–3% Customer identity orchestration, passkeys, fraud detection Consumer identity for retail and banking
Beyond Identity ~1–2% Device-bound passwordless platform Zero-trust device security pure-play

Recent News & Developments

  • Thoma Bravo (August 2023): Completed the acquisition of ForgeRock and combined it with Ping Identity, creating a larger enterprise identity vendor with deeper hybrid capabilities [16]
  • Google (October 2023): Made passkeys the default sign-in option for personal Google accounts, normalizing passwordless login for billions of users [8]
  • European Union (May 2024): Regulation (EU) 2024/1183 entered into force, setting the legal basis for European Digital Identity Wallets across member states [3]
  • Monetary Authority of Singapore and Association of Banks in Singapore (July 2024): Announced the phase-out of SMS OTPs for bank account login, accelerating app-based and device-bound authentication [25]
  • FIDO Alliance (December 2024): Reported more than 15 billion online accounts able to use passkeys, signaling consumer-scale readiness [1]
  • PCI Security Standards Council (March 2025): Future-dated PCI DSS v4.0 requirements, including MFA for all access into cardholder data environments, became mandatory [10]
  • Microsoft (May 2025): Set new consumer accounts to passwordless by default and promoted passkeys as the primary sign-in method [9]
  • NIST (August 2025): Finalized SP 800-63-4, recognizing syncable authenticators and updating requirements for recovery and biometrics [4]

Passwordless Authentication Market Report Scope

Parameter Details
Market Scope The Passwordless Authentication Market covers hardware, software/platform, and services that authenticate users through biometrics, passkeys, security keys, push methods, and PKI across cloud, hybrid, and on-premises deployments for enterprise and consumer use.
Study Period 2021–2035
Base Year 2025
Historical Data 2021–2024
Forecast Period 2026–2035
Market Size in 2025 USD 22.40 Billion
Market Size in 2035 USD 110.14 Billion
CAGR (2026–2035) 16.9%
Fastest Growing Segments Hybrid (19.8% CAGR); Small and Medium Enterprises (18.8% CAGR); Passkeys (18.3% CAGR); Retail and E-commerce (18.1% CAGR)
Regions Covered North America, Europe, South America, Asia Pacific, Middle East and Africa and ROW
Companies Profiled Microsoft, Okta, Cisco (Duo), Ping Identity, Thales, HID Global, Yubico, IBM, Entrust, OneSpan, Transmit Security, Beyond Identity
Valuation Currency USD Billion
Methodology 350+ primary expert interviews; bottom-up market sizing; top-down validation; data triangulation; scenario-based forecasting; real-time project tracking

FAQs

How should procurement teams compare vendors in the Passwordless Authentication Market?
Prioritize FIDO certification, documented account-recovery workflows, and native connectors for existing directories. Ask reference customers for login-success and reset-ticket baselines before signing multi-year terms [1].
Are synced passkeys acceptable for regulated workloads?
NIST SP 800-63-4 accepts syncable authenticators at AAL2, covering most workforce and consumer scenarios. Privileged and AAL3 use cases still require device-bound keys that cannot be exported [4].
How do cyber insurers influence the Passwordless Authentication Market?
Insurers increasingly tie coverage terms and premiums to phishing-resistant MFA on remote and privileged access. Underwriting pressure turns deployment into a financial decision, especially for mid-sized firms at renewal [24].
Does post-quantum cryptography threaten current passwordless investments?
Today's FIDO credentials use elliptic-curve signatures that future quantum computers could break. Choose vendors with crypto-agile roadmaps aligned to NIST's 2024 post-quantum standards, enabling credential reissue without platform replacement [15].
Can passwordless methods secure shared devices and frontline workers?
Yes, through NFC badges, kiosk modes, and roaming security keys not tied to personal phones. Hospitals, retail floors, and warehouses rely on these patterns where smartphones are restricted [21].
Which KPIs show a rollout is succeeding?
Track enrollment rate, authentication success rate, password-fallback frequency, and reset-ticket volume. A steadily falling fallback rate signals when passwords can safely be disabled [22].
How are pricing models shifting in the Passwordless Authentication Market?
Customer identity is moving toward monthly-active-user pricing, while workforce deals favor tiered per-seat bundles. Buyers in the Passwordless Authentication Market with seasonal traffic should negotiate usage caps and overage rates upfront [17].
Author
Author Author Profile Ankit Gupta LinkedIn Team Lead - Research
Ankit Gupta is a seasoned market intelligence and strategic research professional with over six plus years of experience in the ICT and Semiconductor industries. With academic roots in Telecom, Marketing, and Electronics, he blends technical insight with business strategy. Ankit has led 200+ projects, including work for Fortune 500 clients like Microsoft and Rio Tinto, covering market sizing, tech forecasting, and go-to-market strategies. Known for bridging engineering and enterprise decision-making, his insights support growth, innovation, and investment planning across diverse technology markets.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of regulatory databases, peer-reviewed cybersecurity journals, technical publications, and authoritative technology organizations. Key sources included the National Institute of Standards and Technology (NIST), European Union Agency for Cybersecurity (ENISA), International Organization for Standardization (ISO/IEC 27001), Internet Engineering Task Force (IETF), FIDO Alliance, World Wide Web Consortium (W3C), National Cybersecurity Centre (NCSC-UK), Cybersecurity and Infrastructure Security Agency (CISA), European Commission Digital Strategy Reports, International Telecommunication Union (ITU), IEEE Xplore Digital Library, ACM Digital Library, and national cybersecurity frameworks from key markets including Singapore CSA, Australia ACSC, and Japan NISC. These sources were used to collect authentication protocol standards, regulatory compliance requirements, cybersecurity incident statistics, biometric technology patents, and competitive landscape analysis for biometric authentication, multi-factor authentication (MFA), zero-knowledge proof systems, and behavioral analytics technologies.


Primary Research

In order to gather both qualitative and quantitative insights, supply-side and demand-side stakeholders were interviewed during the primary research process. CEOs, CTOs, VPs of Product Security, chief information security officers (CISOs), and heads of identity and access management from companies that offer passwordless authentication, biometric technologies, and enterprise security solutions were examples of supply-side sources. CISOs, chief technology officers, IT directors, security architects, and procurement leads from financial services firms, healthcare organizations, governmental bodies, retail businesses, and telecommunications companies were examples of demand-side sources. Market segmentation, product development roadmaps, enterprise adoption patterns, integration issues, pricing models, and compliance-driven procurement decisions were all corroborated by primary research.

Primary Respondent Breakdown:

By Designation: C-level Primaries (32%), Director Level (30%), Others (38%)

By Region: North America (38%), Europe (25%), Asia-Pacific (28%), Rest of World (9%)


Market Size Estimation

Global market valuation was derived through revenue mapping and enterprise deployment analysis. The methodology included:

Identification of 50+ key technology vendors across North America, Europe, Asia-Pacific, and Latin America

Product mapping across biometric authentication (fingerprint, facial recognition, iris recognition), multi-factor authentication (MFA), zero-knowledge proof, and behavioral analytics categories

Analysis of reported and modeled annual revenues specific to passwordless authentication portfolios

Coverage of vendors representing 75-80% of global market share in 2024

Extrapolation using bottom-up (enterprise deployment volume × ASP by region and organization size) and top-down (vendor revenue validation) approaches to derive segment-specific valuations across authentication methods, deployment models (on-premise, cloud-based, hybrid), organization sizes (SMEs, large enterprises), industry verticals (financial services, healthcare, government, retail, IT and telecom), and device types (smartphones, laptops, tablets, IoT devices)

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Global Diameter Signaling Market
Case Study
Information and Communications Technology
Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.


















