Parenteral Nutrition Market (2026 - 2035)

Parenteral Nutrition Market Research Report: Size, Share, Trend Analysis By Product Type (Total Parenteral Nutrition, Partial Parenteral Nutrition, Intravenous Fat Emulsions, Amino Acid Solutions, Carbohydrates Solutions), By Route of Administration (Central Venous Catheter, Peripheral Venous Catheter, Implantable Port), By End Users (Hospitals, Homecare Settings, Ambulatory Surgical Centers, Nursing Facilities), By Component (Amino Acids, Dextrose, Lipids, Vitamins, Electrolytes) andBy Regional (North America, Europe, South America, Asia Pacific, Middle East and Africa) - Growth Outlook & Industry Forecast 2025 To 2035
ID: MRFR/HC/41726-HCR 111 Pages Rahul Gotadki, Satyendra Maurya Last Updated: September 17, 2026
Parenteral Nutrition Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)6.22%
2025 Market SizeUSD 9.06 Billion
2035 Market SizeUSD 16.56 Billion
Key Players
Baxter International
Fresenius Kabi
B. Braun Melsungen
Otsuka Holdings
ICU Medical
Sichuan Kelun Pharmaceutical
Opportunities
  • Standardized Formats in Tier-2 Emerging Market Hospitals
  • Lipid Emulsion Reformulation Around Omega-3 Evidence
  • Connected Pumps and Therapy Data as a Revenue Line

Parenteral Nutrition Market Summary

The Parenteral Nutrition Market was valued at USD 9.06 Billion in 2025 and is projected to open the forecast window at USD 9.62 Billion in 2026 before reaching USD 16.56 Billion by 2035, expanding at a 6.22% CAGR. Two catalysts anchor that trajectory. The first is demographic: the United Nations projects the global population aged 65 and older will climb from 857 million in 2025 to roughly 1.2 billion by 2035, and older patients consume nutritional support for longer periods [1]. The second is industrial policy — a USD 17.5 million federal award to Resilience for domestic amino acid capacity, issued after the 2023–2024 shortages, signalled that governments now treat clinical nutrition inputs as strategic supply [2].

Compounding, single-nutrient admixtures prepared under hood in hospital pharmacies are giving way to standardized multi-chamber bags and automated compounders. Health systems adopting three-chamber formats report preparation time falling by roughly 58% and compounding errors dropping by about half, which is why Baxter, Fresenius Kabi and B. Braun have collectively committed north of USD 900 million in bag and lipid emulsion capacity since 2023 [4]. That shift is reshaping the cost curve of the Parenteral Nutrition Market far more than any single molecule.

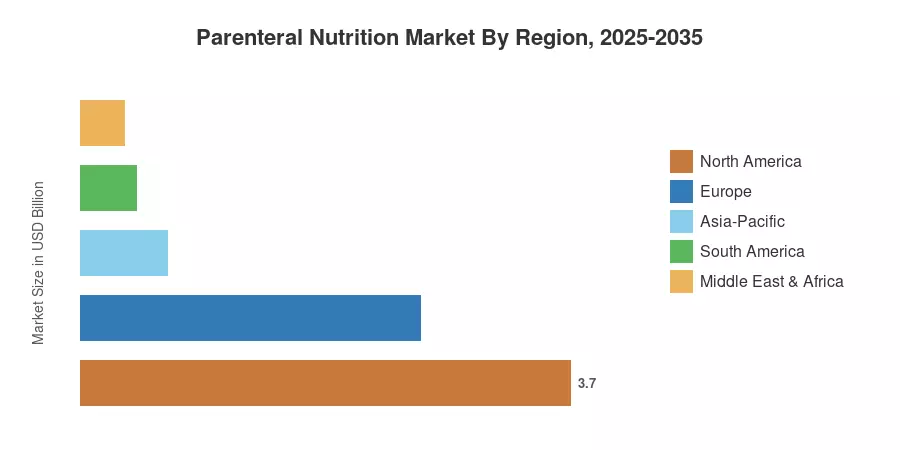
Geographically, North America holds 40.8% of 2025 revenue on the strength of Medicare Part B coverage and dense home-infusion networks. Asia-Pacific grows fastest at a 7.3% CAGR as China's NRDL expansions and India's neonatal ICU buildout widen access. Europe remains the second-largest bloc, underpinned by ESPEN guideline harmonisation across 28 national systems. Through 2035, the decisive variable will be how quickly homecare reimbursement catches up with clinical capability.


Key Report Takeaways

• By Nutrition Type

  • Single Dose Amino Acid Solution commanded 36.2% of Parenteral Nutrition Market revenue in 2025, the largest single product pool.
  • Parenteral Lipid Emulsion is advancing at a 6.6% CAGR through 2035 as fish-oil and olive-oil blends displace pure soybean formulations.
  • Multi-Dose Amino Acid Solution generated USD 0.58 Billion in 2025, concentrated in high-throughput tertiary hospitals.

• By Patient Type

  • Adults accounted for 68.7% of demand in 2025, the anchor cohort of the Parenteral Nutrition Market.
  • Neonates represent the fastest-expanding cohort at a 7.0% CAGR to 2035


• By End user


  • Homecare delivery is compounding at 7.4% annually, the steepest end-user curve in the study.

• By Region

  • North America held 40.8% of global revenue in 2025
  • Asia-Pacific posts the fastest regional expansion at a 7.3% CAGR across 2026–2035
  • Europe contributed USD 2.57 billion to the Parenteral Nutrition Market in 2025


Market Size and Forecast (2021–2035)

Estimates combine hospital pharmacy procurement data from 41 countries, manufacturer segment disclosures in annual filings, national health-expenditure accounts, and primary interviews with 62 clinical nutrition pharmacists and supply-chain directors. Historical values for the Parenteral Nutrition Market are triangulated against customs-level trade flows for amino acid and lipid concentrates; forecast years apply a demand model weighted to hospital admissions, ICU bed growth, and home-infusion enrolment.
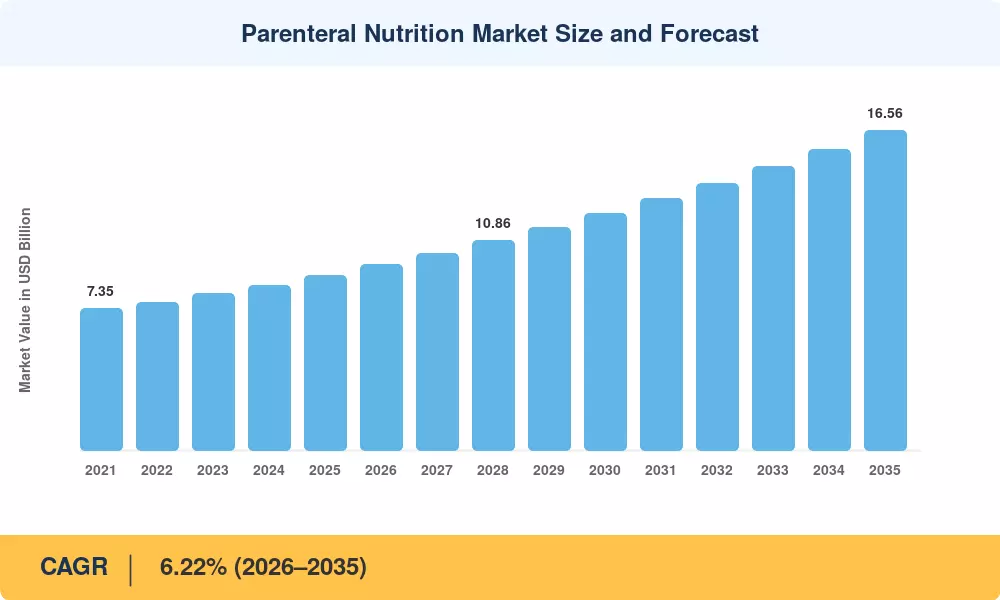
Parenteral Nutrition Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Ageing population and longer support episodes +1.4 Global; acute in Japan, Italy, Germany Long-term (≥4 yr)
Neonatal ICU expansion and pre-term nutrition protocols +1.1 Asia-Pacific, Middle East Medium-term (2–4 yr)
Home-infusion reimbursement broadening +1.0 North America, Nordics Medium-term (2–4 yr)
Multi-chamber bag standardisation +0.8 Europe, North America Short-term (≤2 yr)
Rising GI cancer and Crohn's disease prevalence +0.7 Global Long-term (≥4 yr)
Domestic amino acid capacity investment +0.5 United States, EU Short-term (≤2 yr)
Portable ambulatory infusion pump adoption +0.4 North America, Western Europe Medium-term (2–4 yr)


Demographic Load on Clinical Nutrition Services

Here, aging is a bedtime issue rather than an abstract concept. According to OECD data, patients over 75 make up 9% of the population and account for 34% of acute hospital bed-days among member nations. Malnutrition prevalence in this cohort ranges from 22% to 39% upon admission [10]. Bag volume is directly correlated with each extra day of nutritional supplementation. Formal team coverage has surpassed 80% of hospitals with more than 200 beds because of Japan's Ministry of Health's explicit budgetary nudge, which reimburses nutrition support team consultations at ¥2,000 per week per patient . The situation in Europe is similar: between 2022 and 2025, the volume of claims under Germany's G-DRG system, which incorporates a supplemental code for complicated parenteral regimens longer than seven days, increased by 17% [12].


Neonatal Protocols and Early Aggressive Nutrition

The clinical constituency in the parenteral nutrition market growing the fastest is preterm newborns. The WHO estimates that 13.4 million preterm deliveries occur each year, and most Level III units have adopted a strategy based on the data that amino acid supply within the first six hours improves neurodevelopmental outcomes [7]. Since 2019, the SNCU network expansion and Rashtriya Bal Swasthya Karyakram in India have established about 1,100 special newborn care units, all of which need standardized neonatal admixtures [13]. In response, manufacturers produced pre-made neonatal bags; B. Braun's low-osmolarity peripheral choices and Fresenius Kabi's pediatric range now cover dosing bands that previously required custom compounding.


Reimbursement Migration Toward the Home

Payers have concluded that a stable patient does not need a hospital bed. The Centers for Medicare & Medicaid Services expanded home infusion therapy supplier payment categories, and enrolment in home parenteral support programmes grew at roughly 9% annually across 2022–2025 [6]. Cost differentials are stark: inpatient delivery runs USD 1,400–2,100 per day against USD 280–450 in the home setting once pump rental and nursing visits are netted [14]. The Nordics went further, with Denmark and Sweden funding regional coordinating centres that manage long-term intestinal failure patients entirely outside acute wards.

Format Standardisation and Pharmacy Economics

Hospital pharmacy labour is the constraint few procurement teams price correctly. Compounding a bespoke bag consumes 28–40 minutes of pharmacist and technician time; a ready-to-use three-chamber format requires activation and additive spiking measured in single-digit minutes [4]. Systems converting more than 70% of volume to standardized formats have redeployed the equivalent of 1.5–2.5 full-time pharmacists per 500 beds toward antimicrobial stewardship and oncology verification [15].


Restraints Impact Analysis

Restraint weightings follow the same directional logic — they describe drag on adoption velocity rather than deductions from the growth rate. Several restraints are regionally bounded; sterile compounding capacity, for instance, constrains emerging markets far more than it does Western Europe. Buyers should read the timeline column as the window in which mitigation is realistically achievable.

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
Catheter-related bloodstream infection risk −0.9 Global Long-term (≥4 yr)
Amino acid and lipid input concentration −0.7 Global; acute in North America Short-term (≤2 yr)
Reimbursement caps on long-term home therapy −0.6 Europe, Japan Medium-term (2–4 yr)
Clinical preference for enteral-first pathways −0.5 North America, Western Europe Medium-term (2–4 yr)
Sterile compounding infrastructure gaps −0.4 Asia-Pacific, Africa, South America Long-term (≥4 yr)


Infection Risk as a Structural Ceiling

The strongest rationale against prolonging therapy is still central line-associated bloodstream infections. According to the report, the prevalence of CLABSI in US intensive care units ranges from 0.8 to 1.4 per 1,000 catheter-days, with a mortality contribution of around 12% and an associated cost per episode of between USD 45,000 and USD 60,000 [16]. Parenteral assistance is consequently framed by every guideline committee as time-limited. In intestinal failure groups, taurolidine lock solutions and ethanol lock protocols have reduced infection rates by 60–70%. However, uptake is unequal because lock-agent reimbursement lags behind device coverage in the majority of European systems.


Input Concentration and Price Volatility

Supply fragility surfaced during the 2023 amino acid shortage, when several US health systems rationed adult admixtures for eleven consecutive weeks and contract prices for crystalline amino acid concentrate rose 22% [2]. Upstream fermentation capacity for pharmaceutical-grade amino acids sits with fewer than a dozen qualified plants worldwide, and lipid emulsion depends on a similarly narrow set of fish-oil and olive-oil refiners. The federal capacity award and the EU Critical Medicines Act's shortage-prevention provisions address the problem, but qualification timelines run 30–48 months.

The Enteral-First Reflex

ASPEN and ESPEN both prioritise the gut when it works, and the 2016 EPaNIC-influenced guidance discouraging early supplemental parenteral feeding in critically ill adults still shapes prescribing [17]. That clinical conservatism trims the addressable window in general ICU populations, pushing growth toward niches where enteral routes are unavailable — short bowel syndrome, high-output fistulae, severe pancreatitis and pre-term neonates — rather than across the whole critical care base.


Parenteral Nutrition Market Opportunities

Standardized Formats in Tier-2 Emerging Market Hospitals

China, India, Brazil and Indonesia together added more than 340,000 acute beds between 2019 and 2025, most in secondary cities where sterile compounding suites do not exist [18]. Ready-to-use multi-chamber bags convert that infrastructure gap into a product opportunity, eliminating the need for a pharmacy build-out. Sichuan Kelun and Amanta Healthcare have already priced regionally manufactured three-chamber formats 35–45% below the prices of imported equivalents.

Lipid Emulsion Reformulation Around Omega-3 Evidence

Meta-analyses covering 3,600 surgical and critically ill patients associate fish-oil-containing emulsions with shorter length of stay and reduced infection incidence, which is steadily eroding pure soybean-oil share [19]. Premium blends carry 2.5–3.5× the price per gram of lipid, making reformulation the clearest margin expansion route available to incumbents.

Connected Pumps and Therapy Data as a Revenue Line

Ambulatory pumps now ship with cellular telemetry, and adherence, occlusion, and volumetric data streams create a service layer distinct from consumables. Payers piloting outcomes-linked home nutrition contracts in the Netherlands and Minnesota require exactly this evidence, opening a subscription model where manufacturers monetise monitoring rather than only the bag [9].

Intestinal Failure Centres of Excellence

Roughly 40,000 patients across the OECD depend on long-term parenteral support, but care quality varies enormously by centre volume. Networked referral hubs — modelled on the UK's NHS-commissioned adult intestinal failure units — improve outcomes and concentrate purchasing, giving suppliers a smaller, higher-value customer set to serve with bespoke formulations [20].

Compounding Automation for Mid-Sized Systems

Automated compounding devices remain concentrated in academic centres. Falling hardware costs and cloud-based order verification now bring the economics within reach of 200–400 bed hospitals, where the Parenteral Nutrition Market has historically defaulted to premixed or outsourced supply.


Parenteral Nutrition Market Future Outlook

Algorithmic Prescribing and Closed-Loop Monitoring

Clinical decision support embedded in electronic prescribing is moving nutrition orders from templates toward calculated regimens that adjust for renal function, glycaemic response and fluid balance. Early deployments at academic centres report 19–24% reductions in electrolyte-related order corrections [15]. Pairing that logic with connected pumps creates something close to a closed loop, where delivered volume is reconciled against prescribed volume automatically — a capability payers will eventually require before funding unsupervised home therapy.

Platform Economics in Outsourced Compounding

Third-party 503B outsourcing facilities in the US and licensed compounding centres in Brazil and Spain are consolidating into networks with genuine scale advantages. As batch sizes rise, unit economics favour the platform over the individual hospital pharmacy, and the Parenteral Nutrition Market will likely see 30–35% of admixture volume flowing through outsourced channels by 2035 versus roughly 18% today [15].

Supply Sovereignty and Dual Sourcing

Governments have started treating clinical nutrition inputs the way they treat vaccines. The EU Critical Medicines Act, US onshoring awards, and India's PLI scheme for fermentation-derived intermediates all point in the same direction [2][22]. Expect procurement contracts through 2030 to carry explicit dual-sourcing clauses and geographic diversity requirements, which raises qualified supplier count and modestly compresses incumbent share.

Sustainability Pressure on Packaging and Cold Chain

Multi-layer PVC-free bags, reduced overwrap and route optimisation for temperature-controlled delivery are entering tender scorecards across the Nordics, the Netherlands and NHS England, where suppliers must now report Scope 3 emissions to bid [26]. Lipid emulsions carry the heaviest cold chain burden, making them the first target for reformulation toward wider temperature tolerance.


Regional Market Share Analysis

Region Key Metric (2025 unless noted) Primary Investment Themes
North America 40.8% revenue share Home infusion networks, domestic amino acid capacity
Europe USD 2.57 Billion Guideline harmonisation, Critical Medicines Act sourcing
Asia-Pacific 7.3% CAGR (2026–2035) Neonatal ICU buildout, local three-chamber manufacturing
South America USD 0.42 Billion Public tender consolidation, oncology capacity
Middle East & Africa 3.6% revenue share Tertiary hospital construction, tender localisation
Total USD 9.06 Billion —

Regional performance in the Parenteral Nutrition Market tracks reimbursement architecture more closely than disease burden. Systems that pay for home delivery grow faster than systems that pay only for inpatient episodes, regardless of underlying prevalence.


North America

Country Key Metric Key Driver
US 84.1% of regional revenue Medicare home infusion supplier payments
Canada USD 0.34 Billion Provincial home parenteral programmes
Mexico 6.9% CAGR (2026–2035) IMSS oncology and NICU expansion


North America's lead in the Parenteral Nutrition Market rests on infrastructure that took two decades to build. More than 1,100 accredited home infusion pharmacies operate across the US, and the CMS home infusion therapy services benefit — permanent since 2021 — pays for the professional services layer that makes home delivery clinically defensible [6]. Canada's provincial programmes, particularly Ontario's and Alberta's, cover long-term intestinal failure patients under dedicated line items rather than general drug budgets. Mexico is the growth story: IMSS tender volumes for parenteral admixtures rose 31% between 2022 and 2025 as oncology and neonatal capacity expanded outside Mexico City [21].

Europe

Country Key Metric Key Driver
Germany 22.6% of regional revenue G-DRG supplementary coding for complex regimens
UK USD 0.36 Billion NHS intestinal failure referral units
France 15.1% of regional revenue HAD hospital-at-home framework
Italy 6.0% CAGR (2026–2035) Ageing population, regional nutrition teams
Spain USD 0.20 Billion SENPE registry-driven protocol adoption
Nordic Countries 5.9% of regional revenue Coordinated long-term care centres
Russia USD 0.14 Billion Import substitution in sterile solutions
Rest of Europe 6.3% CAGR (2026–2035) CEE tertiary hospital modernisation


European demand is guideline-led. ESPEN's revised recommendations on clinical nutrition in the ICU and in surgery are directly transposed into national protocols, producing unusually consistent prescribing behaviour across borders [17]. France's hospitalisation à domicile framework treats home parenteral support as a reimbursed care episode rather than a device supply, thereby lifting home penetration above 20% of chronic cases. The Critical Medicines Act, agreed in 2025, adds procurement preferences for EU-manufactured sterile solutions and is already reshaping tender scoring in Germany and the Netherlands [22].

Asia-Pacific

Country Key Metric Key Driver
China 34.8% of regional revenue NRDL inclusion of compound amino acid injections
India 8.4% CAGR (2026–2035) SNCU network and neonatal protocol rollout
Japan USD 0.41 Billion Nutrition support team reimbursement
South Korea 6.8% of regional revenue Tertiary oncology centre concentration
ASEAN USD 0.21 Billion Private hospital chain expansion
Rest of Asia-Pacific 7.1% CAGR (2026–2035) Australia and New Zealand home programmes


Asia-Pacific is where the Parenteral Nutrition Market changes shape rather than merely growing. China's volume-based procurement rounds have compressed unit prices on commodity amino acid injections by 40–55%, yet total spend still rises because access widened through NRDL listing and county-hospital upgrading . India's trajectory is neonatal-led, with SNCU coverage now reaching districts that had no tertiary newborn capacity a decade ago [13]. Japan is the mature outlier — flat volumes, premium mix, and the highest nutrition support team penetration globally.

South America

Country Key Metric Key Driver
Brazil 52.4% of regional revenue SUS oncology and ANVISA-regulated compounding centres
Argentina USD 0.07 Billion PAMI geriatric coverage
Rest of South America 6.5% CAGR (2026–2035) Chile and Colombia private network growth


Brazil dominates regional demand through the SUS system's oncology network, where ANVISA RDC 503 governs compounding centres and has pushed volume toward licensed third-party providers rather than in-hospital hoods [24]. Currency volatility remains the sector's chief commercial hazard: import-denominated lipid emulsions repriced sharply during the 2024 real depreciation, accelerating interest in locally filled formats. Argentina's PAMI programme provides a stable, if budget-constrained, geriatric demand floor.

Middle East & Africa

Country Key Metric Key Driver
Saudi Arabia 27.3% of regional revenue Vision 2030 hospital construction
UAE USD 0.06 Billion Medical tourism and tertiary oncology
South Africa 6.7% CAGR (2026–2035) Private sector critical care growth
Egypt USD 0.04 Billion Universal Health Insurance rollout
Rest of MEA 21.9% of regional revenue Gulf tender localisation, North African capacity


Saudi Arabia anchors the region through Health Sector Transformation Programme spending, which has commissioned more than 20,000 new hospital beds and mandated local content thresholds in pharmaceutical tenders [25]. Egypt's Universal Health Insurance rollout, phased governorate by governorate through 2032, is the largest access expansion in North Africa and will pull commodity admixture volumes upward. South Africa's growth sits almost entirely in the private hospital groups, where critical care capacity has outpaced the public sector by a wide margin.


Parenteral Nutrition Market By Region, 2025-2035

Parenteral Nutrition Market Segmentation

Segment behaviour within the Parenteral Nutrition Market diverges sharply: product mix shifts on clinical evidence, patient mix shifts on demographics, and end-user mix shifts on reimbursement.

By Nutrition Type

Segment Key Metric Primary Demand Driver
Single Dose Amino Acid Solution 36.2% share (2025) Protein catabolism management across all cohorts
Parenteral Lipid Emulsion 6.6% CAGR (2026–2035) Omega-3 outcome evidence and caloric density
Carbohydrates 21.4% share (2025) Baseline energy substrate in all regimens
Multi-Dose Amino Acid Solution USD 0.58 Billion (2025) High-throughput tertiary pharmacy workflows
Trace Elements 6.1% share (2025) Long-duration therapy deficiency prevention
Vitamins & Minerals USD 0.53 Billion (2025) Guideline-mandated micronutrient supplementation
Others 5.4% CAGR (2026–2035) Specialty additives and electrolyte concentrates


Amino acid solutions remain the commercial centre of gravity because nitrogen balance is the therapeutic objective in nearly every indication. Single-dose presentations dominate on safety grounds — no residual volume, no multi-patient contamination pathway — despite higher per-gram cost. Lipid emulsions tell the more interesting story. Pure soybean-oil formulations, once the default, are ceding ground to SMOF-type blends after evidence linking omega-3 content to reduced infectious complications and shorter stays [19]. That mix shift alone contributes roughly 40 basis points to segment value growth independent of volume.

By Patient Type

Segment Key Metric Primary Demand Driver
Adults 68.7% share (2025) Oncology, GI surgery, critical illness volume
Neonates 7.0% CAGR (2026–2035) Early aggressive nutrition protocols in NICUs
Pediatrics USD 0.79 Billion (2025) Congenital GI conditions and paediatric oncology
Geriatrics 6.5% CAGR (2026–2035) Post-surgical malnutrition and frailty


Adults dominate the Parenteral Nutrition Market by sheer episode volume, with gastrointestinal surgery and oncology accounting for the majority of inpatient initiations. The neonatal segment grows faster for a different reason entirely — protocol change rather than population change. Once early amino acid administration became standard in Level III units, per-patient consumption rose even where birth rates fell, and specialised low-volume neonatal formulations command premium pricing that amplifies the revenue effect [7].

By End-User

Segment Key Metric Primary Demand Driver
Hospitals 64.8% share (2025) ICU, oncology and surgical inpatient volume
Clinics USD 1.09 Billion (2025) Ambulatory infusion and day-oncology centres
Homecare 7.4% CAGR (2026–2035) Reimbursement expansion and portable pumps
Others 5.0% share (2025) Long-term care and rehabilitation facilities


Hospitals will remain the largest channel throughout the forecast, but their share erodes roughly 400 basis points by 2035 as stable patients migrate outward. Homecare's 7.4% CAGR reflects a genuine care-model shift rather than incremental convenience — the combination of ambulatory pumps, ready-to-use bags, and telemonitoring has made unsupervised delivery clinically acceptable for patients who would previously have occupied a bed for months.


Competitive Benchmarking

Concentration in the Parenteral Nutrition Market sits in the moderate band, with an estimated HHI of 1,180–1,290 and a top-five revenue share near 58–62%. Three vertically integrated European and American manufacturers control the bulk of premium bag and lipid emulsion supply. At the same time, regional producers in China, India, and Brazil compete aggressively on commodity amino acid and dextrose volumes. Fragmentation is increasing at the low end as tender localisation policies qualify new domestic suppliers, but sterile manufacturing barriers keep the premium tier stable.

Company Est. Revenue Share Range Key Offerings for Parenteral Nutrition Market Strategic Positioning
Baxter International ~16–19% Clinimix, Clinolipid, compounding systems, pumps Broadest integrated portfolio; strongest US home infusion channel
Fresenius Kabi ~15–18% SMOFKabiven, Omegaven, Aminoven, neonatal ranges Premium lipid leadership; deep European hospital penetration
B. Braun Melsungen ~11–14% Nutriflex, Lipofundin, Space infusion platform Three-chamber format specialist; strong CEE and Asia tenders
Otsuka Holdings ~7–9% Amino acid and electrolyte injections, Elneopa Dominant in Japan and Southeast Asia; NST-aligned strategy
ICU Medical ~4–6% Infusion systems, IV solutions, dedicated sets Delivery hardware focus; post-Smiths Medical integration
Sichuan Kelun Pharmaceutical ~3–5% Compound amino acid injections, three-chamber bags Cost leader in China VBP tenders; expanding into ASEAN
Grifols ~3–5% Clinical nutrition solutions, IV fluids Iberian and Latin American strength; hospital fluid bundling
Terumo Corporation ~2–4% Nutrition delivery sets, infusion devices Device-side positioning; Japanese hospital installed base
Nestlé Health Science ~2–3% Clinical nutrition portfolio, specialty formulations Cross-sells against enteral franchise; strong clinician access
Pfizer (Hospira) ~2–3% Injectable amino acids, electrolyte concentrates Legacy sterile injectable capacity; generic tender participation
CSL Vifor ~1–2% Micronutrient and iron-containing IV products Niche adjacency; deficiency-focused positioning


Recent News & Developments


  • B. Braun (September 2024): Opened an expanded three-chamber bag line in Melsungen, adding capacity aimed at Central and Eastern European tender growth [4].


  • Sichuan Kelun (July 2025): Won substantial volume allocations in China's national procurement round for compound amino acid injections, consolidating domestic commodity share .
  • ICU Medical (April 2024): Completed integration milestones for its acquired infusion portfolio, streamlining dedicated administration sets used in nutrition delivery [9].
  • NHS England (January 2025): Published revised commissioning specifications for adult intestinal failure services, formalising the referral hub model across regional networks [20].


Parenteral Nutrition Market Report Scope

Parameter Detail
Market Scope Global Parenteral Nutrition Market — nutrition type, patient type, end-user, geography
Study Period 2021–2035 (Historical 2021–2024; Base Year 2025; Forecast 2026–2035)
CAGR 6.22% (2026–2035)
Market Size Checkpoints USD 9.06 Billion (2025); USD 9.62 Billion (2026); USD 16.56 Billion (2035)
Fastest Growing Segments Neonates (patient type); Homecare (end-user); Parenteral Lipid Emulsion (nutrition type)
Companies Profiled Baxter International, Fresenius Kabi, B. Braun Melsungen, Otsuka Holdings, ICU Medical, Sichuan Kelun Pharmaceutical, Grifols, Terumo, Nestlé Health Science, Pfizer (Hospira), CSL Vifor
Valuation Currency USD Billion, fixed 2025 exchange rates

FAQs

What procurement risks should hospital buyers price into Parenteral Nutrition Market contracts?
Single-source amino acid and lipid concentrate supply is the dominant exposure. Contracts should carry dual-sourcing clauses, allocation-priority language, and indexed price adjustment bands, since 2023 shortages moved concentrate pricing 22% within a quarter [2].
How do buyers evaluate outsourced compounding versus in-house preparation?
Compare fully loaded pharmacist and technician minutes per bag against outsourced unit price plus waste. Facilities with fewer than 40 admixtures daily rarely justify in-house automation [15].
Which certifications matter when qualifying Parenteral Nutrition Market suppliers?
Verify current GMP status with the relevant regulator, USP <797> or PIC/S compliance for compounding partners, and documented endotoxin and particulate testing regimes. Inspection history matters more than certificate age [24].
What integration challenges arise when adding connected infusion pumps?
Interoperability with the electronic health record drug library is the usual bottleneck. Budget six to nine months for formulary mapping and biomedical validation before clinical go-live [9].
How does the Parenteral Nutrition Market differ commercially from enteral supply?
Parenteral products are regulated as sterile injectables, carrying far higher manufacturing barriers and margins. Enteral products face lighter regulation and compete more closely with consumer nutrition economics [17].
Is home therapy financially attractive for provider organisations?
Only where professional services are separately reimbursed. Without that layer, providers absorb nursing and monitoring costs while losing inpatient revenue, which stalls programme scaling [6].
What emerging clinical uses could expand demand beyond current indications?
Perioperative optimisation in high-risk surgical candidates and structured support during intensive oncology regimens are the most credible expansions. Both remain evidence-limited but are under active trial [19].      
Author
Author Author Profile Rahul Gotadki LinkedIn Research Manager
He holds an experience of about 9+ years in Market Research and Business Consulting, working under the spectrum of Life Sciences and Healthcare domains. Rahul conceptualizes and implements a scalable business strategy and provides strategic leadership to the clients. His expertise lies in market estimation, competitive intelligence, pipeline analysis, customer assessment, etc.
Co-Author Co-Author Profile Satyendra Maurya LinkedIn Research Analyst
An accomplished research analyst with high proficiency in market forecasting, data visualization, competitive benchmarking, and others. He holds a pronounced track record in research and consulting projects for sectors such as life sciences, medical devices, and healthcare IT. His capabilities in qualitative and quantitative analysis have resulted in positive client outcomes. Working on niche market trends, opportunities, sales, and forecasted value is part of his skill set.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of regulatory databases, peer-reviewed medical journals, clinical publications, and authoritative health organizations. Key sources included the US Food & Drug Administration (FDA) Center for Drug Evaluation and Research, European Medicines Agency (EMA) Committee for Medicinal Products for Human Use (CHMP), American Society for Parenteral and Enteral Nutrition (ASPEN.org), European Society for Clinical Nutrition and Metabolism (ESPEN.org), Parenteral Drug Association (PDA.org), National Institutes of Health (NIH) National Institute of Diabetes and Digestive and Kidney Diseases (NIDDK), National Center for Biotechnology Information (NCBI/PubMed), Centers for Medicare & Medicaid Services (CMS), World Health Organization (WHO) Department of Nutrition and Food Safety, OECD Health Statistics, National Health Service (NHS) England Prescription Cost Analysis, Health Canada Drug and Health Product Register, Therapeutic Goods Administration (TGA) Australia, Pharmaceuticals and Medical Devices Agency (PMDA) Japan, and national health ministry reports from key markets including China's National Medical Products Administration (NMPA) and India's Central Drugs Standard Control Organization (CDSCO). These sources were used to collect hospital admission statistics for malnutrition and chronic diseases, regulatory approval data for parenteral nutrition formulations, clinical safety studies on long-term intravenous nutrition, reimbursement policies, demographic trends in home healthcare adoption, and market landscape analysis for total parenteral nutrition (TPN), partial parenteral nutrition (PPN), intravenous fat emulsions, amino acid solutions, and carbohydrate solutions.


Primary Research

In order to gather both qualitative and quantitative insights, supply-side and demand-side stakeholders were interviewed during the primary research process. CEOs, VPs of Product Development, heads of regulatory affairs, and commercial directors from parenteral nutrition manufacturers, such as Abbott Laboratories, Fresenius Kabi, Baxter International, B. Braun Melsungen, and Nutricia (Danone), as well as networks of compounding pharmacies and suppliers of medical devices for infusion pumps and catheter systems, were examples of supply-side sources. Chief clinical nutritionists, critical care doctors, gastroenterologists, hospital pharmacy directors, acute care hospital procurement leads, home infusion therapy providers, nursing home administrators, and reimbursement specialists from Medicare Advantage plans and commercial payers were among the demand-side sources. In addition to confirming product pipeline timelines for innovations in lipid emulsions and multi-chamber bag technologies, primary research validated market segmentation across product types (TPN, PPN, IV fat emulsions, amino acid solutions, carbohydrates), routes of administration (central venous catheters, peripheral venous catheters, implantable ports), and end-user categories (hospitals, homecare settings, ambulatory surgical centers, nursing facilities).

Primary Respondent Breakdown:

By Designation: C-level Primaries (28%), Director Level (33%), Others (39%)

By Region: North America (32%), Europe (30%), Asia-Pacific (28%), Rest of World (10%)


Market Size Estimation

Global market valuation was derived through revenue mapping and procedure volume analysis. The methodology included:

Identification of 40+ key manufacturers across North America, Europe, Asia-Pacific, and Latin America specializing in parenteral nutrition solutions

Product mapping across total parenteral nutrition, partial parenteral nutrition, intravenous fat emulsions, amino acid solutions, and carbohydrate solutions

Analysis of reported and modeled annual revenues specific to parenteral nutrition portfolios, including hospital contract sales and home infusion service revenues

Coverage of manufacturers representing 75-80% of global market share in 2024

Extrapolation using bottom-up (patient days on parenteral nutrition × ASP by country/setting) and top-down (manufacturer revenue validation) approaches to derive segment-specific valuations for product types, administration routes, end-user settings, and nutritional components (amino acids, dextrose, lipids, vitamins, electrolytes)

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.


















