Nutraceutical Ingredient Market (2026 - 2035)

Nutraceutical Ingredient Market Research Report By Ingredient Type (Vitamins, Minerals, Herbal Extracts, Prebiotics and Probiotics, Specialty Nutrients (Amino Acids, Carotenoids)), By Application (Dietary Supplements, Functional Foods and Beverages, Cosmetics and Personal Care Products, Pharmaceuticals, Pet Food), By Source (Natural, Synthetic, Semi-Synthetic), By End-User Target (Heart Health, Immune System Support, Anti-Aging, Cognitive Function, Digestive Health), By Distribution Channel (Retail Stores, E-commerce, Direct-to-Consumer, Wholesale Distributors, Food and Beverage Manufacturers) and By Regional (North America, Europe, South America, Asia Pacific, Middle East and Africa) - Growth & Industry Forecast 2025 To 2035
ID: MRFR/HC/21156-HCR 100 Pages Satyendra Maurya, Vikita Thakur Last Updated: September 10, 2026
Nutraceutical Ingredient Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)5.90%
2025 Market SizeUSD 117.56 Billion
2035 Market SizeUSD 208.56 Billion
Key Players
DSM-Firmenich
Archer Daniels Midland
Cargill
IFF
BASF
Kerry Group
Opportunities
  • Personalised Nutrition Platforms
  • Africa and Gulf Expansion
  • Clinical Data as a Product

Nutraceutical Ingredient Market Summary

The Nutraceutical Ingredient Market closed 2025 at USD 117.56 billion and is projected to grow to USD 208.56 billion by 2035, expanding at a compound annual growth rate (CAGR) of 5.90% between 2026 and 2035. Market value is expected to reach USD 124.50 billion in 2026 as the first year of the forecast period. This growth is being driven primarily by government-backed manufacturing incentives in India and regulatory clearance reforms in the European Union, alongside a broader shift toward fermentation-derived and clinically validated ingredients.

India's Production Linked Incentive (PLI) scheme for food processing has committed roughly USD 1.3 billion in outlay, with nutraceuticals carved out as a priority category. This scheme is directly strengthening India's domestic nutraceutical manufacturing base and attracting new production capacity. In parallel, the European Union's Novel Food authorization pipeline cleared a record backlog between 2023 and 2025, unlocking commercial routes for ingredients that had waited years for regulatory clearance, giving manufacturers faster access to the EU market.

Reformulation is also reshaping supplier economics across the industry. Fermentation-derived active ingredients, encapsulated delivery technologies, and clinically proven probiotic strains are replacing synthetic vitamin blends and commodity protein isolates. Precision fermentation capacity captured more than USD 4.2 billion in stated investment throughout 2023 to 2025, and that capital is flowing directly into the Nutraceutical Ingredient Market as incumbent manufacturers retrofit legacy extraction lines to accommodate newer production methods.

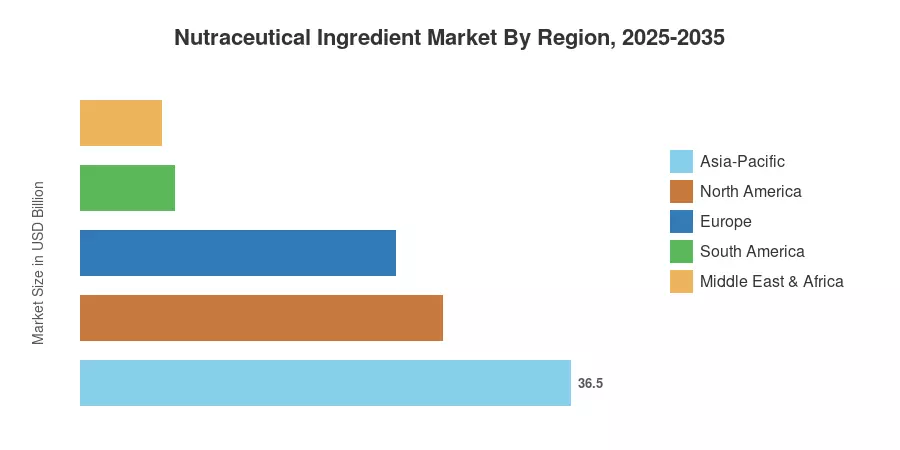
By region, Asia-Pacific holds the largest share of the Nutraceutical Ingredient Market, accounting for 36.5% of 2025 revenue, fueled by China's health food registration reform and India's expanding supplement market. The Middle East and Africa is the fastest-growing region, with a projected CAGR of 8.1%, though growing from a comparatively small base. North America holds the second-largest share, at 27.0%, backed by a mature dietary supplement retail channel and extensive contract-manufacturing depth.


Key Report Takeaways

• By Product Type

  • Vitamins lead the Nutraceutical Ingredient Market with 26.5% of 2025 revenue, underpinned by fortification mandates across staple foods.
  • Probiotics post the fastest product-level growth at 7.4% CAGR through 2035
  • Proteins and amino acids generated USD 21.16 billion in 2025

• By Application

  • Dietary supplements command 38.0% of global demand
  • Functional beverage applications expand at 6.8% CAGR, the quickest of any application in the Nutraceutical Ingredient Market
  • Animal nutrition contributed USD 12.34 billion in 2025

• By Region

  • Asia-Pacific dominates at 36.5% revenue share
  • Middle East & Africa is fastest growing at 8.1% CAGR
  • Europe recorded USD 27.63 billion in 2025


Market Size and Forecast (2021–2035)

Figures below blend supplier-reported revenue, customs and trade-flow reconciliation, and bottom-up demand modelling across 42 ingredient categories. Historical years were validated against audited filings from publicly listed suppliers; forecast years apply category-level elasticity to disposable income, regulatory approval velocity, and installed fermentation capacity.
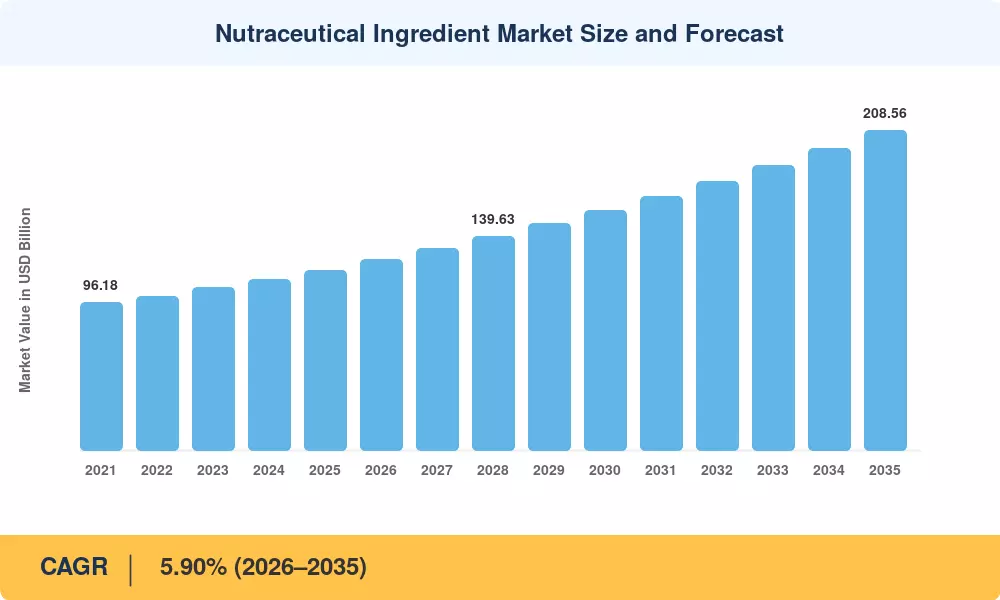
Nutraceutical Ingredient Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Preventive health spending growth 1.35 Global Long-term (≥4 yr)
Government fortification mandates 1.05 Asia-Pacific, Africa Medium-term (2–4 yr)
Clinical substantiation of strains 0.95 North America, Europe Long-term (≥4 yr)
Sports and active nutrition uptake 0.80 Global Short-term (≤2 yr)
Ageing population and healthy longevity 0.70 Europe, Japan Long-term (≥4 yr)
Precision fermentation cost curves 0.60 North America, Europe Medium-term (2–4 yr)
E-commerce supplement penetration 0.45 Asia-Pacific, MEA Short-term (≤2 yr)


Preventive Health Spending

Households are buying prevention. OECD health statistics place per-capita out-of-pocket wellness expenditure growth at roughly 6.3% annually across member states since 2021, outpacing general healthcare inflation. That money flows disproportionately into self-directed categories, which is exactly where the Nutraceutical Ingredient Market captures value. Payers have noticed too — several European insurers now reimburse documented micronutrient protocols for specific deficiency populations, converting discretionary purchases into structural demand.

Fortification Mandates

Regulation creates guaranteed volume. India's FSSAI +F fortification standards cover edible oil, milk, salt, wheat flour and rice, and the Food Corporation of India's rice fortification programme reached national coverage in 2024, requiring sustained premix supply measured in tens of thousands of tonnes annually [6]. Nigeria, Indonesia and Egypt run comparable mandates. These programmes are procurement-driven, low-margin and enormously sticky.

Clinical Substantiation

Evidence is now a moat. EFSA has authorised only a narrow set of health claims under Regulation 1924/2006, and the cost of a compliant human intervention trial routinely exceeds USD 1.5 million [7]. Suppliers carrying documented strains and standardised extracts extract premium pricing that generic equivalents cannot approach, which is steadily concentrating margin among a dozen or so evidence-rich players.

Precision Fermentation Economics

Cost curves have bent sharply. Fermentation-derived vitamin K2, HMOs and specialty proteins have seen unit production costs fall an estimated 30–40% since 2021 as capacity utilisation improved [10]. Once fermentation output undercuts botanical extraction on both price and batch consistency, switching decisions become straightforward for formulators.


Restraints Impact Analysis

Restraint impacts are directional drag estimates scored on the same relative scale used in Section 4; they are not subtractive CAGR components.

Restraint ~% Drag on CAGR Geographic Relevance Impact Timeline
Fragmented global claim regulation −0.85 Global Long-term (≥4 yr)
Botanical raw material price volatility −0.65 Asia-Pacific, South America Short-term (≤2 yr)
Adulteration and identity-testing failures −0.50 Global Medium-term (2–4 yr)
Private-label price compression −0.40 North America, Europe Medium-term (2–4 yr)
Consumer scepticism on efficacy −0.30 Europe, North America Long-term (≥4 yr)


Regulatory Fragmentation

No two jurisdictions agree. An ingredient cleared as a dietary supplement component under the US DSHEA framework may require full Novel Food authorisation in the EU — a process EFSA data shows frequently runs beyond 24 months — while China's health food registration pathway demands separate domestic toxicology. The Nutraceutical Ingredient Market therefore carries duplicated compliance costs on every cross-border launch, and smaller innovators frequently abandon secondary geographies entirely.

Raw Material Volatility

Botanical inputs behave like agricultural commodities because they are agricultural commodities. Curcumin, ashwagandha and boswellia spot prices swung by more than 35% within single crop years during 2022–2024 on monsoon variability and export policy shifts [13]. Formulators respond by dual-sourcing or reformulating toward fermentation-derived alternatives, which dampens near-term botanical volumes.

Adulteration and Trust

Testing failures travel fast. Peer-reviewed DNA-barcoding audits have repeatedly found double-digit misidentification rates in traded botanical powders [14], and each publicised failure triggers retailer de-listings and tighter incoming-goods specifications. Compliance cost rises for honest suppliers, and category growth stalls while trust is rebuilt.


Nutraceutical Ingredient Market Opportunities

Personalised Nutrition Platforms

Subscription diagnostics paired with made-to-order formulations shift ingredient demand from bulk commodity to configurable modules. Suppliers able to ship 200 SKUs in small, traceable lots will capture disproportionate value as direct-to-consumer platforms scale.

Africa and Gulf Expansion

Middle East & Africa remains structurally underserved. Saudi Arabia's Vision 2030 health-sector localisation targets and the Gulf's rapid pharmacy-retail buildout create a genuine geographic gap for suppliers willing to register early. This is the fastest-expanding pocket of the Nutraceutical Ingredient Market.

Clinical Data as a Product

Evidence packages are becoming saleable assets. Suppliers increasingly license strain dossiers, standardised extract monographs and trial datasets to brand owners rather than selling only kilograms — a data monetisation model that raises gross margin without adding tonnage.

Upcycled and Side-Stream Sourcing

Fruit pomace, brewer's spent grain and marine processing residues yield polyphenols, fibres and peptides at materially lower feedstock cost. Regulatory tailwinds under EU circular-economy rules make these streams commercially credible rather than merely reputational.

Companion Animal Premiumisation

Pet supplement demand is growing faster than human categories in several developed markets, and joint-health, gut-health and cognitive actives transfer readily from human portfolios with modest reformulation.


Nutraceutical Ingredient Market Future Outlook

Computational Formulation

Machine-learning models trained on ingredient interaction and stability data are compressing development cycles from eighteen months to under six. By the early 2030s, expect most premium formulations in the Nutraceutical Ingredient Market to be screened computationally before a single pilot batch is run, shifting competitive advantage toward suppliers with proprietary formulation datasets.

Platform and Subscription Economics

Direct-to-consumer subscription models change order profiles fundamentally — smaller lots, higher frequency, tighter traceability. Suppliers structured for bulk tanker economics will struggle; those with flexible, digitally integrated fulfilment will capture the margin.

Sustainability Disclosure as a Purchase Criterion

Scope 3 reporting under CSRD and comparable frameworks makes ingredient carbon intensity a procurement line item. FAO estimates around one-third of global food output is lost or wasted, and side-stream valorisation is the most credible route to lowering both footprint and feedstock cost simultaneously.

Convergence with Pharmaceutical Standards

GMP expectations are converging upward. As live biotherapeutic products and medical foods blur the supplement-pharma boundary, ingredient suppliers face pharmaceutical-grade documentation demands — a cost burden that will accelerate consolidation among mid-tier producers.


Regional Market Share Analysis

Region 2025 Revenue Share (%) Primary Investment Themes
Asia-Pacific 36.5 Fortification premixes, fermentation capacity, e-commerce supply
North America 27.0 Contract manufacturing, clinical substantiation, sports nutrition
Europe 23.5 Novel Food clearances, circular sourcing, claim compliance
South America 7.0 Botanical export processing, functional beverage inputs
Middle East & Africa 6.0 Localisation policy, halal certification, staple fortification
Total 100.0

Regional performance across the Nutraceutical Ingredient Market reflects three variables: regulatory permissiveness, retail channel maturity, and domestic ingredient manufacturing depth.


North America

Country Share of Region (%) Key Driver
US 78.0 DSHEA-enabled supplement channel scale
Canada 13.0 Natural Health Products licensing framework
Mexico 9.0 Contract manufacturing cost advantage


US demand rests on an unusually permissive pre-market framework, but FDA's expanded New Dietary Ingredient notification scrutiny since 2023 has raised the evidentiary bar for genuinely novel actives. Canada's licensing regime is slower yet confers credibility that exporters use across Commonwealth markets. Mexico has quietly become a nearshoring hub for softgel and powder blending serving both US brands and Latin American retail.

Europe

Country 2025 Value (USD B) Key Driver
Germany 5.80 Pharmacy-channel supplement dominance
UK 4.70 Post-Brexit independent novel food route
France 3.87 Complément alimentaire notification system
Italy 3.04 Ministry of Health botanical positive list
Spain 2.49 Sports nutrition and export processing
Nordic Countries 2.21 Marine omega-3 and vitamin D demand
Russia 1.93 Domestic substitution of imported actives
Rest of Europe 3.59 Central European contract manufacturing


Europe trades growth for defensibility. Regulation 1924/2006 blocks most efficacy messaging, so competition shifts to purity, traceability and sustainability credentials — areas where the Corporate Sustainability Reporting Directive now forces disclosure. Italy's botanical positive list remains the pragmatic entry route for plant actives, and many suppliers launch there before attempting EU-wide clearance.

Asia-Pacific

Country Share of Region (%) Key Driver
China 32.0 Health food registration and filing reform
India 19.0 FSSAI fortification mandates and PLI outlay
Japan 17.0 Foods with Function Claims notification regime
South Korea 10.0 Individually recognised functional ingredients
ASEAN 13.0 Halal-certified export manufacturing
Rest of Asia-Pacific 9.0 Rising middle-class supplement adoption


Asia-Pacific anchors the Nutraceutical Ingredient Market on both supply and demand. China combines the largest domestic consumer base with vast vitamin and amino acid manufacturing capacity, while Japan's Foods with Function Claims pathway — notification rather than approval — has generated thousands of filings and given ingredient suppliers a fast commercialisation route. India's dual role as botanical source and fortification buyer makes it the region's most strategically important single country.

South America

Country CAGR 2026–2035 (%) Key Driver
Brazil 6.4 ANVISA functional claim framework
Argentina 5.8 Protein and botanical export processing
Rest of South America 5.3 Andean superfruit and quinoa derivatives


Brazil sets the regional tone. ANVISA's consolidated food supplement rules created legal clarity that pulled multinational brands into the market, and domestic processors of açaí, guarana and camu-camu have moved up the value chain from raw powder to standardised extract. Currency volatility remains the persistent brake on import-dependent formulations.

Middle East & Africa

Country 2025 Value (USD B) Key Driver
Saudi Arabia 1.90 Vision 2030 health localisation targets
UAE 1.48 Regional distribution and re-export hub
South Africa 1.34 Complementary medicines regulatory framework
Egypt 0.99 National staple fortification programme
Rest of MEA 1.34 Donor-funded micronutrient interventions


MEA grows fastest because it starts smallest and because policy is actively pulling demand forward. Saudi localisation targets are steering procurement toward suppliers with in-Kingdom presence, and halal certification has become a hard gate rather than a differentiator. Donor-funded micronutrient programmes across Sub-Saharan Africa add a large, price-sensitive premix layer that behaves independently of consumer retail cycles.


Nutraceutical Ingredient Market By Region, 2025-2035

Nutraceutical Ingredient Market Segmentation

Segmentation across the Nutraceutical Ingredient Market follows three commercially meaningful dimensions: product type, physical form, and downstream application.

By Product Type

Segment Metric (2025) Primary Demand Driver
Vitamins 26.5% share Fortification mandates and multivitamin baseload
Proteins & Amino Acids USD 21.16 Billion Sports and active nutrition expansion
Probiotics 7.4% CAGR Gut-health evidence and strain differentiation
Minerals 12.0% share Deficiency programmes and bone health
Prebiotics 9.5% share Fibre gap closure and synbiotic pairing
Omega-3 Fatty Acids USD 9.99 Billion Cardiovascular and cognitive positioning
Plant Extracts 7.0% share Botanical and traditional-medicine demand
Others 4.0% share Enzymes, carotenoids, specialty carbohydrates


Vitamins remain the volume anchor, and the segment's stability is regulatory rather than fashionable — fortification programmes buy the same premixes year after year regardless of consumer trend cycles. Probiotics are the profit story. Documented strains with named clinical trials command multiples of commodity culture pricing, and the shift toward spore-forming and next-generation strains is widening that gap. Within the Nutraceutical Ingredient Market, probiotics illustrate the broader migration from tonnage to intellectual property.

By Form

Segment 2025 Value (USD B) Primary Demand Driver
Powder 79.94 Capsule, tablet and premix compatibility
Liquid 37.62 Beverage fortification and pediatric dosing


Powder dominance is a logistics outcome as much as a technical one: dry actives ship cheaply, tolerate ambient storage and drop straight into existing tableting lines. Liquid grows faster where beverage brands need cold-stable, clear-solution actives, and emulsification technology is the constraint most suppliers in the Nutraceutical Ingredient Market are currently spending against.

By Application

Segment Metric (2025) Primary Demand Driver
Dietary Supplements 38.0% share Self-directed preventive health purchasing
Functional Food 27.5% share Mainstream retail reformulation
Functional Beverage 6.8% CAGR Energy, hydration and gut-health drinks
Animal Nutrition USD 12.34 Billion Antibiotic replacement and companion premiumisation
Others 5.0% share Medical foods and infant nutrition


Dietary supplements absorb the largest share because the channel tolerates higher active loadings and faster claim iteration than mainstream food. Functional beverages grow fastest, driven by gut-health and cognitive positioning in ready-to-drink formats. However, they impose the harshest technical constraints — clarity, taste masking and shelf stability all at once. That difficulty is precisely why beverage-grade actives carry premium pricing in the Nutraceutical Ingredient Market.


Competitive Benchmarking

Concentration is moderate. Market Research Future estimates a Herfindahl-Hirschman Index in the 550–700 range, with the top five suppliers accounting for roughly 28–33% of global revenue in the Nutraceutical Ingredient Market. Below that tier sits a long tail of regional botanical processors and single-category specialists. Consolidation is accelerating as documentation burdens rise, but no single player approaches dominance.

Company Est. Revenue Share Range Key Offerings for Nutraceutical Ingredient Market Strategic Positioning
DSM-Firmenich ~8–11% Vitamins, carotenoids, omega-3, cultures Broadest vertically integrated portfolio
Archer Daniels Midland ~6–9% Probiotics, proteins, fibres, botanical extracts Scale plus fermentation and health-and-wellness platform
Cargill ~5–8% Plant proteins, steviol glycosides, fibres, lipids Feedstock control and global supply reach
IFF (Danisco Health & Biosciences) ~5–7% Cultures, probiotics, HMOs, enzymes Strain library and clinical documentation depth
BASF ~4–6% Omega-3 concentrates, vitamins, carotenoids Chemistry-led process and purity leadership
Kerry Group ~3–5% Probiotics, proteins, botanical actives, taste systems Formulation partnership and co-development model
Glanbia Nutritionals ~3–5% Whey and milk proteins, premixes, bioactives Dairy protein specialisation with premix reach
Ingredion ~2–4% Prebiotic fibres, plant proteins, specialty starches Texture-plus-nutrition combination positioning
Tate & Lyle ~2–4% Soluble fibres, sweeteners, gut-health actives Fibre science and sugar-reduction anchoring
Lonza ~2–3% Capsules, delivery systems, specialty actives Delivery technology and pharma-grade compliance
Roquette ~2–3% Pea proteins, polyols, excipients Plant-protein scale and pharma crossover


Recent News & Developments

Deal activity and regulatory milestones since 2023 have reshaped supplier positioning across the Nutraceutical Ingredient Market.

  • DSM and Firmenich (May 2023): Completed their merger to form DSM-Firmenich, consolidating vitamins, cultures and taste under one roof and creating the sector's broadest single portfolio [17]
  • FSSAI (October 2023): Tightened labelling and composition rules for health supplements and nutraceuticals, raising compliance requirements for imported actives entering India [6]
  • ADM (March 2024): Expanded probiotics and postbiotics capacity in Valencia, Spain, targeting European gut-health demand with locally produced strains [18]
  • EFSA (July 2024): Issued positive Novel Food opinions clearing a multi-year backlog, opening EU commercialisation for several fermentation-derived actives [12]
  • Glanbia (November 2024): Acquired flavour and formulation assets to deepen its bioactive and premix capability beyond core dairy proteins [19]
  • Lonza (2024–2025): Progressed divestment of its Capsules & Health Ingredients unit, sharpening focus on biologics while releasing capacity to new ownership [20]
  • Saudi Food and Drug Authority (February 2025): Updated health supplement registration requirements, adding localisation incentives aligned with Vision 2030 procurement goals [21]
  • China SAMR (June 2025): Broadened the health food raw material filing catalogue, shortening time-to-market for qualifying vitamin and mineral formulations [22]


Nutraceutical Ingredient Market Report Scope

Parameter Detail
Market Scope Global supply of bioactive and functional ingredients for supplements, food, beverage and animal nutrition
Study Period 2021–2035 (Historical 2021–2024; Base Year 2025; Forecast 2026–2035)
CAGR 5.90% (2026–2035)
Market Size Checkpoints USD 117.56 Billion (2025); USD 124.50 Billion (2026); USD 208.56 Billion (2035)
Fastest Growing Segments Probiotics (product type); Functional Beverage (application); Middle East & Africa (region)
Companies Profiled 11 profiled suppliers including DSM-Firmenich, ADM, Cargill, IFF, BASF, Kerry Group, Glanbia, Ingredion, Tate & Lyle, Lonza, Roquette
Valuation Currency USD Billion

FAQs

What contract structures reduce supply risk when sourcing for the Nutraceutical Ingredient Market?
Multi-year index-linked agreements with dual-qualified sites work best for botanical actives. They cap price swings while preserving switching ability if a harvest fails [13].
How should buyers evaluate a supplier's clinical evidence package?
Check whether trials used the exact strain or extract ratio being sold, not a related material. Strain-specific human data with published outcomes is the only defensible standard [7].
Which certifications matter most for exporters entering the Nutraceutical Ingredient Market in the Gulf?
Halal certification from a recognised body plus SFDA product registration are mandatory gates. Local warehousing arrangements increasingly influence tender outcomes [21].
What are the main integration challenges when switching to fermentation-derived actives?
Particle size and dispersion behaviour usually differ from extracted equivalents, forcing process retuning. Budget for stability retesting across the full shelf-life window [10].
How does private-label growth affect margins in the Nutraceutical Ingredient Market?
Retailer private labels compress branded pricing, pushing ingredient suppliers toward volume contracts at thinner spreads. Differentiated actives with claim support largely escape this pressure [15].
Are medical foods a realistic adjacency for supplement ingredient suppliers?
Yes, though documentation demands approach pharmaceutical levels. Suppliers already running pharma-grade quality systems face the shortest path [24].
What emerging use case deserves the most attention over the next three years?
Cognitive and healthy-ageing formulations aimed at populations over 55. Demographic momentum makes this the most durable new demand pocket [9].      
Author
Author Author Profile Satyendra Maurya LinkedIn Research Analyst
An accomplished research analyst with high proficiency in market forecasting, data visualization, competitive benchmarking, and others. He holds a pronounced track record in research and consulting projects for sectors such as life sciences, medical devices, and healthcare IT. His capabilities in qualitative and quantitative analysis have resulted in positive client outcomes. Working on niche market trends, opportunities, sales, and forecasted value is part of his skill set.
Co-Author Co-Author Profile Vikita Thakur LinkedIn Senior Research Analyst
She holds an experience of about 5+ years in market research and business consulting projects for sectors such as life sciences, medical devices, and healthcare IT. She possesses a robust background in data analysis, market estimation, competitive intelligence, pipeline analysis market trend identification, and consumer behavior insights. Her expertise lies in technical Sales support, client interaction and project management, designing and implementing market research studies, conducting competitive analysis, and synthesizing complex data into actionable recommendations that drive business growth.
Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.
















